>>> Up
* Aker BP Raised to Buy at SEB Equities; PT 260 kroner
* Antin Raised to Buy at Citi; PT 14.90 euros
* Antofagasta Raised to Buy at Canaccord; PT 2,065 pence (+)
* AT&T Raised to Outperform at RBC; PT $26
* Barratt Redrow PLC Raised to Buy at Redburn; PT 540 pence
* Boeing Raised to Overweight at Barclays
* Booz Allen Raised to Equal-Weight at Barclays
* CNH Industrial Raised to Outperform at Bernstein (+)
* Currys Raised to Neutral at BNPP Exane (+)
* CVC Capital Raised to Buy at Citi; PT 25.30 euros
* Diversified Energy PT Raised to $27 from $21 at Truist Secs
* EnQuest Raised to Buy at Jefferies; PT 15 pence
* European Medtech Sector Upgraded at Morgan Stanley, Qiagen Cut
* Experian Raised to Outperform at RBC; PT 4,200 pence
* Hermes Raised to Buy at Stifel; PT 2,560 euros
* IPC Raised to Buy at Jefferies; PT 140 kronor
* Medacta Raised to Overweight at Morgan Stanley
* Oxford Nanopore Raised to Hold at Stifel; PT 135 pence (+)
* Persimmon Raised to Buy at Redburn; PT 1,510 pence
* Rexel Raised to Outperform at Bernstein (+)
* Sandvik Raised to Market Perform at Bernstein (++)
* Siemens PT Raised to 245 euros from 215 euros at Berenberg
* Spectris Raised to Buy at HSBC; PT 2,900 pence
* Tesla Raised to Hold at Punto Casa de Bolsa; PT $364.44
>>> Down
>>> Down
* ABB Cut to Underperform at Bernstein (+)
* Berkeley Cut to Neutral at Redburn; PT 4,460 pence
* Crest Nicholson Cut to Neutral at Redburn; PT 186 pence
* Energean Cut to Underperform at Jefferies; PT 800 pence
* Equinor Cut to Neutral at SpareBank; PT 290 kroner
* Equinor Cut to Neutral at SpareBank; PT 290 kroner
* Nexans Cut to Market Perform at Bernstein (++)
* Ocado PT Cut to 230 pence from 235 pence at Morgan Stanley
* Rolls-Royce Cut to Neutral at Citi; PT 641 pence
* Royal Unibrew Cut to Equal-Weight at Barclays; PT 653 kroner
* Signify Cut to Market Perform at Bernstein (++)
* T-Mobile Cut to Sector Perform at RBC; PT $240
* Unilever Cut to Underperform at RBC; PT 4,000 pence
>>> Initiation
>>> Initiation
* Bytes Technology Rated New Buy at Investec; PT 600 pence
* Ebiquity Rated New Buy at Cavendish; PT 78 pence (+)
* Epiroc Cut to Underperform at Bernstein (++)
* Hilton Grand Vacations Rated New Overweight at Morgan Stanley
* Marriott Vacations Rated New Underweight at Morgan Stanley
* Palantir Assumed Underweight at Morgan Stanley; PT $60
* Palantir Assumed Underweight at Morgan Stanley; PT $60
* Travel + Leisure Co Rated New Overweight at Morgan Stanley
>>> Call
>>> Call
* Currys Raised to Neutral at Exane as Retailers May Re-rate (+)
* European Medtech Sector Upgraded at Morgan Stanley, Qiagen Cut
* Ned Davis Warns It May Cut Exposure to US Equities After Selloff
* Rolls-Royce Shares Downgraded to Neutral at Citi on Valuation
* Rolls-Royce Shares Downgraded to Neutral at Citi on Valuation
* Unilever’s Outperformance Seems Excessive, RBC Downgrades
* JPMorgan Strategists See Europe Underperforming US For Longer (+)
* Morgan Stanley’s Wilson Says Rates Key Driver of Stocks in 2025 (+)
* RBC’s Calvasina Sees Bigger Gains for US Stocks as Bulls Fade (+)
Taking stock of the global EV sector
For those trying to gauge the health of the global electric vehicle sector, this year has begun with two sharply conflicting signals from the world’s two biggest EV producers. On January 1, China’s BYD announced that it had sold 4.3mn cars in 2024, nearly 20 per cent above its stated target. A day later, Elon Musk’s Tesla reported its first full-year sales decline for more than a decade.
The contrasting announcements highlight some key trends in a sector that has played a totemic role in the drive to decarbonise the world economy, and which is increasingly important in the global contest for industrial power.
China goes gangbusters
In late 2020, President Xi Jinping approved a strategy under which sales of “new energy vehicles” — including plug-in hybrid as well as pure electric cars — would reach a fifth of Chinese passenger car sales by 2025. China has far exceeded that target: in the second half of last year, NEV sales overtook those of combustion-engine cars.
The single biggest reason for this is the rapid advances that Chinese carmakers have made in reducing the cost of their vehicles. BYD, which now controls over a third of the domestic electric and hybrid car market, has been perhaps the most impressive performer on this front. Its lowest-cost electric car sells for less than $10,000.
Analysts at Bernstein estimated that BYD’s cost of production for EVs was 50 per cent lower than that of European rivals, thanks to economies of scale, vertical integration (it makes its own batteries and other parts) and robust local supply chains (China is dominant in many key commodities and components for the EV sector).
Tesla is a major player in China too, and it achieved a 9 per cent increase in sales in the country last year. But that was far behind the wider growth rate of nearly 40 per cent in the Chinese electric and plug-in hybrid market.
Western market growth has slowed
As a disruptive early mover in the US electric car market, it’s unsurprising that Tesla has been losing share as other carmakers got on the electric bandwagon. Tesla’s US market share in electric vehicles slipped below 50 per cent for the first time in the second quarter of last year.
A further headache for Tesla is that while EV sales are still growing in the US, the pace of growth has slowed significantly in its most important market. The proportion of EVs in new US car sales shot up from 3.4 per cent in late 2021 to nearly 8 per cent in late 2023 — but then dipped below that level for the next two quarters. Affordability has been a key challenge: carmakers have struggled to close the price gap between electric and petrol-powered cars, and higher interest rates have made consumers less willing to shoulder the extra cost.
The share is higher in Europe. EVs accounted for nearly a fifth of car sales last year in the UK, and roughly an eighth of sales in the EU. But EV sales in the EU fell by 6 per cent in the first nine months of last year, hit by a weakening of government subsidies. That effect was particularly stark in Germany, where sales fell by more than a quarter in the year to October.
Hybrid hype
Once widely seen as a pointless halfway measure, hybrid cars are enjoying something of a second wind, due in part to concerns about the speed of expansion of electric charging infrastructure.
The US in particular has seen a surge in sales of non-plug-in hybrids, which have a small battery that is charged by the petrol engine and by the friction from braking. Sales of these cars reached 10.6 per cent of the US light vehicle market in the third quarter of 2024.
In China, momentum has gathered behind plug-in hybrids, which have larger batteries that enable them to operate without using their petrol engine at all on shorter journeys. Sales of these vehicles rose by 70 per cent year on year in the first half of 2024, to reach a 42 per cent share of China’s NEV market.
As the world’s biggest producer of plug-in hybrids, BYD is perfectly placed to benefit from this trend. Last year it sold 2.5mn of these vehicles — a 73 per cent annual rise, comfortably outstripping the 1.8mn pure electrics that it sold. Tesla, with its firm commitment to battery power, receives no benefit from the growth in hybrid sales.
How much the planet benefits is another question. The International Council on Clean Transportation estimated last year that lifecycle emissions (from manufacturing as well as driving) for battery-powered cars were about 66 per cent lower than for conventional cars, or 83 per cent lower if they’re powered only by renewables. Meanwhile, the net emissions benefit for plug-in hybrids was about 40 per cent, and for non-plug-ins, about a quarter.
What next?
Tesla shares took only a modest hit from the disappointing numbers and had made back those gains by the weekend, to trade over 70 per cent higher than where they started 2024. This is in large part because Tesla is not valued like a normal car company, whether because of its cult following, its aggressive investments into other areas of technology, or its chief executive’s bromance with the incoming US president.
But there are more straightforward reasons to suspect that Tesla’s downbeat recent numbers may prove a prelude to stronger results in coming quarters. The company plans to start to production of “more affordable models” in the first half of this year. Tesla will also gain a competitive advantage against its rivals if Donald Trump, as expected, axes EV tax incentives created by Joe Biden’s Inflation Reduction Act.
BYD, meanwhile, looked set to benefit from a shakeout in the Chinese EV market, as weaker players failed amid intense price competition, said Yale Zhang, head of Shanghai-based consultancy Automotive Foresight. But the export prospects for it and other Chinese car companies look more difficult.
The EU, anxious to protect its own automotive industry, has imposed tough new tariffs on Chinese-made electric cars, arguing that the industry has received unfair state support. BYD is still hoping to crack into the European market with a new factory in Hungary (though it could face scrutiny after allegations that a subcontractor in Brazil subjected workers to “slavery”-like conditions). The US has in effect closed its market to Chinese EVs, with tariffs of 100 per cent.
Policymakers in the west hope these measures will pay off by giving their carmakers time to catch up with their Chinese rivals. In the meantime, warned automotive consultant Michael Dunne of Dunne Insights, “the pace of the transition is night and day between China and the rest of the world”.
If bitcoin is the future, what explains MicroStrategy’s need for speed?
Perpetual appreciation is a demanding ask for any asset class, and the company seems to know it. Saylor’s relentless proselytising for bitcoin — an odd choice for someone accumulating the asset — suggests an acute awareness of the stakes. It’s also no surprise that he is cultivating government support, meeting with President-elect Donald Trump’s son Eric (which preceded a sharp 13 per cent rise in the stock on Friday) and advocating for a Strategic Bitcoin Reserve. It’s an ironic twist for a cryptocurrency long touted as a bulwark against government meddling. But when your playbook hinges on unrelenting enthusiasm, pragmatism trumps principle.
Accelerating purchases, insider sales, and a rapidly evaporating premium
Something peculiar is afoot at MicroStrategy.
The company has amassed over two per cent of all bitcoin in existence, funded through a combination of shares and convertible bonds. This strategy has turned a humdrum business software firm into something akin to a bitcoin ETF, albeit one trading at a frothy premium to its net asset value. The stock is up over 20 times since the pivot to bitcoin in August 2020.
Yet recent months have revealed some curious contradictions in this narrative. While bitcoin has maintained its stratospheric altitude at around $100,000 per coin, MicroStrategy’s stock has drifted lower, shedding 40 per cent since peaking intraday on November 21 at $550, which implied at the time a market cap of $124bn. Even its inclusion in the Nasdaq 100 index failed to boost the share price. Its premium to net asset value has meanwhile decreased from a high of 3.8 times to 1.9 times. This decline in the share price is happening even as the company continues to acquire more bitcoin.
More telling still is the company’s frenetic execution of its $21bn “at-the-money” equity offering, announced with much fanfare on Hallowe’en. What was billed as a three-year marathon has been run at the pace of a sprinter on amphetamines, with over two-thirds of the allocation exhausted in just two months. This is odd behaviour for a strategy ostensibly designed for disciplined, incremental buying. There has been no buying on the dip. Even as bitcoin’s price has held firm near its peak, Michael Saylor, the company’s chair, has ramped up bitcoin purchases at breakneck speed.

According to JPMorgan analysts, MicroStrategy accounted for an astonishing 28 per cent of capital inflows into the cryptocurrency market in 2024.
There is also no time to waste. Last Friday the company announced plans to raise up to $2bn in perpetual preferred stock this quarter to buy more bitcoin, although the precise timing and terms have not yet been announced. This comes just over a week after MicroStrategy said it was seeking shareholder approval to increase its share count by over 3000 per cent from 330mn to 10.33bn.
The timing smacks of opportunism, as if the company’s leadership recognises that the current NAV premium — the financial equivalent of finding money growing on trees — might not be permanent. There’s a hint of urgency (or desperation) in the air, an extreme haste to lock in this discrepancy between MicroStrategy’s stock and the bitcoin price before it is arbitraged away.
Compounding the intrigue is the behaviour of MicroStrategy’s senior leadership. Saylor has publicly condemned diversification, urging investors to concentrate their portfolios in bitcoin with almost religious conviction. He has even suggested that people mortgage their homes to buy bitcoin!
His lieutenants, however, appeared to have missed the sermon, cashing in huge chunks of their stock holdings for the very fiat currency their boss routinely derides. November saw a flurry of insider selling, as executives converted their shares into good old-fashioned Yankee dollars. MicroStrategy shares may be a bitcoin proxy and so ostensibly a unique store of value, but with insider sales totalling $570mn in 2024, management is not HODLing the stock.
The paradoxes don’t stop there. In following its strategy MicroStrategy appears structurally predisposed to buying bitcoin at ever-higher prices. During the crypto winter of 2022-2023, when bitcoin wallowed in the teens and twenties, the company’s purchases slowed to a crawl as its stock traded around NAV. Yet as bitcoin’s price soared, so too did MicroStrategy’s buying frenzy. The business model seems less a bet on bitcoin’s inherent value and more a wager on the fervour it inspires.
The premium to NAV holds as long as bitcoin keeps ascending, and that premium is the glue that holds the entire strategy together. By selling stock at 2-3 times NAV, MicroStrategy is in effect buying bitcoin at a substantial discount. Without the NAV premium, the stock price falls, and much of the $7.2bn of convertible bonds outstanding risks being redeemed for cash at maturity, not converted into new shares. At that point, things get a lot stickier for MicroStrategy because its software business loses money and it generates no cash from bitcoin. (MicroStrategy trumpets a metric called “BTC yield”, which implies a return but really measures the percentage increase in bitcoin per share from its issue of stock and purchases of bitcoin. There is in fact no “yield” in the conventional sense of dividends or income streams.)

The question that lingers is whether MicroStrategy can maintain its premium valuation through sheer force of narrative much like the meme stocks that have defied conventional valuation metrics. The company has effectively become a publicly traded bet on bitcoin’s future, but one that still trades at a substantial mark-up to the underlying asset. This premium represents either the market’s faith in Saylor’s vision or a temporary, psychology-driven inefficiency waiting to be arbitraged away.
The whole affair feels like a high-stakes game of musical chairs, and as the tempo quickens, even the insiders seem to be hedging their bets. Whether MicroStrategy’s gambit will be remembered as a stroke of financial genius or a cautionary tale remains unresolved. For now, the music plays on, with the volume dialled up to 11, and the faithful — or the merely hopeful — keep dancing.
What’s Gustav Klimt’s Most Iconic Work? We’ve Ranked 10 of His Best
Here are 10 of our favorite works by Austrian artist to ignite your exploration.
“To speak the truth is to shine and burn,” Gustav Klimt inscribed on an early version of his provocative Nuda Veritas. Across time and distance—from Vienna’s Belle Époque to our own second Gilded Age—Klimt’s masterworks have never lost their luster.
Born in the Austrian Empire in 1862 and trained in the academic tradition, Klimt spearheaded the Vienna Secession at the turn of the century, declaring independence from the strictures of genre and school. Klimt’s personal vision culminated in a “golden phase” of portraits and allegories, rendered in lifelike scale and adorned with mesmerizing facets of gold leaf and pigment. The son of a goldsmith, the artist’s fascination with the shimmery hue was fueled by many influences.
In the decades since the artist’s death in 1918, his paintings have commanded some of the highest prices ever paid for individual works of art, led by Water Serpents II (1904–1907), which sold to Russian fertilizer mogul Dmitry Rybolovlev for $184 million in 2013.
Comprising hundreds of paintings and thousands of works on paper, Klimt’s oeuvre is as wide-ranging as it is radiant. Here are 10 of our favorite pieces to ignite your exploration.
10. Pine Forest II (1901)

Gustav Klimt, Pine Forest II (1901).
One of Klimt’s least showy compositions, the tiny glints of light it reveals are nothing short of magical. While Klimt is best known for his gold-inflected portraits, he painted many luminous landscapes, as well.
9. Jurisprudence (1899–1907)

Gustav Kilmt, Jurisprudence (1899–1907)
Known only through black-and-white photographs since its destruction or disappearance circa 1945, the psychosexual power of this underworldly scene is not lost on us. The painting was one of the artist’s three paintings for the University of Vienna, along with Medicine and Philosophy.
8. LakeAttersee (1900)

Gustav Klimt, Lake Attersee (Am Attersee) (1900). Courtesy of the Leopold Museum.
In this underrated, quietly luminous seascape, Klimt pushes painterly abstraction to a new and daring level.
7. Death and Life (1908–1911)

Gustav Klimt, Death and Life (1910/11). ©Leopold Museum, Vienna. Photo Courtesy of M. Thumberger.
The artist could not have foreseen the carnage of the Great War or the influenza pandemic that would claim 50 million souls including his own—yet he chose to reverse life and death’s customary order of precedence.
6. Water Serpents I (1904–1907)

Gustav Klimt, Water Serpents I (1904–1907).
The figures’ shimmering scales offer plausible deniability that this painting depicts same-sex love, 70 years before its decriminalization in Austria.
5. Nuda Veritas (1899)

Gustav Klimt, Nuda Veritas (1899). Courtesy of the Österreichisches Theatermuseum/Kunsthistorisches Museum Wien.
At once a familiar classical allegory and a radical confrontation, this painting boldly asserts that “to please everyone is bad.”
4. Judith and the Head of Holofernes (1901)

Gustav Klimt, Judith and the Head of Holofernes (1901). Photo: VCG Wilson/Corbis via Getty Images.
Unlike Caravaggio’s treatment of this biblical episode, Klimt focuses on the heroine herself rather than her violent act. Judith, for instance, depicts the ancient Jewish heroine, not in the violent physicality of her altercation with Holofernes, but in a pose of unbridled sensual conquest.
3. Beethoven Frieze (1901–1902)

Part of Gustav Klimt’s Beethoven Frieze (1902). Photo: Pierce Archive LLC/Buyenlarge via Getty Images.
This monumental work, painted directly on the walls of the Secession Building in Vienna, deftly borrows from Byzantine mosaics and Japanese woodblock prints to evoke the splendor of Beethoven’s final symphony.
2. Portrait of Adele Bloch-Bauer I (1903–1907)
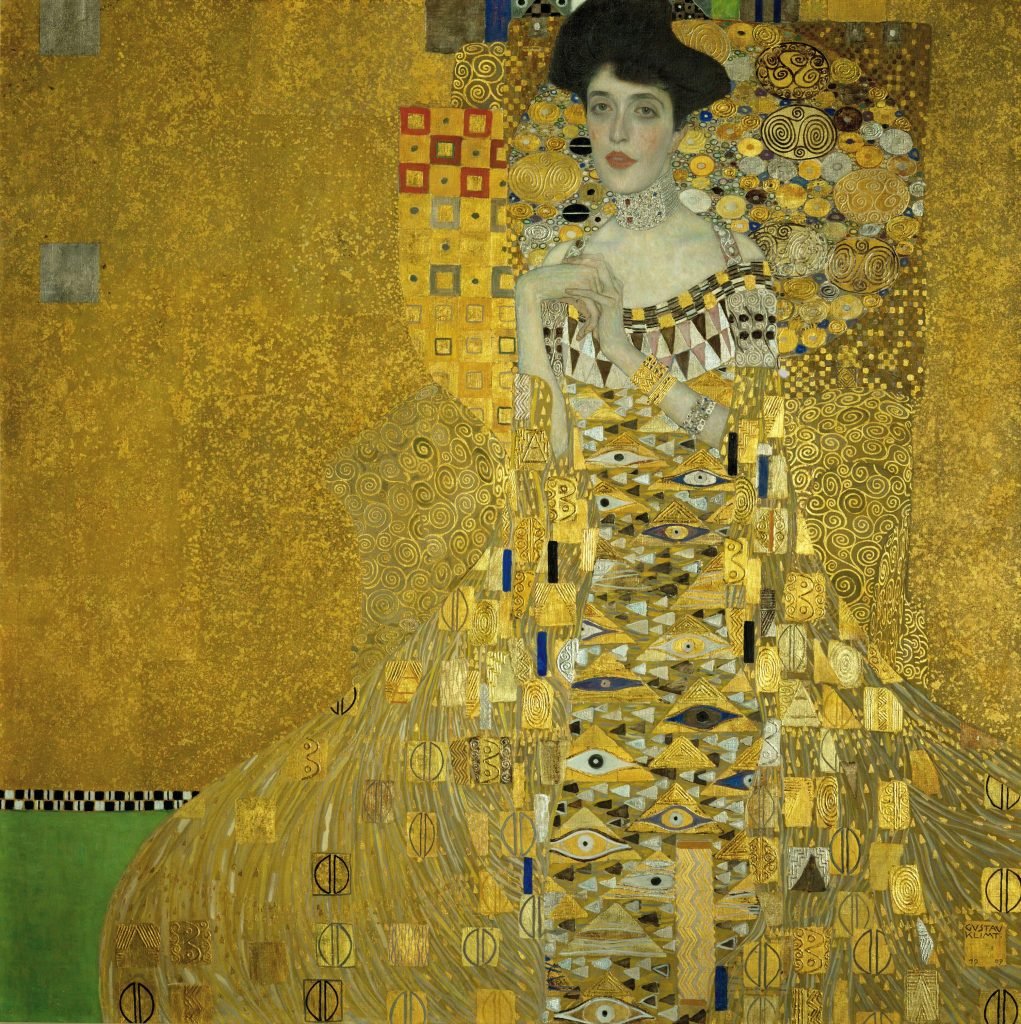
Gustav Klimt, Portrait Adele Bloch-Bauer (1907). Courtesy of Getty Images.
The centerpiece of a Supreme Court case, a record-shattering sale via Christie’s, and a biopic starring Helen Mirren and Ryan Reynolds, it is still impossible to overhype this paragon of Klimt’s ‘golden phase.’
1. The Kiss (1907–1908)
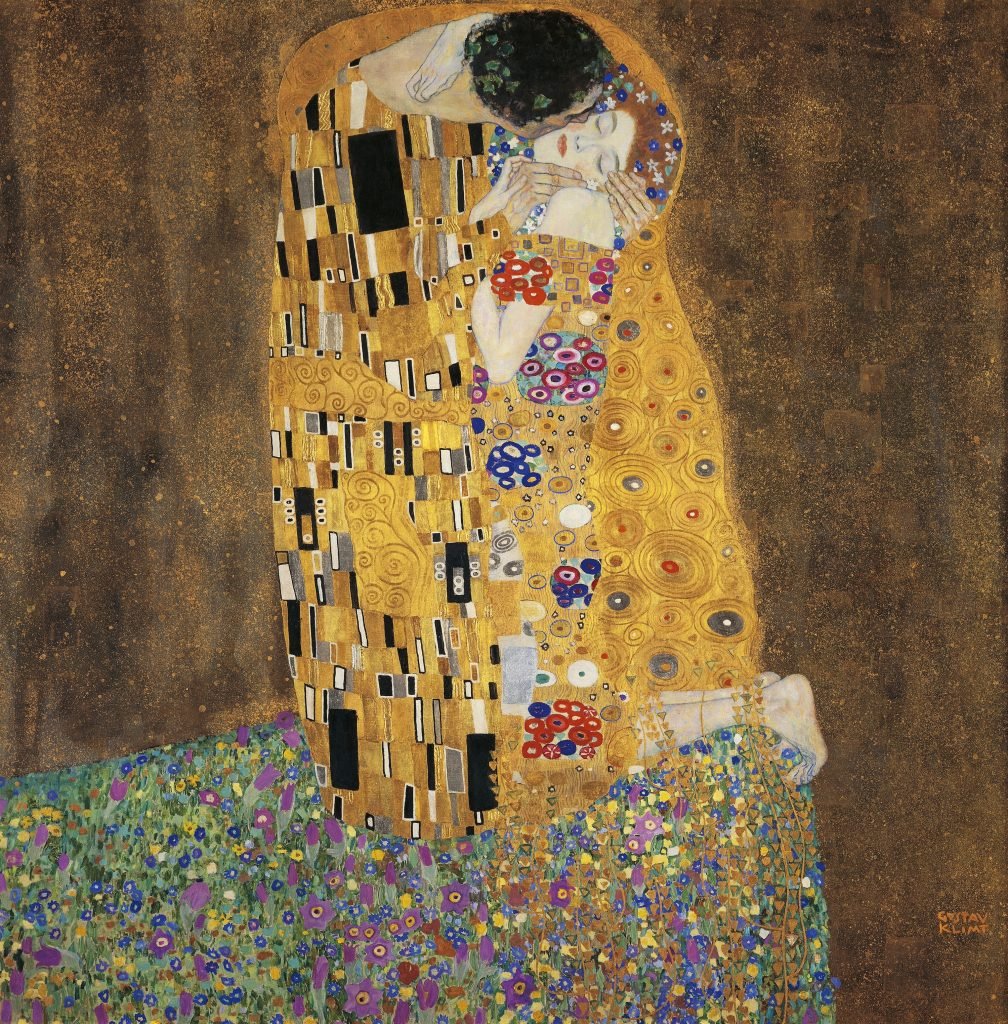
Gustav Klimt, The Kiss (1907). Photo by DeAgostini/Getty Images); Vienna, Österreichischer Galerie Belvedere (Art Gallery). Photo by DeAgostini/Getty Images.
This icon of Art Nouveau dynamism and dazzle was savvily purchased fresh off the easel by the Austrian government, and it remains one of the country’s most visited attractions—and one of the most beloved paintings in the world. The painting, which was created in the aftermath of a scandal, is rich with fascinating details.
Research Calls I
-
Upgrades:
- Advanced Energy (AEIS) upgraded to Buy from Neutral at Citigroup; tgt raised to $138
- Align Tech (ALGN) upgraded to Outperform from Market Perform at Leerink Partners; tgt raised to $280
- Amcor (AMCR) upgraded to Buy from Hold at Truist; tgt raised to $12
- Amcor (AMCR) upgraded to Buy from Neutral at Citigroup; tgt raised to $12
- American Airlines (AAL) upgraded to Buy from Hold at Melius; tgt $23
- American Airlines (AAL) upgraded to Buy from Hold at Jefferies; tgt raised to $20
- Amplitude (AMPL) upgraded to Overweight from Neutral at Piper Sandler; tgt raised to $15
- Arch Resources (ARCH) upgraded to Overweight from Neutral at Piper Sandler; tgt lowered to $150
- AvalonBay (AVB) upgraded to Outperform from Neutral at Mizuho; tgt raised to $242
- Banc of California (BANC) upgraded to Overweight from Equal Weight at Wells Fargo; tgt raised to $20
- Boeing (BA) upgraded to Overweight from Equal Weight at Barclays; tgt raised to $210
- Booz Allen Hamilton (BAH) upgraded to Equal Weight from Underweight at Barclays; tgt $140
- Capital One (COF) upgraded to Overweight from Equal Weight at Barclays; tgt raised to $219
- Capri Holdings (CPRI) upgraded to Outperform from Market Perform at BMO Capital Markets; tgt raised to $31
- Cardinal Health (CAH) upgraded to Buy from Neutral at BofA Securities; tgt raised to $145
- Chewy (CHWY) upgraded to Outperform from Neutral at Mizuho; tgt raised to $42
- Cisco (CSCO) upgraded to Buy from Hold at Melius; tgt raised to $73
- Citigroup (C) upgraded to Overweight from Equal Weight at Barclays; tgt raised to $95
- Columbia Banking (COLB) upgraded to Overweight from Equal Weight at Wells Fargo; tgt raised to $35
- Corebridge Financial (CRBG) upgraded to Overweight from Equal Weight at Barclays; tgt $37
- Discover Financial Services (DFS) upgraded to Overweight from Equal Weight at Barclays; tgt raised to $186
- Dutch Bros (BROS) upgraded to Outperform from Neutral at Robert W. Baird; tgt raised to $70
- Franklin Resources (BEN) upgraded to Neutral from Sell at Goldman; tgt raised to $22
- Quest Diagnostics (DGX) upgraded to Outperform from Market Perform at Leerink Partners; tgt raised to $174
-
Downgrades:
- Affiliated Managers (AMG) downgraded to Neutral from Buy at Goldman; tgt lowered to $191
- Ameriprise Financial (AMP) downgraded to Neutral from Buy at UBS; tgt lowered to $570
- Amkor (AMKR) downgraded to Hold from Buy at Melius; tgt lowered to $30
- AppFolio (APPF) downgraded to Neutral from Overweight at Piper Sandler; tgt $265
- BlackLine (BL) downgraded to Underweight from Neutral at Piper Sandler; tgt $60
- Cboe Global Markets (CBOE) downgraded to Sell from Neutral at Goldman; tgt $184
- CME Group (CME) downgraded to Neutral from Buy at Citigroup; tgt lowered to $250
- Commscope (COMM) downgraded to Underperform from Mkt Perform at Raymond James
- Dynatrace (DT) downgraded to Neutral from Buy at Guggenheim
- Salesforce (CRM) downgraded to Sell from Neutral at Guggenheim; tgt $247
- Others:
- Appian (APPN) initiated with a Sector Perform at Scotiabank; tgt $37
Gapping down
News:
News:
- SKE -7.6% (collected $45 million of gold stream funding on December 30, 2024 under its gold stream arrangement; provides progress update on Eskay Creek)
- SEPN -7.1% (names Gil Labrucherie as CFO)
- RARE -1.1% (EC extends approval of Evkeeza to children as young as 6-months old with HoFH)
Gapping up
In reaction to earnings/guidance:
In reaction to earnings/guidance:
- CMC +1.8%
Other news:
- FUBO +28.5% (fuboTV & Disney (DIS) nearing agreement to merge their online live TV units, according to Bloomberg)
- PPTA +18.4% (U.S. Forest Service issues permit for its Idaho antimony and gold mine, according to Reuters)
- NIU +7.3% (reports Q4 sales of 226,634 units)
- OCS +6.8% (announces positive OCS-05 Phase 2 ACUITY Trial in Acute Optic Neuritis, met primary safety endpoint and key secondary efficacy endpoints opening development pathways as a potential first-in-class neuroprotective therapy)
- VZLA +6.4% (announces 43% increase in measured and indicated mineral resources at Panuco, including 46 moz grading 640 G/T AGEQ in first measured resource estimate)
- SEDG +6.3% (SolarEdge Technologies announces safe harbor agreements with Sunrun (RUN) and one of the largest financers of residential solar installations in the United States; expects to reduce its headcount by approximately 400 employees)
- MRT +6.2% (announced the launch of its dynamic pricing model)
- SES +6.2% (unveils new AI-enhanced 2170 cylindrical cell for humanoid robotics applications at the 2025 CES Show)
- X +6% (Nippon Steel and U. S. Steel confirm multiple lawsuits in response to wrongful interference with the proposed acquisition of U. S. Steel)
- ALCO +5.4% (announces strategic transformation that includes the wind down of Alico Citrus' primary operations)
- UBER +5.1% (enters $1.5 bln accelerated share repurchase program)
- AEVA +4.8% (Aeva and Wideeye announce a joint demonstration of the industry's first functional Frequency Modulated Continuous Wave iin-cabin 4D LiDAR solution for passenger vehicles at CES 2025)
- XPEV +4.1% (XPeng and Volkswagen Group China announce a MOU to jointly build one of the largest super-fast charging networks in China)
- WULF +4% (announces December 2024 production and operations update: mines 158 bitcoin, achieves 9.7 EH/s)
- MSTR +4% (announces that it is targeting a capital raise of up to $2 billion through one or more public underwritten offering of perpetual preferred stock which will be senior to our class A common stock)
- CAN +3.9% (receives A15XP order from new US customer)
- VREX +3.9% (terminated the Equipment Credit Agreement since it was no longer needed following the consummation of the offering of the additional senior secured notes on December 20, 2024)
- BTBT +3.3% (filed a prospectus supplement on Jan 3, 2025 to register the offer, sale and issuance of up to an aggregate of US$1,000,000,000 of the Class A ordinary shares)
- CLSK +3.2% (releases December 2024 bitcoin mining update)
- JKS +2.7% (Perovskite Tandem Solar Cell Based on N-type TOPCon Sets New Record with Conversion Efficiency of 33.84%)
- GEV +2.6% (plans to invest $20 mln in Singapore to boost innovation in repair capabilities and technologies on next generation of its High efficiency, Air-cooled gas turbines)
- AGIO +2.5% (discloses that FDA approved an update to the U.S. Prescribing Information for PYRUKYND; now includes information regarding liver injury observed in patients with another condition)
- GILT +2.5% (received $9 million in orders from major satellite operators)
- IOT +2.3% (CEO and CTO adopted pre-arranged stock trading plan)
- AZUL +2.2% (successfully reaches individual settlement agreement)
- UMH +2.2% (Q4 operations update)
- CORZ +2.2% (December 2024 production and operations updates)
- DHT +1.6% (reports it purchased 1,481,383 of its own shares in the open market, equivalent to 0.9% of its outstanding shares, at an average price of $8.8899)
- GRMN +1.6% (Garmin and Qualcomm (QCOM) reveal next-gen digital cockpit solution powered by Snapdragon cockpit elite platform)
- DLB +1.4% (report Samsung and Google's new spatial audio format will take on Dolby Atmos this year, according to TheVerge.com)
- TENB +1.4% (CEO/Chairman unexpectedly passes away; expects to meet or exceed prior guidance)
- VRSN +1.4% (10% owner Warren Buffett's Berkshire Hathaway (BRK.A / BRK.B) bought another 20,044 shares worth approx. $4.1 mln)
- BWXT +1.3% (announces that it has successfully completed its acquisition of L3Harris' (LHX) Aerojet Ordnance Tennessee business as of January 3, 2025)
Withings’ Omnia is a full-size body-scanning health mirror
The Omnia is still very much in concept mode — a phenomenon popular in the automotive world that has since spilled over into consumer electronics. That is to say that Withings’ splashiest product of CES 2025 may never be a product. Among other things, a body-scanning smart mirror would likely be cost prohibitive for consumers.
According to Withings, Omnia is “not just a product — it’s a transformative experience that reimagines digital health possibilities.” Certainly the notion of a daily full-body health scan is appealing to many potential customers. It does, however, come on the heels of a decade of failed smart mirror projects.
The “conceptual product” would offer 360-degree body scans, offering up user insight into weight, along with heart and lung health. Other metrics like sleep, activity, and nutrition would presumably come from a connected wearable.
The mirror itself would be interactive via touch, coupled with the inclusion of a voice assistant. The Omnia could also serve as a telemedicine portal to healthcare professions, who would gain access to user metrics and offer advice accordingly.
Withings says the system is “currently in development,” pending things like clinical reviews and additional AI features. It does add, however, that some of the above features will be available in some form via the Withings app at some point later in 2025.