FT : Rich Russians head for UK in record numbers

Rich Russians are gaining entry to the UK in record numbers amid a worsening economic outlook in their home country.
The number of Russians who were granted investor visas this year has soared by 69 per cent, according to Home Office statistics. The visas gave foreigners from outside the EU a fast track to residence and citizenship in return for buying gilts worth £1m to £10m.

In the first nine months of the year, 162 investor visas were granted to Russians, compared with 96 in the same period of 2013, the figures show. The whole of 2013 saw only 118 investor visas granted to Russians, according to the data, which were first reported by The Sunday Times.
Falling oil prices, western sanctions against Moscow over its actions in eastern Ukraine, and a plummeting rouble have all taken a heavy toll on the Russian economy — sending capital flight to new heights and draining state coffers.
The rouble was down by up to 36 per cent last week, although a big interest-rate rise by the central bank saw it strengthen to end the week only 2 per cent weaker.
The most powerful and rich among Russian society have had a nervous time of late: the September arrest of Vladimir Yevtushenkov, one of Russia’s richest men — and a subsequent court ruling forcing his Sistema Group to hand its Bashneft oil company back to the state — triggered warnings both from tycoons and reform-minded government officials that the country’s investment climate was being undermined.
Mr Yevtushenkov was released from house arrest last week and attended a banquet hosted by President Vladimir Putin a day later with other oligarchs. His invitation sent shares in Sistema soaring by more than 300 per cent in intraday trading.
Investor visas have proved particularly popular with Russians and Chinese, but the British government is — for the first time in two decades — making them harder to obtain. New rules that came into force last month raised the minimum amount needed to £2m from £1m, and brought in restrictions on the nature of the investment.
Until the recent change, visa applicants had been permitted to spend a quarter of their total UK investment on property, but this is no longer allowed. Although the Home Office did not given a reason for its decision, it was widely considered to be a response to public anxiety about foreigners investing in London properties that remain vacant.
The Home Office’s independent immigration advisers calculated in February that the scheme resulted in about £500m of gilts investment a year, and said this would “barely fund two days’ worth of the national deficit”.

>>> ECB's Coene (Belgium): Would support the ECB govt bond purchases - Belgium p

ECB's Coene (Belgium): Would support the ECB govt bond purchases - Belgium press 
- Would help spur economic activity and fight off deflationary pressures.
- Says: "Since the beginning of 2014, we have systematically underestimated deflationary effects...if we were to find ourselves at the beginning of next year with negative inflation and fall into a deflationary spiral, the effects on the behaviour of households and businesses could be very negative."

>>> Vodafone tipped as potential bidder for Sky

Vodafone tipped as potential bidder for Sky 

Vodafone, an FTSE-100 mobile telecoms group, could be poised to make a takeover bid for the listed UK-based satellite television broadcaster Sky, the Sunday Express reported. The newspaper cited people familiar with the matter who said Vodafone could make an offer for Sky early next year.

The article went on to cite another source who said a Vodafone bid for Sky definitely could happen, with Vodafone keen to broaden its offering.

Vodafone and Sky both refused to comment, the report said.

An analyst cited by the newspaper predicted that Vodafone will acquire Sky next year. Sky would be a good strategic fit for Vodafone and would complementary in Germany, Italy and the UK.

Sky is reportedly in discussions with Vodafone already about hiring some of the mobile network’s infrastructure so that Sky can provide mobile services, the item said. The item did not name the original report.

Sky's market capitalisation stood at GBP 15.28bn (EUR 19.53bn) at the close of trading in London on Friday, 19 December.
Sunday Express

(BFW) Sika CEO Says Can’t Implement Saint-Gobain’s Goals: NZZaS


Sika CEO Says Can’t Implement Saint-Gobain’s Goals: NZZaS
2014-12-21 09:23:27.611 GMT


By Giles Broom
(Bloomberg) -- Sika’s management can’t understand Saint-
Gobain’s goals for business, plans can’t be implemented, CEO Jan
Jenisch is cited as saying in interview in NZZ am Sonntag.
* Sika to finish 2014 with double-digit growth,“good” profit
margin
* NOTE: Sika Family Seeking to Oust Board Members Opposing
Sale


For Related News and Information:
First Word scrolling panel: FIRST<GO>
First Word newswire: NH BFW<GO>

To contact the reporter on this story:
Giles Broom in Geneva at +41-22-317-9212 or
gbroom@bloomberg.net
To contact the editor responsible for this story:
Mark Bentley at +49-699-204-1262 or
mbentley3@bloomberg.net

Wiwo : ECB Vice Constancio warns of 'dangerous vicious circle "

ECB Vice Constancio warns of 'dangerous vicious circle "

Oil prices steadily falling stir at the European Central Bank, the fear of deflation. ECB Vice Constancio warns of a "dangerous vicious circle".

"In the short term this creates a not an easy situation for us," admitted ECB Vice President Vitor Constancio an interview with Business Week. "We now expect a negative inflation rate in the coming months. That's one thing that has to look at each central bank very closely."

The original estimate of the ECB inflation for 2015 from 0.7 per cent is already out of date for the ECB Vice. "Since the drafting of these projections, oil prices have fallen by a further 15 percent." The ECB must now prevent a downward spiral. It threatens "a dangerous vicious circle of falling prices, rising real wages, falling profits, shrinking demand and prices continue to fall," warned the ECB Vice-President. "The economy would slip into recession." Currently, many experts predicted that the economic slowdown will continue in the euro zone by 2018. Constancio: "Until then, so there is downward pressure on inflation expectations."

Currently, the euro-zone but location is not in deflation. "A few months with negative inflation rates mean deflation. These negative inflation rates must be over a longer period of time," said Constancio. "If it is only a temporary phenomenon, then I see no danger begin. Deflationary tendencies when the company and the people change their behavior and postpone investments and expenses."

There is also a risk of deflation does not consist in all euro area countries. "In countries such as Spain and Ireland, whose economy is slowly recovering, increasing productivity. This creates scope for wage increases, which counteract the threat of deflation," Constancio said the former President of the Banco de Portugal was.

In the fight against deflation, the ECB had to use all possible resources, including the controversial purchase of government bonds, which had recently criticized Bundesbank President Jens Weidmann. "We need to use all monetary policy instruments at our disposal," Constancio said. "Is basically quantitative easing, everyone is talking about now, nothing more than a traditional open market operation, ie about the possibility of a central bank, securities, government bonds, to buy in the secondary market or sell to control the monetary base. This is perfectly legal. And what is legal, we do not exclude. " There is nevertheless at the ECB "not an obsession, necessarily to buy government bonds."

Constancio sees no danger bubble in the stock and real estate markets

The European Central Bank keeps warnings of a bubble in the financial markets is unfounded. "In the US, the price-earnings ratio of the shares is somewhat higher than the historical average -. But not in Europe here I do not see any significant overvaluation of equity markets," said ECB Vice President Vitor Constancio in an interview with Business Week. "Even in corporate bonds, we can not recognize such overvaluation." Similar to the situation in the real estate markets is. In some euro area countries, prices have risen in recent years significantly, such as Belgium and Ireland. In Belgium, the national supervisory authorities had already responded and increased capital requirements for mortgage loans. In Ireland there are now more stringent capital requirements. "Overall, I see no danger for Europe a new house price bubble," said Constancio.

Special Situations: Carrefour Bingo 1: Eur 24.3 - target remains North of

Special Situations: Carrefour Bingo 1:  Eur 24.3 - target remains North of 40 - BUY re-iterated

Special Situations: Carrefour (CA FP)

trade action flash – bingo 1: monetization of Brazil – BUY again

CA FP: EUR 24.3; target: Eur 40+

December 19, 2014

Carrefour announced it was selling 10% of its Brazilian business to Abilio Diniz for BRL20.4bn.  The figure is within our expected range particularly given the depreciation of the Reais vs. Euro (10%).  As we had been arguing forcefully since Mr. Plassat was appointed CEO, the Carrefour Brazil business, one of the group’s main assets, is being monetized with a clear price tag put on it.  That Mr. Diniz bought the stake is no surprise either.  This is what we had written in our April 16, 2012 report:

“Carrefour has the ability to price some of its most important assets via partial IPOs, spin-offs (it did it already with its Spanish discount chain, returning more than Eur 2bn to shareholders). In particular, it could list its Brazilian business, or issue tracking shares for it, or even possibly sell it to Abilio Diniz when he is cashed out of CBD by Casino (or more likely a combination of IPO with Diniz taking a significant stake).”

Our scenario for Carrefour is unfolding exactly as we thought.  Mr. Diniz is taking a substantial stake that he can increase to 16%.  No doubt that the IPO will come in due course, in particular when the Brazilian market returns to a more bullish stance. The fact Mr. Diniz is becoming a significant shareholder is extremely good news for Carrefour. He is one of Brazil’s most emblematic business leader, having built the country’s largest and most successful supermarket chain (Pao de Acucar – PCAR4 BZ) and sold it to Casino.

With Brazil partially done, we continue to think that Carrefour’s next major restructuring news will be the monetization of its huge real estate portfolio.  Our target remains North of Eur 40.

As an aside, we recommend to close the short Casino stub we had recommended as a hedge in our May 9 2014 report.  The stub value (Casino ex Pao de Acucar and Mercyalis) went down by over 20% since then.


>>> The Biggest Economic Story Going Into 2015 Is Not Oil


The Biggest Economic Story Going Into 2015 Is Not Oil

Isn’t it fun to just watch the market numbers roll by from time to time as you go about your day, see Europe markets up 3%+, Dubai 13%, US over 2% (biggest two-day rally since 2011!), and you just know oil must get hit again? Well, it did. WTI down another 3%+. I tells ya, no Plunge Protection is going save this sucker.
And oil is not even the biggest story today. It’s plenty big enough by itself to bring down large swaths of the economy, but in the background there’s an even bigger tale a-waiting. Not entirely unconnected, but by no means the exact same story either. It’s like them tsunami waves as they come rolling in. It’s exactly like that.
That is, in the wake of the oil tsunami, which is a long way away from having finished washing down our shores, there’s the demise of emerging markets. And I’m not talking Putin, he’ll be fine, as he showed again today in his big press-op. It’s the other, smaller, emerging countries that will blow up in spectacular fashion, and then spread their mayhem around. And make no mistake: to be a contender for bigger story than oil going into 2015, you have to be major league large. This one is.
The US dollar will keep rising more or less in and of itself, simply because the Fed has ‘tapered QE’, and much of what happened in global credit markets, especially in emerging markets, was based on cheap and easily available dollars. There’s now $85 billion less of that each month than before the taper took it away in $10 billion monthly increments. The core is simple.
This is not primarily government debt, it’s corporate debt. But it’s still huge, and it has not just kept emerging economies alive since 2008, it’s given them the aura of growth. Which was temporary, and illusionary, all along. Just like in the rest of the world, Japan, EU, US. And, since countries can’t – or won’t – let their major companies fail, down the line it becomes public debt.
One major difference from the last emerging markets blow-up, in the late 20th century, is size: emerging markets today are half the world economy. And they’re about to be blown to smithereens. Sure, oil will play a part. But mostly it will be the greenback. And you know, we can all imagine what happens when you blow up half the global economy …
Erico Matias Tavares at Sinclair has a first set of details:
There are some signs of trouble in emerging markets. And the money at risk now is bigger than ever. The yield spread between high grade emerging markets and US AAA-rated corporate debt has jumped, almost doubling in less than three weeks to the highest level since mid-2012.


MSCI Emerging Markets Index and Yield Spread between High Grade Emerging Markets and US AAA Corporates: 14 March 2003 – Today. Source: US Federal Reserve.

This means that the best credit names in emerging markets have to pay a bigger premium over their US counterparts to get funding. When this spread spikes up and continues above its 200-day moving average for a sustained period of time, it is typically a bad sign for equity valuations in emerging markets, as shown in the graph above. One swallow does not a summer make, but it is worthwhile keeping an eye on this indicator.


As yields go up the value of these emerging market bonds goes down, resulting in losses for the investors holding them. The surge of the US dollar in recent months could magnify these losses: if the bonds are denominated in local currency they will be worth a lot less to US investors; otherwise, the borrowers will now have to work a lot harder to repay those US dollar debts, increasing their credit risk. Any losses could end up being very significant this time around, as demand for emerging markets bonds has literally exploded in recent years.


Average Annual Gross Debt Issuance ($ billions, percent): 2000 – Today. Source: Dealogic, US Treasury. Note: Data include private placements and publicly-issued bonds. 2014 data are through August 2014 and annualized.

As the graph above shows, the issuance of emerging market corporate debt has risen sharply since the depths of the 2008-09 financial crisis.These volumes are very large indeed, and now account for non-trivial portions of investors’ and pension funds’ portfolios worldwide.


As a result, emerging markets corporations are now leveraged to the hilt, easily exceeding the 2008 highs by almost a multiple to EBITDA. And why not? With foreign investors desperate for yield as a result of all the stimulus and money printing by their central banks, they were only too happy to oblige. And they were not alone. Governments in these countries were also busy doing some borrowing of their own, as their domestic capital markets deepened.


[..] foreign investors have also piled into locally denominated bonds of emerging markets governments. Countries like Peru and Latvia now have over 50% foreign ownership of their bonds. [..] But there are big speculative reasons behind the recent money flows going into these countries – which could reverse very quickly should the tide turn. [..]


If investors end up rushing for the emerging markets exit for whatever reason, with this unprecedented level of exposure they might be bringing home much more than a bruised ego and an empty wallet. For one, European banks are hugely exposed to emerging markets. Any impairment to their books would likely make any new lending even more difficult, at a time when there is already a dearth of non-government credit in Europe.


And if emerging economies falter, where will the growth needed to repair Western government and private balance sheets come from? It used to be said that when the US economy sneezes the rest of the world catches a cold. Now it seems all we need is a hiccup in emerging markets.

That’s what you get when emerging markets are both half the global economy AND they’ve accomplished that level off of ultra-low US Fed interest rates and ultra-high US Fed credit ‘accommodation’. All you have to do when you’re the Fed is to take both away at the same time, and you’re the feudal overlord.
Our favorite friend-to-not-like Ambrose Evans-Pritchard does what he does well: provide numbers:
The US Federal Reserve has pulled the trigger. Emerging markets must now brace for their ordeal by fire. They have collectively borrowed $5.7 trillion in US dollars, a currency they cannot print and do not control. This hard-currency debt has tripled in a decade, split between $3.1 trillion in bank loans and $2.6 trillion in bonds. It is comparable in scale and ratio-terms to any of the biggest cross-border lending sprees of the past two centuries.


Much of the debt was taken out at real interest rates of 1% on the implicit assumption that the Fed would continue to flood the world with liquidity for years to come. The borrowers are “short dollars”, in trading parlance. They now face the margin call from Hell as the global monetary hegemon pivots. The Fed dashed all lingering hopes for leniency on Wednesday. The pledge to keep uber-stimulus for a “considerable time” has gone, and so has the market’s security blanket, or the Fed Put as it is called. Such tweaks of language have multiplied potency in a world of zero rates.


Officials from the BIS say privately that developing countries may be just as vulnerable to a dollar shock as they were in the Fed tightening cycle of the late 1990s, which culminated in Russia’s default and the East Asia Crisis. The difference this time is that emerging markets have grown to be half the world economy.Their aggregate debt levels have reached a record 175% of GDP, up 30 percentage points since 2009.


Most have already picked the low-hanging fruit of catch-up growth, and hit structural buffers. The second assumption was that China would continue to drive a commodity supercycle even after Premier Li Keqiang vowed to overthrow his country’s obsolete, 30-year model of industrial hyper-growth, and wean the economy off $26 trillion of credit leverage before it is too late. [..]


Stress is spreading beyond Russia, Nigeria, Venezuela and other petro-states to the rest of the emerging market nexus, as might be expected since this is a story of evaporating dollar liquidity as well as a US shale supply-glut.


[..[ the Turkish lira has fallen 12% since the end of November. The Borsa Istanbul 100 index is down 20% in dollar terms. Indonesia had to intervene on Wednesday to defend the rupiah. Brazil’s real has fallen to a 10-year low against the dollar, as has the index of emerging market currencies. Sao Paolo’s Bovespa index is down 23% in dollars in 3 weeks.
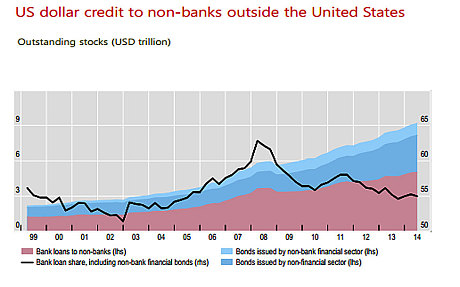
The slide can be self-feeding. Funds are forced to sell holdings if investors take fright and ask for their money back, shedding the good with the bad. Pimco’s Emerging Market Corporate Bond Fund bled $237m in November, and the pain is unlikely to stop as clients discover that 24% of its portfolio is in Russia.


One might rail against the injustice of indiscriminate selling. Such are the intertwined destinies of countries that have nothing in common. The Fed has already slashed its bond purchases to zero, withdrawing $85bn of net stimulus each month. It is clearly itching to raise rates for the first time in seven years. This is the reason why the dollar index has jumped 12% since May, smashing through its 30-year downtrend line, a “seismic change” in the words of HSBC. [..]


World finance is rotating on its axis, says Stephen Jen, from SLJ Macro Partners. The stronger the US boom, the worse it will be for those countries on the wrong side of the dollar.


“Emerging market currencies could melt down. There have been way too many cumulative capital flows into these markets in the past decade. Nothing they can do will stop potential outflows, as long as the US economy recovers.
Hold it there for a moment. I don’t think it’s the US economy (its recovery is fake), it’s the US dollar.
Will this trend lead to a 1997-1998-like crisis? I am starting to think that this is extremely probable for 2015,” he said.


This time the threat does not come from insolvent states. They have learned the lesson of the late 1990s. Few have dollar debts. But their companies and banks most certainly do, some 70% of GDP in Russia, for example. This amounts to much the same thing in macro-economic terms. Private debt morphs into state debt since governments cannot allow key pillars of their economies to collapse.


These countries have, of course, built $9 trillion of foreign reserves, often the side-effect of holding down their currencies to gain export share. This certainly provides a buffer. Yet the reserves cannot fruitfully be used in a recessionary crisis because sales of foreign bonds automatically entail monetary tightening. [..]


.. these reserves are a mirage. If you deploy them in such circumstances, you choke your own economy unless you can sterilize the effects. [..]


Investors are counting on the European Central Bank to keep the world supplied with largesse as the Fed pulls back. Yet the ECB could not pick up the baton even if it were to launch a blitz of quantitative easing, and there is no conceivable consensus for action on such a commensurate scale.


The world’s financial system is on a dollar standard, not a euro standard. Global loans are in dollars. The US Treasury bond is the benchmarks for global credit markets, not the German Bund. Contracts and derivatives are priced off dollar instruments. Bank of America says the combined monetary stimulus from Europe and Japan can offset only 30% of the lost stimulus from the US.
What more can I say? This is the lead story as we go into 2015 two weeks from today. Oil will help it along, and complicate as well as deepen the whole thing to a huge degree, but the essence is what it is: the punchbowl that has kept world economies in a zombie state of virtual health and growth has been taken away on the premise of US recovery as Janet Yellen has declared it.
It doesn’t even matter whether this is a preconceived plan or not, as some people allege, it still works the same way. The US gets to be in control, for a while, until it realizes, Wile E. shuffle style, that you shouldn’t do unto others what you don’t want to be done unto you. But by then it’ll be too late. Way too late.
As I wrote just a few days ago in We’re Not In Kansas Anymore, there’s a major reset underway. We’re watching, in real time, the end of the fake reality created by the central banks. And it’s not going to be nice or feel nice. It’s going to hurt, and the lower you are on the ladder, the more painful it will be. Be that globally, if you live in poorer countries, or domestically, if you belong to a poorer segment of the population where you are. In both senses, the poorest will be hit hardest.
It’s the new model along which the clowns we allow to run the show, do so. Unless ‘we the people’ take back control, it’s pretty easy to see how this will go down.
*  *  *
Still not convinced... Barclays notes this is already one of the worst sell-offs in EM credit since the crisis...

WSJ : China’s Xiaomi Raises Over $1 Billion in Investment Round

China’s Xiaomi Raises Over $1 Billion in Investment Round
Funding Values the Chinese Smartphone Maker at More Than $45 billion, a Source Says

HONG KONG—Xiaomi Corp. is raising more than $1 billion in its latest round of funding, valuing the fast-growing Chinese smartphone maker at more than $45 billion and making it one of the most valuable technology startups in the world, a person familiar with the matter said.

The round, which could close as early as Monday, is led by All-Stars Investment, a tech investment fund run by former Morgan Stanley analyst Richard Ji, the person said. Other participants in the round include Russian investment firm DST Global and Singapore sovereign-wealth fund GIC, which are both already shareholders of Xiaomi.

Yunfeng Capital, a private-equity firm affiliated with Alibaba Group Holding Ltd. Executive Chairman Jack Ma , is also participating in the round.

A Xiaomi spokesman declined to comment.

The $45 billion-plus valuation puts Xiaomi above most other Silicon Valley and Asian technology startups. Earlier this month, U.S. ride-sharing service Uber Technologies Inc. said a new round of funding valued it at $41 billion.

The surge in Xiaomi’s valuation over the past year indicates just how high expectations are as the company expands its business outside China, mainly in emerging markets where there is robust demand for inexpensive smartphones. In its previous round of funding in August 2013, Xiaomi was valued at $10 billion.

Xiaomi, founded by Lei Jun in 2010, has grown rapidly to become the top-selling smartphone vendor in China by offering affordable phones with features rivaling high-end models. Xiaomi phones come with its own customized version of Google Inc. ’s Android operating system, and the company frequently updates the software based on requests from users.

In the second quarter, Xiaomi overtook Samsung Electronics Co. as China’s biggest smartphone maker by shipments for the first time, according to research firm Canalys. This year, Xiaomi expects to sell 60 million units globally, up from 18.7 million in 2013.