Asian Market Update: Improving China trade and continued pause in Yuan devaluation help equities recover
***Economic Data***
- (CN) CHINA DEC TRADE BALANCE (IN CNY): 382B V 339BE; USD terms: $60.1B v $51.3BE
- (AU) AUSTRALIA SEPT-NOV JOB VACANCIES Q/Q: 3.5% V 3.5% PRIOR
- (JP) JAPAN DEC M2 MONEY STOCK Y/Y: 3.0% V 3.3%E; M3 MONEY STOCK Y/Y: 2.5% V 2.7%E
- (NZ) NEW ZEALAND DEC QV HOUSE PRICES Y/Y: 14.2% V 15.0% PRIOR
- (KR) SOUTH KOREA DEC UNEMPLOYMENT RATE: 3.4% V 3.5%E
- (KR) SOUTH KOREA DEC IMPORT PRICE INDEX M/M: -1.0% V -1.7% PRIOR; Y/Y: -11.9% V -15.6% PRIOR
- (KR) South Korea NOV Money Supply L: 0.4% v 0.7% prior; M2: 0.4% v 0.1% prior
***Index Snapshot (as of 05:00 GMT)***
- Nikkei225 +2.7%, S&P/ASX +1.3%, Kospi +1.3%, Shanghai Composite -0.9%, Hang Seng +2.1%, Mar S&P500 +0.9% at 1,942
***Commodities/Fixed Income***
- Feb gold -0.2% at $1,084/oz, Feb crude oil +1.1% at $30.79/brl, Mar copper +0.6% at $1.97/lb
- (US) API Petroleum Inventories: Crude: -3.9M v -5.6M prior; 2nd straight draw
- (HK) Offshore overnight yuan HIBOR 8.3% v 66.8% yesterday
- USD/CNY: *(CN) PBOC SETS YUAN MID POINT AT 6.5630 V 6.5628 PRIOR; 4th straight firmer setting relative to Close
- (JP) Japan MoF sells ¥500B in 0.1% 10-year CPI-linked Bonds; Bid-to-cover ratio: 2.47x v 2.21x prior
- (AU) Australia MoF (AOFM) sells A$900M in 4.25% 2026 Bonds; avg yield: 2.755%; bid-to-cover: 2.82x
***Market Focal Points/FX***
- Asian equities are tracking the gains on Wall St, with more positive regional developments helping in broad-based market recovery. Continued pause on currency devaluation by the PBoC along with stronger than expected China trade data have lifted risk-on sentiment across the asset classes. Nikkei225 is in the lead among the indices, boosted by weaker JPY, as USD/JPY rose some 70pips above 118.30. AUD/USD and NZD/USD are both up 70pip with respective highs of 0.7050 and 0.6590. Even crude oil has joined the rebound with 1.3% rise in electronic trade above $30.80, while copper is up 0.7% at $1.97.
- PBoC has strengthened Yuan relative to prior close for the 4th straight session, easing investors' concerns over potential outflows from China. After yesterday's record high HIBOR setting, demand for ammunition to short the currency in Hong Kong has also retreated, as today's HIBOR rate plunged back to 8.3% from 66.8%. Note this is still significantly higher than the long-term average below 4%. Finally, efforts to weaken the Chinese currency over the past few months have finally paid off in the trade data. December surplus in both CNY and USD terms was much higher than expected, as exporters benefited. In Yuan terms, outbound shipments rose +2.3% v -4.1%e, and in USD, decline was just -1.4% v -8.0%e. Imports declines were also not as severe as expected - in CNY -4.0% v -7.9%e and in USD -7.6% v -11.0%e. Shipments to Europe resumed growth, decline in Japan exports was cut in half below 5%, and US exports improved to -3.7% v -5.3% prior. Customs Office did acknowledge that challenges remain in China trade development, and that authorities will monitor exchange rate changes.
- President Obama's last State of the Union address brushed in broad strokes on achievements of his administration and largely reinforced the policy objectives of his cabinet. POTUS called US economy the most durable in the world, called for more affordable education, cheered accomplishments of ACA in insuring 18M Americans, and continued to push for greater use of clean energy. The speech was missing any reference to the 10 US Navy personnel held by Iranian officials after two of their vessels floated into Iranian waters. Secretary of State Kerry in contact with Iran authorities and have received assurances the sailors are safe and will be promptly released.
***Equities***
US equities / ADRs:
- CYBR: Check Point reportedly in talks to acquire CyberArk - Haaretz; +13.2% afterhours
- MET: Approves plan to pursue separation of U.S. Retail Business (about 20% of op earnings); +6.0% afterhours
- TREE: Raises FY15 guidance for adj EBITDA $38.8-39.8M, R$252.5-253.5M v $247Me (adj EBITDA $38.3-38.8M, R$244-247M prior); +4.5% afterhours
- YUM: Reports prelim China Dec SSS y/y: +1% vs -3% in Nov; Reports prelim China Q4 SSS +2% y/y (guided 0-4% on Dec 10th); +2.5% afterhours
- TSCO: Reports prelim Q4 $0.81-0.82 v $0.90e, R$1.65B v $1.73Be, SSS -1.4%; -1.0% afterhours
- WBMD: Guides Q4 Rev slightly above prior guidance range (implies above $191M v $188Me) - filing; -1.5% afterhours
- F: Guides 2016 pre tax profit equal to or higher y/y; approves $0.25 special dividend (1.9% yield); -1.8% afterhours
- CSX: Reports Q4 $0.48 v $0.46e, R$2.78B v $2.92Be; Guides FY16 EPS down y/y and below consensus; -1.9% afterhours
Key movers in Asia:
- Vanke 2202.HK +1.6% (said to request largest shareholder to cut holding)
- Wanda Cinema 002739.CN -2.2% (acquisition)
- TCL Multimedia Technology 1070.HK +1.6% (profit alert)
- Shanghai Jinjiang International Hotels Development Co Ltd 600754.CN +7.3% (Shanghai Disney Park sets opening date)
- China Unicom 762.HK +4.7%, China Telecom 728.HK +5.1% (resource share agreement)
CGG Announces the launch of €350M rights offering (90.7% of market cap)
CGG announces the launch of ~ EUR350 million rights offering maintaining shareholders' preferential subscription rights AS PART of its transformation plan
- Subscription ratio: 3 new shares for 1 existing share
- Subscription price: EUR0.66 per new share
- Subscription period: 14 January 2016 to 27 January 2016 inclusive
CGG announces the launch of ~ EUR350 million rights offering maintaining shareholders' preferential subscription rights AS PART of its transformation plan
- Subscription ratio: 3 new shares for 1 existing share
- Subscription price: EUR0.66 per new share
- Subscription period: 14 January 2016 to 27 January 2016 inclusive
The net proceeds of the issuance will be used to reinforce the shareholders' equity of CGG and improve its liquidity as it finances its Transformation Plan. The net proceeds will therefore be used principally to cover the shortfall in the consolidated net working capital of CGG of approximately U.S.$175 million for 2016 and, secondly, to finance its activities, which will permit CGG to reduce its reliance on drawings under the Group's revolving credit facilities.
--> Link to original press Release : http://bit.ly/1ZjTxMe
PARTAGE DE RÉSEAUX MOBILES
L'ARCEP met en consultation publique un projet de lignes directrices sur l'itinérance et la mutualisation des réseaux mobiles
Paris, le 12 janvier 2016
L'ARCEP soumet à consultation publique son analyse
La loi pour la croissance, l'activité et l'égalité des chances économiques, publiée le 7 août 2015, a conféré un nouveau pouvoir à l'ARCEP : celui de demander à des opérateurs la modification de leurs contrats de partage de réseaux mobiles, notamment lorsque cela est nécessaire à la réalisation de ses objectifs de régulation.
Afin de donner de la visibilité au secteur sur les conditions dans lesquelles elle entend mettre en œuvre son nouveau pouvoir, l'ARCEP soumet aujourd'hui à consultation publique un document de travail comprenant un projet de lignes directrices sur le partage de réseaux mobiles, accompagné de premières analyses sur les contrats existants. Y sont notamment identifiées les évolutions qui apparaissent a priori souhaitables dans les accords de partage de réseaux mobiles existants. Les acteurs intéressés sont invités à commenter ces éléments d'ici le 23 février 2016. Le document sera également transmis pour avis à l'Autorité de la concurrence. Les premières analyses présentées sont ainsi susceptibles d'évoluer en fonction des réponses à ces consultations.
L'ARCEP souligne que le document qu'elle met en consultation publique aujourd'hui a été élaboré en prenant en compte la structure actuelle du marché à quatre opérateurs de réseaux mobiles en métropole. Les premières analyses présentées pourraient ainsi être modifiées en cas d'évolution de la structure du marché.
L'extinction progressive des accords d'itinérance
Aujourd'hui, deux grands contrats de partage de réseaux mobiles existent en métropole.
Premièrement, un accord d'itinérance 2G/3G permet aux clients de Free Mobile d'accéder au réseau d'Orange, avec cependant une couverture et une qualité moindres que pour les clients d'Orange. Si cette prestation s'est justifiée pour accompagner l'entrée d'un quatrième opérateur de réseau mobile, elle ne saurait a priori être pérenne. En parallèle du déploiement du réseau de Free Mobile, la trajectoire d'extinction de l'itinérance devrait désormais être prévue. L'ARCEP envisage à ce stade que le processus d'extinction débute rapidement, sans attendre la fin du contrat existant. Pour les services haut débit (équivalent 3G), l'ARCEP estime que l'extinction devrait se terminer à une date évaluée à ce stade entre la fin 2018 et la fin 2020. Pour les services voix, SMS et bas débit (équivalent 2G), qui ont une importance moindre dans la dynamique d'investissement, l'extinction pourrait être effective à une date évaluée à ce stade entre le début 2020 et la fin 2022.
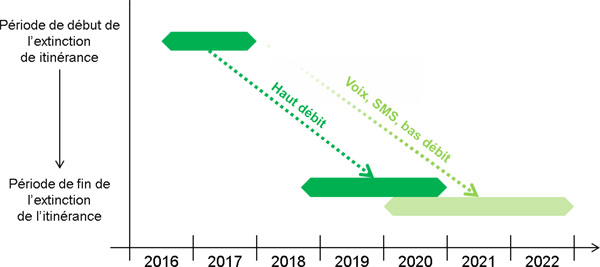
Trajectoire d'extinction de l'itinérance de Free Mobile, soumise à consultation publique
Trajectoire d'extinction de l'itinérance de Free Mobile, soumise à consultation publique
Deuxièmement, SFR et Bouygues Telecom ont établi un accord visant à mutualiser leurs réseaux 2G/3G/4G sur une large partie du territoire. L'ARCEP souhaite s'assurer que ce vaste accord permette bien, comme les deux opérateurs l'ont indiqué, d'améliorer la couverture et la qualité des services pour les utilisateurs. De plus, cet accord inclut une prestation d'itinérance 4G pour les clients de SFR sur une partie du réseau de Bouygues Telecom. Au regard de l'importance, pour la dynamique du marché, des investissements dans les infrastructures 4G, l'ARCEP appelle à fixer précisément la fin de l'itinérance très haut débit (équivalent 4G), à une date évaluée à ce stade entre fin 2016 et fin 2018.
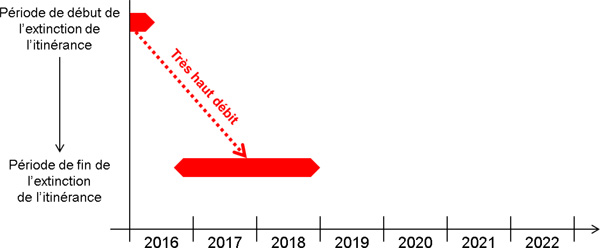
Trajectoire d'extinction de l'itinérance de SFR, soumise à consultation publique
Trajectoire d'extinction de l'itinérance de SFR, soumise à consultation publique
Au stade de la présente consultation publique, l'ARCEP laisse ouvertes les dates précises de fin qu'elle recommande pour les prestations d'itinérance. Elle appelle les acteurs intéressés à indiquer les dates qui leur semblent justifiées, a priori au sein des trois intervalles qu'elle a pré-identifiés.
After Hours Summary: ICLD +4.6%, ACST +4.4%, IRG +2.0%, PRGS +1.7%, TREE +1.6% following earnings/guidanceAfter Hours Gainers:
Companies trading higher in after hours in reaction to earnings/guidance: ICLD +4.6%, ACST +4.4%, IRG +2.0%, PRGS +1.7%, TREE +1.6%
Companies trading higher in after hours in reaction to news: BIOL +10.9% (entered into a development and distribution agreement with IPG Photonics Corporation's (IPGP) medical laser division), MET +7.1% (planned to pursue the separation such as public offering, spin-off, or sale of a substantial portion of its U.S. Retail segment), ARNA +5.1% (Co and Boehringer Ingelheim to conduct joint research to identify drug candidates targeting an undisclosed G protein-coupled receptor), ICLD 10.9% (CEO releases letter to shareholders; expects to see continued growth in 2016), YUM +3.4% (reported China December comps +1% YoY; sees Q4 China comps at +2%).
After Hours Losers:
Companies trading lower in after hours in reaction to earnings/guidance: F -3.9%, CSX -2.5%, WBMD -1.5%
Companies trading lower in after hours in reaction to news: KBIO -53.2% (will withdraw its appeal of the Nasdaq decision of to delist shares), FXCM -11.6% (reports December and Q4 metrics; Says ongoing sales process may not be completed in Q1 as previously indicated).
Closing Market Summary: Indices Rally Into CloseThe stock market ended its volatile Tuesday affair on a positive note, with the S&P 500 advancing 0.8%. The stock market fixated on oil prices today after mostly quiet overseas sessions. Despite the moderate advance, the rally remained muted for most of the day thanks to ongoing commodity concerns. The tech-heavy Nasdaq (+1.0%) outperformed the benchmark index and the Dow Jones Industrial Average (+0.7%).
Oil rested on its overnight low until reports of a terrorist attack in Turkey pushed the energy-component higher. WTI crude was able to mount a rally into the U.S. open, but was unable to maintain that momentum. Declines in oil were mirrored across equities for the most of the day as WTI crude ended its pit session lower by 3.1% at $30.44/bbl. However, the energy component climbed in electronic trade and the stock market rallied alongside.
On the leaderboard, technology (+1.2%), health care (+1.2%), consumer discretionary (+1.0%), and industrials (+0.7%) lead the pack. On the flipside, energy utilities (-0.5%), telecom services (-0.4%), materials (+0.2%), energy (+0.4%), and consumer staples (+0.5%) underperformed.
In the heavily-weighted technology sector, large-cap components saw relative strength with increased buying interest following the recent selloff. Cornerstones, Alphabet (GOOGL 745.34, +12.27), Facebook (FB 99.37, +1.86), and Apple (AAPL 99.96, +1.43) sported advances between 1.5% and 1.9%. Elsewhere in the space, the high-beta chipmakers ended in liine with the broader market, evidenced by the 0.8% gain in the PHLX Semiconductor index. Inside the index Intel (INTC 32.68, +0.62) outperformed with a gain of 1.9% thanks to resumed coverage at JPMorgan Chase with an 'Overweight' designation.
Looking at the consumer discretionary space, large-cap constituents there also showed relative strength with Starbucks (SBUX 59.46, +1.64) rising 2.8% after the company announced that it's on pace to have 2000 stores in China after looking to add 500 in 2016. Other influential sector members like Disney (DIS 101.46, +1.54) and Netflix (NFLX 116.58, +1.61) added 1.5% and 1.6%, respectively.
Switching to health care , the insurance sub-sector lead the space with Anthem Inc. (ANTM 135.60, +7.24), UnitedHealth Group (112.26, +2.68), and Aetna (AET 109.15, +4.08) outperforming with gains between 2.5% and 5.6%. Elsewhere in the group, biotechnology paced the advance evidenced by the 1.6% gain in the iShares Nasdaq Biotechnology ETF (IBB 296.21, +4.52).
Treasuries ended just below their highs with the 10-yr yield slipping seven basis points to 2.10%.
Trading volume remained heavy with more than a billion shares changing hands at the NYSE floor once again.
On the economic front, the November Job Openings and Labor Turnover Survey showed that job openings increased to 5.431 million from October's revised 5.349 million figure (from 5.383 million).
Tomorrow, the weekly MBA Mortgage Index will be released at 7:00 ET while the Federal Reserve's January Beige Book and the December Treasury Budget will cross the wires at 14:00 ET.
- Russell 2000 -8.1% YTD
- Nasdaq -6.4% YTD
- S&P 500 -5.2%
- Dow Jones Industrial Average -5.2%
Fox Exec Co-Chair Lachlan Murdoch reportedly reiterates that Fox remains uninterested in getting involved in a TWX bid - press