>>> VXX Reverse Split Number 4—August 9th, 2016

http://sixfigureinvesting.com/2013/08/next-vxx-reverse-split/

Barclays’ announced 26-July-16 that it was going to reverse split VXX and its sister, medium term fund VXZ on August 9th, 2016. Both funds will be reverse split 4:1. This is the first reverse split for VXZ since its inception in 2009, but it will be the fourth for VXX. For details on how options are handled with reverse splits (it’s not pretty) see the bottom of this post.
For a security doomed to decrease in value over time Barclays’ VXX does amazingly well. Its volume averages over 65 million shares per day and its assets under management have stayed around $1.0 to $1.5 billion for the last couple of years. Not bad for a product that has averaged a 58% annual loss since its inception in January 2009. This works out to an average loss of almost 7% per month. See “Volatility Fund Monthly and Year Decay Rates” for a chart showing how these losses have varied over time.
According to its prospectus, Barclays can reverse split VXX any time after it closes below $25 and that reverse splits will always be at a four to one ratio.
History of VXX Reverse Splits
Event Dates Split Ratio Inception / close price right before reverse split (split adjusted) Months since inception /last split
Inception 30-Jan-2009 100 (6,400)
1st Rev. Split 8-Nov-2010 4:1 13.11 21
2nd Rev. Split 4-Oct-2012 4:1 8.77 23
3rd Rev. Split 8-Nov-2013 4:1 12.84 13
4th Rev. Split 8-Aug-2016 4:1 9.27 34

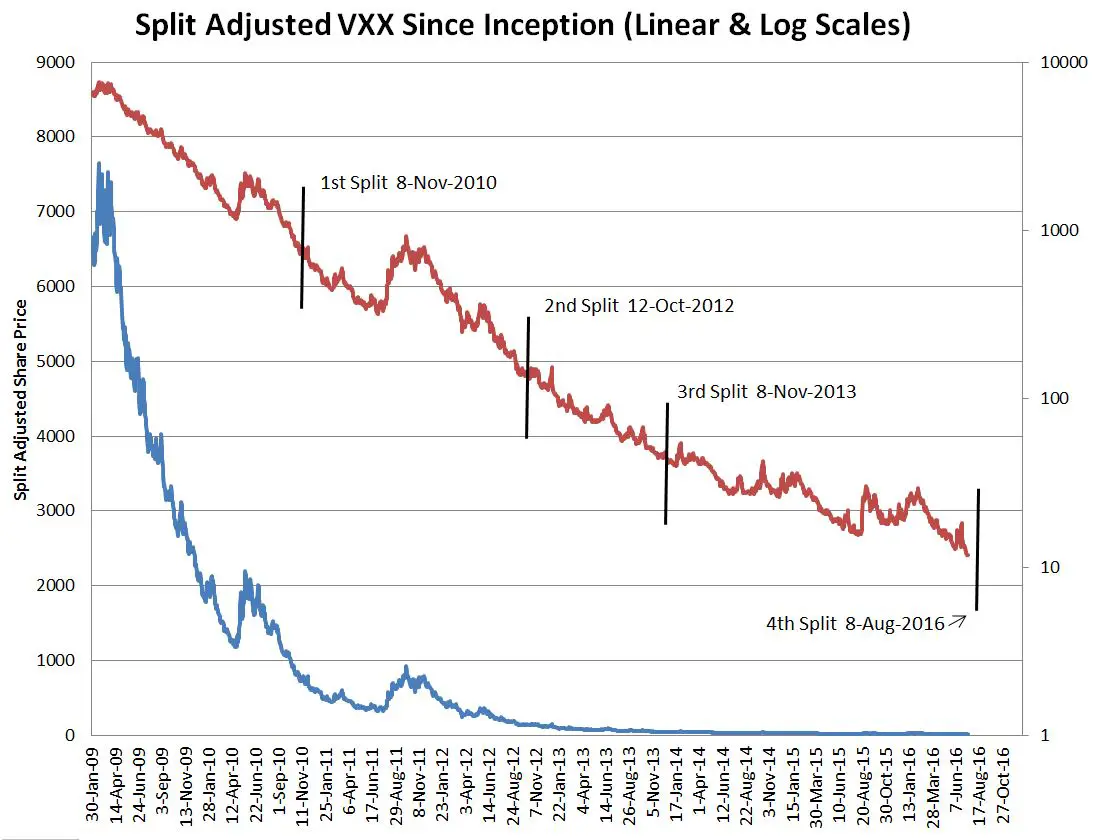
The first and second splits of VXX occurred after about 22 months, but 2012 did not have volatility bumps like 2010 and 2011, so the 3rdreverse split was only 13 months after the 2nd one. Volatility has kicked up quite a bit since 2014 so it took a record 34 months before Barclays reverse split this product again. The approximate decay per month has slowed down to “only” around 3.5% per month (35% per year).
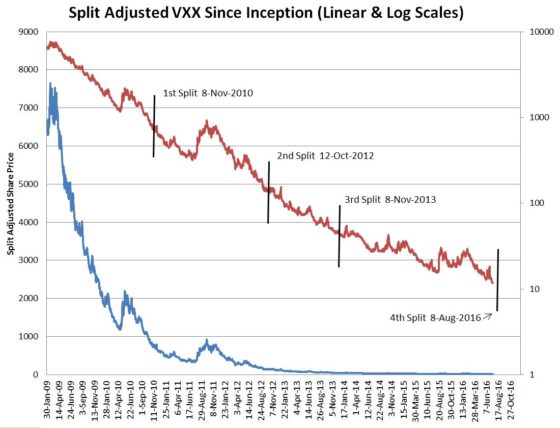
The chart below, with both log and linear scales, shows VXX’s sordid split adjusted price history.
Given its horrid track record, it’s fair to ask why people keep investing in VXX. Some are just trying to profit from volatility spikes, hoping to catch the next big crash that somebody is always predicting to happen soon. Others are trying to hedge their equity holdings with VXX because it is one of the few securities that reliably goes up when the market is panicking. Unfortunately, this strategy rarely works well. Unless your timing is very good owning enough VXX to effectively hedge your portfolio is prohibitively expensive.
Specifics of the Split
If you hold shares of VXX there isn’t anything to worry about when it reverse splits. The value of your investment stays the same through the reverse split process. You just have 4X fewer shares that are worth 4X more each (assuming a reverse split ratio of 4:1). If your shareholdings are not a multiple of four, say 215 shares, you will get 53 reverse adjusted shares and a cash payout for the 3 remaining pre-split shares.
If you are short VXX, same story, no material impact.
If you were holding VXX options (long or short) when the reverse split occurred there’s still no material impact, however, the option chains are going to hurt your head for a while. This Options Clearing Corporationmemo describes the adjustments for the August 2016 reverse split. It adjusts the number of VXX shares per option on the pre-split contract from the usual 100 to 25. The option strikes are not adjusted and the underlying symbol that the options trade against is VXX1, a new symbol—which is set at 25% of VXX’s price. These contortions are required so that holders aren’t left with fractional contracts–something the options clearing house doesn’t want to deal with.
So, as an example, let’s say you hold ten pre-split options on VXX with an expiration date of August 19th and a strike price of $10. Each contract was worth around 0.19 ($19) at the close on August 8th (VXX’s closing price was 9.30) so your overall position value is around $190. After the reverse split your contracts are adjusted so each contract has 25 shares of the new reverse split VXX as its deliverable. The strike price, $10 stays the same, and the effective price of the underlying that the option is priced against is the current VXX value divided by 4. So, if on August 9th, right after the reverse split VXX’s price is $37.2 and VXX1’s price is 9.3. Your options will continue to be worth about $19 each, and you still own 10 contracts so your position is still worth around $190. The only difference is that if you exercise all your contracts you won’t get 1000 shares of VXX, you’ll get 250 shares.
New options created after the split will be generated with VXX as the underlying, but the old adjusted options will hang around until they expire. I’ve seen reports that the liquidity on the adjusted options is not good, so if you are planning on exiting your options, rather than just letting them expire you should consider closing out your positions and reestablishing them after the split.
For regular, forward splits things are more straightforward —the strike price of the options are divided by the split ratio, and the number of contracts is multiplied by the split ratio. See the OCC memo on SVXY’s 1:2 split for an example. This basic approach can’t be used on reverse splits (multiply the strike price and divide the number of contacts by the split ratio) because depending on the number of contracts held some customers would end up with fractional contracts—which is a no go.
The chart below uses my simulated data plus actuals to show VXX’s price history since 2004

WSJ : Are Negative Rates Backfiring? Here’s Some Early Evidence

Are Negative Rates Backfiring? Here’s Some Early Evidence

Economists worry that people and businesses are saving more, instead of spending

KORSCHENBROICH, Germany—Two years ago, the European Central Bank cut interest rates below zero to encourage people such as Heike Hofmann, who sells fruits and vegetables in this small city, to spend more.

Policy makers in Europe and Japan have turned to negative rates for the same reason—to stimulate their lackluster economies. Yet the results have left some economists scratching their heads. Instead of opening their wallets, many consumers and businesses are squirreling away more money.

When Ms. Hofmann heard the ECB was knocking rates below zero in June 2014, she considered it “madness” and promptly cut her spending, set aside more money and bought gold. “I now need to save more than before to have enough to retire,” says Ms. Hofmann, 54 years old.

Recent economic data show consumers are saving more in Germany and Japan, and in Denmark, Switzerland and Sweden, three non-eurozone countries with negative rates, savings are at their highest since 1995, the year the Organization for Economic Cooperation and Development started collecting data on those countries. Companies in Europe, the Middle East, Africa and Japan also are holding on to more cash.

Economists point to a variety of other possible factors confounding central-bank policy: Low inflation has left consumers with more money to sock away; aging populations are naturally more inclined to save; central banks themselves may have failed to properly explain their actions.


But there is a growing suspicion that part of problem may be negative rates themselves. Some economists and bankers contend that negative rates communicate fear over the growth outlook and the central bank’s ability to manage it.

“People only borrow and spend more when they are confident about the future,” says Andrew Sheets, chief cross-asset strategist at Morgan Stanley. “But by going negative, into uncharted territory, the policy actually undermines confidence.”

Going negative was a big bet by central banks faced with a sluggish recovery from the financial crisis. Whether negative rates succeed or flop has huge implications for the global economy. Japan and Europe are already doing large volumes of bond buying to spur their economies, and their central bankers have little left in their tool kits.

The U.S. Federal Reserve’s next move is likely to raise rates, but Chairwoman Janet Yellen has said negative rates could find a place in the Fed’s armory in any future crisis.

The Bank of England, shaken by June’s surprise vote to leave the European Union, cut interest rates to their lowest in its 322-year history last week but said it was reluctant to go negative. BOE Gov. Mark Carney said he is “not a fan” of a policy that has negative consequences for savers and the financial system. European banks say their profitability has been hit hard by low rates.

Negative Interest Rates: How Do They Work?
0:00 / 0:00
Central banks across the globe are trying a radical approach to boost economic growth: negative interest rates. But what are negative rates and will they work? Image: Adele Morgan/The Wall Street Journal (Originally published April 14, 2016)
Some central bankers say it is too early to judge negative rates. “The effect won’t be seen all at once, but it will gradually become clear,” said Bank of Japan Gov. Haruhiko Kuroda in a June news conference.

Benoît Coeuré, a member of the ECB’s executive board, in a July speech, said measures including negative interest rates, “are proving to be effective in lifting inflation toward its medium-term objective and reducing the overall level of risk in the economy.”

Low interest rates should encourage consumers and businesses to spend by depressing returns on savings and safe assets such as government bonds. Such spending should create demand for goods, help lift sagging inflation and boost economic growth.

Negative rates aren’t fundamentally different, in their day-to-day effects, for most people. Negative rates mean large commercial banks have to pay to park their money at central banks, which encourages them to lend it out instead. Banks spread those costs in various ways. For the individual or most corporate customers, the effect is to push interest rates paid on deposits, while still positive, even closer to zero.

Negative rates aren’t just aimed at spurring spending. Europe and Japan need weaker currencies to help exports and boost low inflation, and negative rates can help bring that about.

Some economists now believe negative rates can have an unintended psychological effect by communicating fear over the growth outlook and the central bank’s ability to manage it.

“The signal to the consumer is that something is wrong—it’s a crisis measure,” says Carl Hammer, chief currency strategist at Swedish bank SEB.

Lasse Bohman, a 63-year old newsstand worker from Stockholm, said the concept of negative interest rates is “weird” and makes him want to save more for retirement rather than spend. “I am just going to keep on putting money in the bank,” he says, or “put it under the mattress at home.”

In Germany, Europe’s largest economy and a nation known for thrift, savings as a percentage of disposable household income rose to 9.7% in 2015, according to preliminary data from the OECD. That is the highest rate since 2010, and the OECD expects the savings rate to rise further this year, to 10.4%.

Many Germans worry that negative rates pose a threat to their rainy-day funds. Four in 10 Germans cite the ECB’s monetary policy and low interest rates as their biggest concern when it comes to savings, according to a survey by the German Savings Banks Association last October.

In December, Ms. Hofmann, the Korschenbroich fruit vendor, used her Christmas bonus to buy two 10-gram bars of gold. She has since bought more and has put it, and every euro she can set aside, into a safe at home, saying she doesn’t trust banks. “Every time I check my savings account, it makes me want to cry,” she says.

In the broader eurozone, where saving isn’t as ingrained in the psyche as in Germany, the household savings rate has edged lower since negative interest rates were introduced in 2014.

The OECD forecasts the household-saving rate will increase this year in Japan, which introduced negative rates in February. Cash and deposits held by Japanese households were up 1.3% in the first quarter from the same period a year ago, according to the Bank of Japan.

In the U.S. and U.K., where interest rates are still positive but annualized growth rates in the year’s first quarter were slower than the eurozone or Japan, savings rates have been stable or trending lower.

Companies also are also holding on to funds, and some are forgoing cheap loans.

In Japan, cash and deposits held by nonfinancial corporations increased 8.4% in the first quarter from a year earlier, according to the Bank of Japan. That growth was the biggest since the 1990s.

Nonfinancial corporations in Europe, the Middle East and Africa had €921 billion in cash balances as of December 2015, according to a report from Moody’s Investors Service on the companies it rates, up about 5% from a year earlier. As a percentage of revenues, cash balances were 15% last year, versus 13% in 2014.

“This odd policy of negative interest rates hasn’t motivated us to invest more. On the contrary, it’s a signal that the economic situation isn’t improving,” says Hans-Gerd Wienands, chief financial officer of Messer Group, a German supplier of industrial gases.

The company has cut the amount it invests to 12.5% of revenue this year, from more than 20% in 2010, as it reduced debt.

In Japan, Tatsuro Takahashi, who sells barbecue pork from his food truck in Tokyo, said, “I’m not interested in borrowing money to expand my business, whether the rate is lower or not. It is riskier.”

Bank lending in Japan has expanded for 58 months in a row through July, but growth has slowed.

The Bank of Japan “failed to foresee people’s behavior,” said Noriko Hama, a professor of economics at Doshisha University in Kyoto, in the magazine Weekly Economist. “It’s simply rational for them to increase savings.”

Household spending in Japan jumped 1.2% in February, the month the BOJ introduced negative rates, but fell the following four months.

Some say other factors are contributing to increased savings. In Germany, for instance, low inflation stemming from cheaper oil and tepid growth means that people have more money to put away simply because the stuff they buy costs less.

ECB President Mario Draghi says that after accounting for inflation, the rate that savers earn today is higher than it was on average in the 1990s.

Peter Praet, the ECB’s chief economist, says the focus should also be on borrowers, who are more inclined to spend than savers, and are seeing a boost to their disposable income because ultralow rates reduce the cost of servicing debt.

Other central-bank executives concede negative rates may push some to save. Yves Mersch, a member of the ECB’s executive board, said in June that it is possible “households are hoarding even more” because they need to save more to build up the same amount of wealth over the same time span.

Household spending as percentage of gross domestic product has fallen slightly in Germany to 54% last year, from 55.4% in 2013, according to OECD data. It also has fallen in Sweden, and is relatively flat in Denmark and Switzerland.

Interest payments on savings accounts in the eurozone are at the lowest levels since 2000, according to ECB data. In the early 1990s, it took nine years for a German saver to double his or her capital as interest income piled up, according to Hans Joachim Reinke, chief executive of Frankfurt-based Union Investment. Now, savers like Ms. Hofmann would have to wait 500 years for that to happen.

Negative rates have also hit pension payouts, giving older savers another reason to squirrel away more cash.

Pension funds and pensioners typically invest in government bonds in a quest for reliable income. That income has never been smaller. About $12 trillion worth of bonds currently have negative yields, according to Bank of America Merrill Lynch European credit-strategy research, compared with almost none two years ago.

That is a problem for Henrik Olejasz Larsen, who as chief investment officer of Sampension manages pensions for Danish government employees. The return on assets that Sampension invests in has fallen as low as 0.2%, far from the 3.5% needed to maintain pension payouts at a level expected by their holders.

University of Michigan economist Miles Kimball believes rates should be lowered even deeper into negative territory. If people are getting scared by negative rates, he says, it is the fault of central banks’ inability to communicate effectively, not the policy itself.

“They should say that this is a normal tool of policy,” he says, “and then people wouldn’t freak out.”

>>> Asian Update

Asian Mid-session Market Update: China CPI decelerates for 3rd straight month; AUD falls as NAB forecasts more aggressive RBA easing

***Economic Data***
- (CN) CHINA JULY CPI Y/Y: 1.8% V 1.8%E; 6-month low
- (CN) CHINA JULY PPI Y/Y: -1.7% V -2.0%E (53nd consecutive month of decline)
- (JP) JAPAN JULY M2 MONEY STOCK Y/Y: 3.3% V 3.3%E; M3 MONEY STOCK Y/Y: 2.9% V 2.9%E
- (AU) AUSTRALIA JULY NAB BUSINESS CONFIDENCE: 4 V 5 PRIOR; CONDITIONS: 8 V 11 PRIOR
- (AU) Australia ANZ Roy Morgan Weekly Consumer Confidence Index: 114.7 v 118.0 prior
- (NZ) NEW ZEALAND JULY CARD SPENDING M/M: 0.3% V 0.1%E; TOTAL M/M: 0.4% V +1.0% PRIOR
- (NZ) New Zealand ANZ July non-tradable inflation m/m: -0.3%; first decline since May 2015
- (NZ) New Zealand July ANZ Truckometer Heavy M/M: -5.7% v +4.7% prior
- (UK) JULY BRC LFL SALES Y/Y: +1.1% V -0.7% PRIOR; 6-month high

***Index Snapshot (as of 04:30 GMT)***
- Nikkei225 +0.4%, S&P/ASX +0.2%, Kospi +0.6%, Shanghai Composite +0.3%, Hang Seng -0.2%, Sep S&P500 flat at 2,176

***Commodities/Fixed Income***
- Dec gold -0.1% at $1,340/oz, Sep crude oil -0.9% at $42.66/brl, Sep copper -0.1% at $2.16/lb
- GLD: SPDR Gold Trust ETF daily holdings rise 6.5 tonnes to 973.8 tonnes; first decline since Aug 3rd
- SLV: iShares Silver Trust ETF daily holdings rise to 10,941 tonnes from 10,911 tonnes prior; multi-year high
- JGB: (JP) Japan's MOF sells ¥725B in 0.3% 30-year bonds; Avg yield: 0.424% v 0.120% prior; Bid to cover: 3.07x v 2.64x prior
- USD/CNY: (CN) PBOC SETS YUAN MID POINT AT 6.6594 V 6.6615 PRIOR
- (CN) PBOC to inject CNY70B in 7-day reverse repos
- (AU) Australia MoF (AOFM) sells A$150M in 2.5% 2030 Indexed Bonds; avg yield: 0.3921%; bid-to-cover: 2.63x

***Market Focal Points/FX***
- Asian equity markets are gaining modestly despite incremental declines on Wall St as expectations of policy accommodation in the region continue to run high. China consumer inflation has met consensus estimates but slowed for the 3rd straight month to 1.8%, remaining well below the 3% target. Likewise, Australia ANZ business confidence slipped further, while New Zealand ANZ inflation and forward-looking heavy trucking sentiment reversed course into the red in July. S&P futures are flat, oil is consolidating US session gains, and FX majors traded with a dollar-positive bias. AUD/USD fell about 40pips toward 0.7620, NZD/USD was down 30pips below 0.7130, and USD/JPY briefly rose about 25pips from the lows above 102.50. GBP/USD tested below 1.30 level for the first time in nearly a month on comments from a BOE hawk McCafferty who acknowledged that further easing is likely to be necessary as it was difficult to forecast the headwinds from the Brexit vote on the economy.

- China CPI hit a 6-month low, but m/m saw a rise of +0.2% v -0.1% prior. Food price inflation slowed to 3.3% v 4.6% prior, while that of non-food goods rose to 1.4% v 1.2% prior. Economists have also continued to digest overnight release of July trade data that showed higher than expected surplus but bigger than expected declines in both exports and imports. ANZ said outbound shipments will remain lackluster "as sluggish growth in Europe and Japan is likely to drag on Chinas exports... Brexit will weigh further on exports to the EU, as the EU and Japan together make up over a fifth of Chinas total exports."

- NAB July business retreated further in July, prompting its economists to revise its RBA forecasts to anticipate more easing. Namely, NAB now sees two additional RBA rate cuts next year to 1.00% rate along with the possibility of "unconventional monetary policy". NAB cited expectation of CPI remaining below target for extended period and structural transition away from mining in the economy weighing on labor in the long run. NAB sees RBA easing again in May and Aug of 2017 to help stabilize the unemployment rate (which is currently a concern for the RBA) at just over 5%.

- Ahead of this week's RBNZ decision, swaps markets have boosted expectations of a more aggressive 50bp cut to 15% from 10%, while ANZ chief economist said NZ banks are unlikely to pass on a full rate cut given the rise in funding costs and slower deposit growth.

***Equities***
US equities / ADRs:
- MCHP: Reports Q2 $0.84 v $0.75e, R$844.0M (adj) v $821Me; raises dividend 0.1% from $0.3595 to $0.36 (implied 2.5% yield); +4.5% afterhours
- NUAN: Reports Q3 $0.38 v $0.37e, R$485M v $490Me; -1 .0% afterhours
- GPS: Reports July SSS -4% v -0.3%e; Guides Q2 $0.58-0.59 (ex $0.28 in store closure and streamlining costs) v $0.47e, R$3.85B v $3.75Be; -5.1% afterhours
- MTW: Reports Q2 $0.04 v $0.03e, R$457.7M v $468Me: -11.9% afterhours
- MXL: Reports Q2 $0.50 v $0.44e, R$102M v $102Me; -15.5% afterhours

Asia Notables by sector:
- Consumer discretionary: Skyworth Digital 751.HK +1.6% (July result); Cochlear COH.AU -1.7% (FY16 result); Mobile Embrace MBE.AU -8.1% (guidance)
- Consumer staples: Cosmax 192820.KR +1.0% (Q2 result)
- Financials: ANZ Bank ANZ.AU +2.8% (9-month result); IOOF Holdings IFL.AU -6.9% (FY16 result)
- Industrials: Great Wall Motor 2333.HK +2.4% (July result); Brother Industries 6448.JP +16.8% (Q1 result); Japan Steel Works 5631.JP +9.7% (Q1 result)
- Technology: Mesoblast MSB.AU +7.9% (phase 2 results show improvements)
- Materials: Aluminum Corporation of China 2600.HK -0.7% (acquisition); Mitsubishi Materials 5711.JP -5.3% (Q1 result)
- Utilities: Transurban TCL.AU -0.5% (FY16 result)

>>> After Hours Summary: SINA +5%, MCHP +4.4% higher following earn


After Hours Summary: SINA +5%, MCHP +4.4% higher following earnings, CPS +1% on S&P SmallCap 600 addition news... TUBE -22%, MTW -12.8%, GPS -5.2% on earnings/guidance/SSS

After Hours Gainers:

Companies trading higher in after hours in reaction to earnings/guidance: HIIQ +31%, REN +19.8%, FH +14.3% (also FORM Holdings to acquire 100% of XpresSpa through a private placement of its common stock to Mistral Equity Parterns and other existing XpresSpa holders at $2.31/share or $1.73 mln), AMPH +9.4%, CSLT +8.8%, NVRO +8.7%, ENDP +7.2%, GIGA +6.5% (also receives a $1.9 mln order for non-recurring engineering services associated with its Microsource business unit from an aerospace company), OPK +5.4%, MIME +5%, SINA +4.9%, ZLTQ +4.8%, CPE +4.7%, MCHP +4.4%, (also increased quarterly cash dividend to $0.36/share from $0.3595/share), ARNA +4.2%, IDI +4.1%, (also annouces Harry Jordan as COO), NILE +3.8%, VSLR +3.4%, FGEN +3.2%, VTTI +3.2%, (also VTTI Energy Partners to acquire an additional 8.4% equity interest in VTTI MLP B.V. and associated pro-rata net debt from VTTI MLP Partners B.V. for cash consideration of $96.2 mln; commences 5.25 mln public offering of common units representing limited partner interests in the Partnership ), AMID +3.1%, IPHI +2.3%

Companies trading higher in after hours in reaction to news: WPZ +4.7% (Williams and Williams Partners announced they have agreed to sell the companies' Canadian businesses to Inter Pipeline Ltd. for combined cash proceeds of $1.35 billion CAD), CPS +1.2% (S&P announces Cooper-Standard Holdings will replace QLogic Corp.  in the S&P SmallCap 600 after the close of trading on Wednesday August 10)

After Hours Losers:

Companies trading lower in after hours in reaction to earnings/guidance: DRYS -31.1%, CNXR -23.2%, TUBE -22.2%, MODN -16.4%, NPTN -15.6%, MXL -14.6%, MTW -12.8%, ROG -9.3%, GPS -5.2% (Gap reports July same store sales -4.0% vs -3.6% Retail Metrics consensus and issues Q2 guidance), RRGB -5.2% (also announces that Denny Marie Post has been appointed as CEO and to the board, effective August 8 2016 ), RRGB -5.2%, BOJA -4.8%, ELNK -4.5%, JPEP -3.1%, DVA -2.9%, MNKD -2%, RAX -1.8% (also sells its Cloud Sites business unit to Liquid Web; terms not disclosed), LC -1.7% (also CFO Dolan stepping down), HTZ -1.7%, TWLO -1.4%, KITE -1.3%, NUAN -1%

Companies trading lower in after hours in reaction to news: TWER -13.9% ( files for $20 mln common stock offering ), FCSC -12.4% ( to offer and sell shares of its common stock and related warrants to purchase shares of its common stock in an underwritten public offering), IAG -8.5% (IAMGOLD to sell, on a bought deal basis, 38.85 mln common shares at a price of $5.15/share, for aggregate gross proceeds of ~$200 mln; commences cash tender offer for up to $150 million of its 6.75% Senior Notes due 2020), ACAD -4.6% ( to offer and sell $200 mln of its common stock in an underwritten public offering ), X -4.2% ( commences 17 mln common stock offering), TSE -3.9% (Trinseo announces that Bain Capital Everest Manager Holding has agreed to sell 8 mln ordinary shares pursuant to its shelf registration statement), BMRN -2.9% (files mixed securities shelf offering; commences 7.5 mln common stock offering), WING -2.8% (announces that a stockholder, namely an affiliate of Roark Capital, intends to offer for sale in an underwritten secondary offering 6 mln shares of the co's common stock ), PSXP -2% ( announces an underwritten public offering of 6 mln common units ), SAVE -0.8% (reports July prelim traffic; RPMs +18.4% Y/Y on ASMs +17.1% Y/Y, load factor for July 2016 was 89.8%, +1%), D -0.3% (to offer to sell 25 million equity units, subject to market and other conditions), ALDX -0.2% (will report the results of a clinical trial of NS2 in patients with Sjögren-Larsson Syndrome on August 9, 2016, prior to the market open)

>>> US Close Dow -0.08% S&P -0.09% Nasdaq -0.15% Russell -0.07%


Closing Market Summary: Stocks Finish Flat as Oil Rallies

The stock market began the week on a quiet note as the Nasdaq Composite (-0.2%) settled behind the S&P 500 (-0.1%) and the Dow Jones Industrial Average (-0.1%). The benchmark index meandered in an eight-point trading range as a rally in crude oil helped counter weakness from the heavyweight consumer discretionary (-0.3%) and health care (-0.9%) sectors.

U.S. equities began the day on a modestly higher note, responding to a positive bias in global bourses. Asia-Pacific indices outperformed as participants reacted to Friday's above-consensus reading of the U.S. Employment Situation Report for July. The employment data showed continued improvement to the hiring landscape as nonfarm payrolls (255K; consensus 185K) handily beat estimates for the second consecutive month. Conversely, there was no negative response to China's disappointing Trade Balance Report after the People's Bank of China suggested potential "innovative" stimulus measures.

The major averages pulled back through the opening hour as the heavyweight technology (UNCH), consumer discretionary (-0.3%), and health care (-0.9%) sectors weighed on the broader market. The move to the downside was limited though, as investors eyed a rebound in crude oil. WTI crude rallied 3.0% ($43.07/bbl; +$1.24) amid reports that several members of OPEC are attempting to revitalize a production freeze agreement. The energy component extended its August gain to 3.6%.

The benchmark index carved out a session low in the afternoon (2177.85), but recovered in the final hour to end just below its flat line. Seven sectors ended in the red with heavily-weighted industrials (UNCH) and technology (UNCH) showing the slimmest losses. On the flipside, financials (+0.1%), materials (+0.2%), and energy (+1.2%) outperformed.

The countercyclical health care sector (-0.9%) ended at the bottom of the leaderboard as pharmaceutical names weighed. In the group, Bristol-Myers (BMY 60.30, -2.98) extended its two-session losing streak to 19.9%. The company came under pressure last Friday after announcing that its Opdivo medication failed to meet its primary endpoints. Biotechnology also underperformed after Allergan (AGN 248.31, -5.54) reported mixed quarterly results and updated its outlook to reflect the sale of the Actavis Generics division to Teva Pharmaceuticals (TEVA 53.30, -0.91).

Influential Netflix (NFLX 95.11, -1.92) weighed on the consumer discretionary space (-0.3%) after reports indicated that Alibaba (BABA 85.00, +0.41) is not seeking to invest in the company. Separately, Chinese streaming service Leeco announced that it is looking to add additional U.S. employees. Amazon (AMZN 766.56, +0.58) finished flat after Wal-Mart (WMT 73.34, -0.42) agreed to purchase Amazon competitor Jet.com. Wal-Mart agreed to pay $3 billion in cash for the company. Elsewhere, on the M&A front, Mattress Firm (MFRM 63.75, +34.01) spiked after Steinhoff offered to acquire the company for $64 per share. 

The PHLX Semiconductor Index (-0.2%) ended behind the broader technology sector (UNCH) as Qorvo (QRVO 54.30, -0.75) continued to underperform. The name has been under pressure after reporting its quarterly results on August 2. Separately, ON Semiconductor (ON 10.11, +0.12) ended higher by 1.2% after beating analysts' estimates for the quarter and offering in-line guidance for the third quarter.

The U.S. Dollar Index (96.39, +0.19) settled modestly higher as the greenback gained ground against the pound and yen. Sterling lost 0.2% against the buck (1.3042) while the dollar/yen pair ended the day higher by 0.6% (102.44). Elsewhere, the dollar lost 0.1% against the commodity-sensitive Canadian dollar (1.3165).

Treasuries ended a quiet session on a flat note as the yield on the benchmark 10-yr note finished flat at 1.59%.

Participation was below the recent average as fewer than 772 million shares changed hands on the NYSE floor.

There was no economic data of note released today. 

Tomorrow's economic data will include the preliminary estimate of second quarter Productivity (consensus 0.5%) and Unit Labor Costs (consensus 1.7%), which will cross the wires at 8:30 ET. Separately, Wholesale Inventories for June (consensus +0.2%) will be released at 10:00 ET. 

  • Russell 2000 +8.3% YTD
  • S&P 500 +6.7% YTD
  • Dow Jones +6.3% YTD
  • Nasdaq Composite +4.1% YTD 

>>> Intercontinental Hotels Group target raised to $48 at MKM Partners (42.60 +

Intercontinental Hotels Group target raised to $48 at MKM Partners

MKM Partners raises their IHG tgt to $48 from $45 noting co reported adj. EBIT ~4% ahead of consensus and EPS ahead of expectations driven by RevPAR acceleration in 2Q from 1Q and cost phasing to 2H. Firm believes this quarter highlights why they favor co's high-quality, less cyclical fee business: (1) Nearly 90% of fee income is based on hotel revs and 95% of operating profit is from its recurring fee business and (2) its transition to asset-light has structurally higher ROIC (deserves a higher multiple, in their view) that they calculated has increased from 10% in 2003 to 47% in 1H16. Firm believes IHG is a good candidate to participate in further industry consolidation.