Shares, Corporate Bonds Seen Decoupling After Rise
By Sagarika Jaisinghani and Tasos Vossos, Bloomberg Markets Live commentators and reporters
Resilient earnings and bets of peaking inflation have helped stocks and corporate bonds rally alike over the past couple of months, but with recession fears still lurking, the two asset classes could soon start taking different paths.
European stocks have gained about 9% since a low in early July, while corporate bonds are up 4.4% since bottoming in mid-June.
With Federal Reserve officials indicating they’ll keep monetary policy tight until they’re sure that inflation won’t flare up again, even at the cost of some economic pain, debt from safer firms may benefit from a potential flight-to-safety. But for stocks, it’s a risk to earnings that many investors may be unwilling to bear.

“What we’ve seen at this juncture is a bear market rally and we don’t want to chase it,” says Wei Li, global chief investment strategist at BlackRock, speaking of the rebound in equities. “I don’t think we’re out of the woods with one month of inflation cooling. Bets of a dovish Fed pivot are premature and earnings don’t reflect the real risk of a US recession next year.”
The second-quarter earnings season did much to restore faith in the health of Europe Inc. as companies largely proved demand was robust enough for them to pass on higher costs to consumers. But economists forecast a slowdown in business activity from here on, while Citigroup strategist Beata Manthey says she expects regional earnings to fall 2% this year and 5% in 2023.

And while investors in Bank of America’s latest global fund manager survey have turned less pessimistic about global growth, sentiment is still bearish. European stock funds saw outflows of $2.2 billion in the week to Aug. 17 -- a 27th straight week of redemptions, according to a BofA note that cited EPFR Global data.
Strategists now expect the Stoxx 600 to end the year at 447 points -- about 2% above current levels, according to the average of 15 estimates in Bloomberg’s monthly survey. BofA’s European strategists remain negative on the region’s equities as well as cyclicals versus defensives.

In the bond world, the layers that make up a company’s borrowing costs look set to play into investors’ hands. Corporate yields comprise the rate paid on similar government debt and a premium to compensate for threats like a borrower going bust.
When the economy falters, these building blocks tend to move in opposite directions. While a recession will raise concerns about firms’ ability to repay their debt and widen the spread over safe bonds, the flight-to-quality in such a scenario will cushion the blow.
To be sure, the summer rebound has made entry points in corporate bonds somewhat less appealing. George Bory, head of fixed income strategy at Allspring Global Investments, has turned more cautious on bond valuations, but remains bullish on them overall. “The world was becoming more bond friendly place and that should continue in the second half of the year,” he says.
Nasdaq Tanks As "Gamma Unclench" Arrives - Here Are The Levels To Sell (Or Buy)
US equity markets are under pressure this morning with Nasdaq leading the charge lower (having been dumped at the Asia open, the European open, and the US open)...
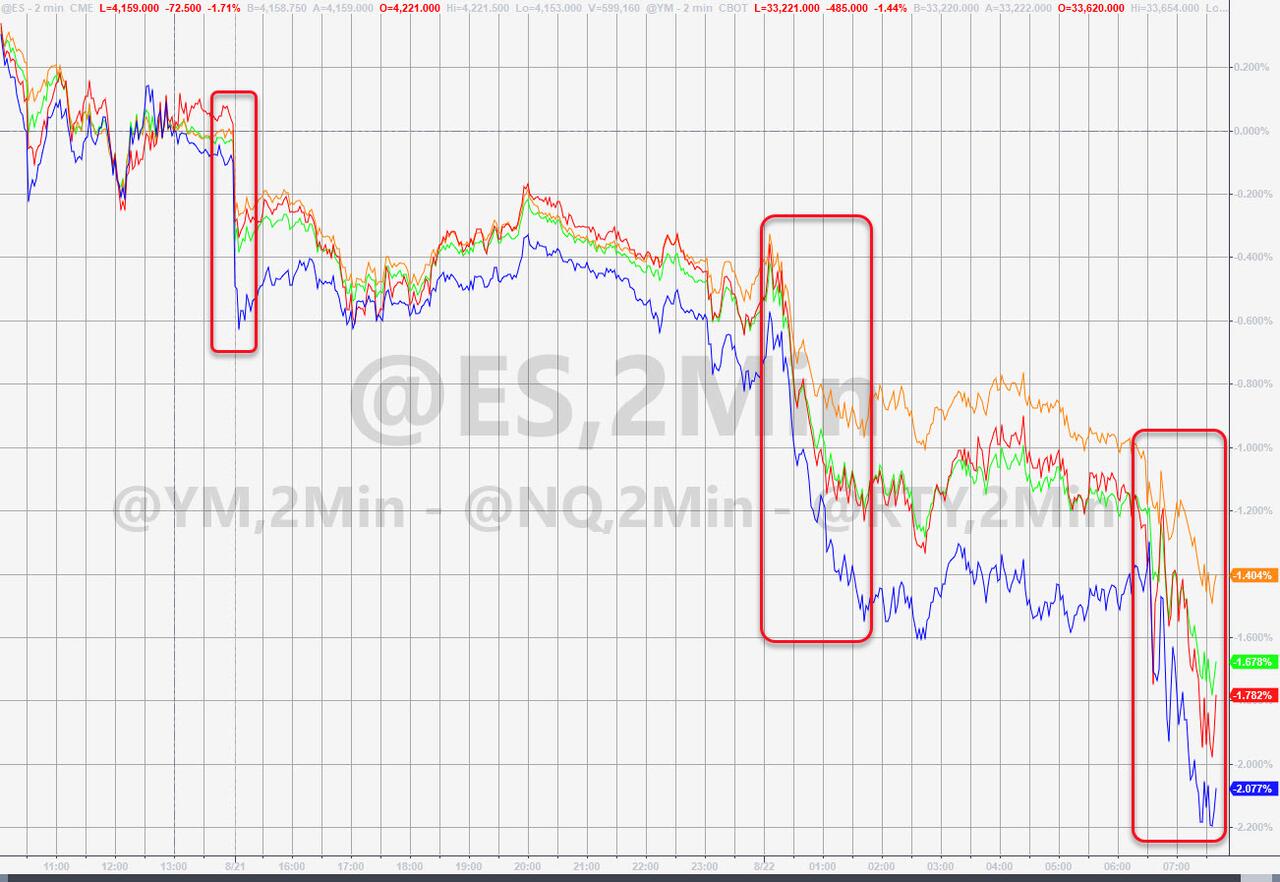
The Dow, S&P, and Russell 2000 all reversed at their 200DMAs and look set to test the 100DMA (Nasdaq never made it back to its 200DMA)...

As Nomura's Charlie McElligott notes, one major reason for this sudden volatility is the anticipated post Op-Ex “Gamma Unchlench” arrives and is allowing US Equities a larger trading distribution, with several key technical levels in play(or broken):
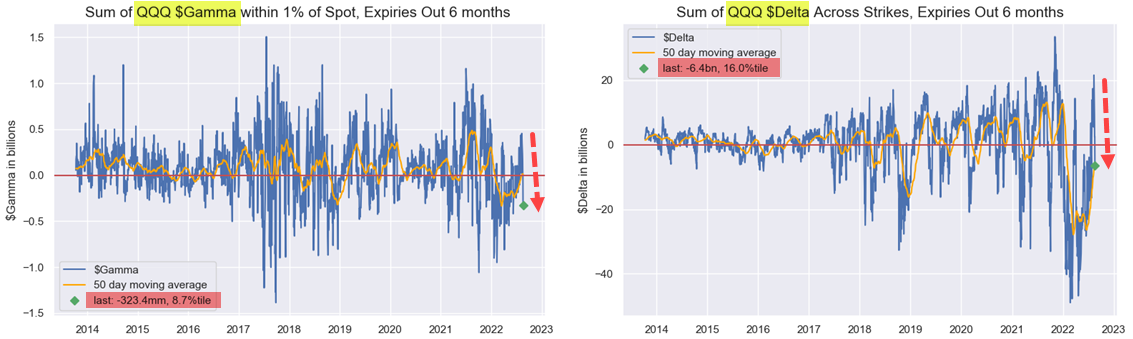
- Most critically after Friday’s heavy expiration activity, we now see Dealers in “Negative Gamma vs Spot” location below 4219 flip-line for SPX / SPY consolidated options (Note: QQQ, IWM and HYG all now in “Negative Gamma vs Spot” territory as well)
- ES1 through the 4215 “50% high / low” retrace
- Through 4202 sees a break below the bottom of the mid-July bull channel
Nasdaq stands out as the most obvious pivot back into "negative gamma" territory, with the ensuing 'delta purge'...
So what happens next?
As McElligott notes, from a “flows” perspective on the now two month Equities rally, we have focused on:
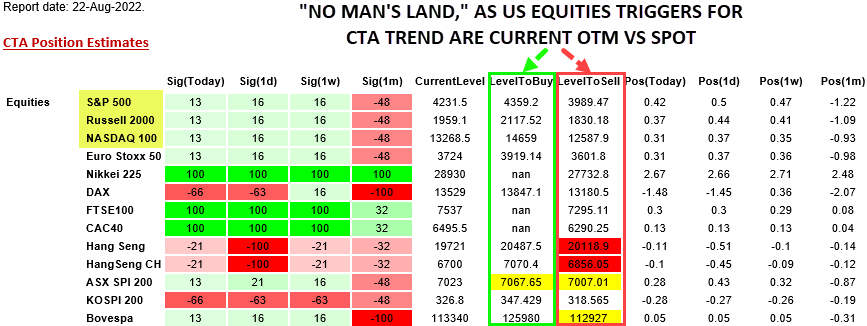
- 1) Systematic strategy buying-to-cover from CTA Trend (+$78.6B of Global Equities buying off the June net exposure low / peak of aggregated “Short” positioning);
- ...as well as 2) Vol Control re-allocation to add back exposure (+$35B off the May exposure lows), which only then accelerated the destruction of downside hedges AND forced grabbing into upside...
- ...hence 3) massive Mechanical “Positive $Delta” flows from the Options space, which at one-point were > +$900B of implied $Delta off the June low
NOW, however, we see those Systematic and Mechanical “buy” flows either largely spent, or at risk of actually becoming supply a few weeks out, IF Vol was to reset higher here for a sustained period of time
1. CTA Trend now sits in “no man’s land."Well-below releveraging buy-triggers overhead in US Equities futures... butAbove de-leveraging / flip back “Short” sell-triggers...For the S&P, 3989 is key for a big purge (with 4094 the next support to watch at 100DMA), but forthe Nasdaq 100 the 'level to sell' is close at 12,587.2. Vol Control is the local tie-breaker, and it’s nuanced as-everVol Control in the NEAR-TERM (next two weeks) would require sustained 2.0% daily chg type days in-order to see a pivot back towards de-allocation (2% daily chg = -$4.7B over the next two weeks)—or, as an alternative, larger 1d absolute Vol shocks (e.g. a 3.0% SPX change today would see -$2.3B of VC de-allocation selling)3. From a Vol mkt perspective, Spot lower / Vol higher and resumption of downside hedging demand(Skew actually performed on Friday) will see NEGATIVE $Delta flows picking back-up.
For the Nomura strategist, the key for this nascent selloff to hold is going to be the willingness then of ACTIVE / DISCRETIONARY traders to again “lean into” the market and resume “Shorting” HERE AND NOW while the post Op-Ex “window for Vol expansion” is open, and / or take down “Nets” again ahead of a rough seasonal for Equities, coming after what’s been a vicious two month covering explosion across previously “grossed-UP” Shorts in “worst of” themes...
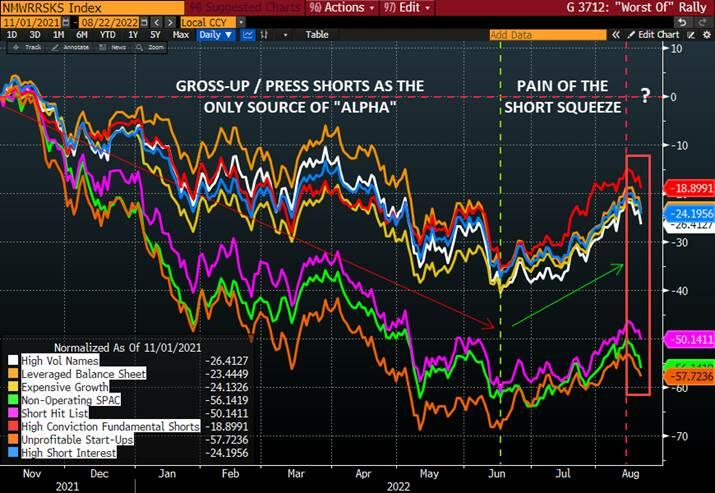
...so there is some scar tissue to sort out.
Research Calls
- Upgrades:
- Bruker (BRKR) upgraded to Buy from Neutral at Citigroup; tgt raised to $80
- Elevance Health (ELV) upgraded to Outperform from Mkt Perform at SVB Leerink; tgt raised to $580
- Foot Locker (FL) upgraded to Equal-Weight from Underweight at Morgan Stanley; tgt raised to $36
- Foot Locker (FL) upgraded to Equal Weight from Underweight at Barclays (Friday)
- Salzgitter AG (SZGPY) upgraded to Neutral from Underperform at Credit Suisse
- Schneider National (SNDR) upgraded to Outperform from In-line at Evercore ISI; tgt $28
- Vipshop (VIPS) upgraded to Neutral from Sell at Citigroup; tgt raised to $10.90
- Vipshop (VIPS) upgraded to Outperform from Neutral at Credit Suisse; tgt raised to $12
- Youdao (DAO) upgraded to Outperform from Market Perform at CICC; tgt $7
- Downgrades:
- Canadian Nat'l Rail (CNI) downgraded to In-line from Outperform at Evercore ISI; tgt $129
- Cochlear (CHEOY) downgraded to Neutral from Buy at Citigroup
- Coupa Software (COUP) downgraded to Underperform from Sector Perform at RBC Capital Mkts; tgt lowered to $55
- DocuSign (DOCU) downgraded to Sector Perform from Outperform at RBC Capital Mkts; tgt lowered to $65
- Gritstone bio (GRTS) downgraded to Sell from Neutral at Goldman; tgt $2
- Intra-Cellular Therapies (ITCI) downgraded to Neutral from Buy at Goldman; tgt lowered to $49
- NeoGenomics (NEO) downgraded to Hold from Buy at Needham
- Saia (SAIA) downgraded to In-line from Outperform at Evercore ISI; tgt $243
- UPS (UPS) downgraded to In-line from Outperform at Evercore ISI; tgt $214
- V.F. Corp (VFC) downgraded to Market Perform from Outperform at Cowen; tgt lowered to $50
- Others:
- AmerisourceBergen (ABC) assumed with an Equal-Weight at Morgan Stanley
- Cardinal Health (CAH) assumed with an Overweight at Morgan Stanley; tgt raised to $76
- C.H. Robinson (CHRW) added to Tactical Outperform List at Evercore ISI
- CinCor Pharma (CINC) initiated with an Overweight at Piper Sandler; tgt $73
- FedEx (FDX) added to Tactical Outperform List at Evercore ISI
- Illumina (ILMN) added to 90-day Positive Catalyst Watch at Citigroup
- Laboratory Corp (LH) assumed with an Overweight at Morgan Stanley; tgt $300
- McKesson (MCK) assumed with an Overweight at Morgan Stanley
- Millicom International Cellular (TIGO) resumed with a Reduce at HSBC Securities; tgt $14
- Quest Diagnostics (DGX) assumed with an Equal-Weight at Morgan Stanley; tgt $142
- Waldencast plc (WALD) initiated with an Outperform at Raymond James; tgt $11
Gapping up
News:
- MSPR +25.6% (reports growth to 34 million unique healthcare member lives)
- GTH +3.4% (receives Non-Binding Proposal to be acquired for $1.36 per ADS)
- VXX +1.8% (trading higher with US futures under pressure)
- PODD +0.5% (receives FDA clearance for Omnipod 5 for children aged two years and older with type 1 diabetes)
Analyst comments:
- VIPS +0.9% (upgraded to Neutral from Sell at Citigroup; upgraded to Outperform from Neutral at Credit Suisse)
Gapping down
Select index ETFs showing early weakness:
- QQQ -1.5%, SPY -1.1%, IWM -1.1%, DIA -0.9%, .
Other news:
- AMC -31% (APE shares to begin trading today - CEO tweeted: Remember, with the APE seeing its first trade on the NYSE at some time tomorrow morning, the value of your AMC investment will be the combination of your AMC shares and your new APE units. An AMC share plus a new APE unit added together — compared to just an AMC share previously)
- ADES -28.2% (to merge with Arq Limited)
- BBBY -10.8% (report some suppliers are restricting or halting shipments as BBBY fell behind on payments, according to Bloomberg)
- MREO -5% (Sends Letter to Rubric Capital Management)
- RVLP -4.4% (files for 15,451,612 share common stock offering by selling shareholders)
- TSLA -2.2% (Elon Musk tweets "After wide release of FSD Beta 10.69.2, price of FSD will rise to $15k in North America on September 5th. Current price will be honored for orders made before Sept 5th, but delivered later")
- CS -1.3% (appoints Dixit Joshi as CFO)
- OXY -1.3% (Warren Buffett (BRK.B) is not expected to bid for control of Occidental)
- INST -1.2% (files for $800 mln mixed securities shelf offering; also files for 122,065,804 share common stock offering by selling shareholders)
- VOD -1.2% (agrees non-binding terms in relation to the sale of Vodafone Hungary for €1.8 billion to 4iG and Corvinus)
- WEN -0.9% (CDC confirms E. coli outbreak with unknown food source; WEN says "we are taking the precaution of discarding and replacing the sandwich lettuce at some restaurants in that region")
- VIAV -0.8% (files mixed securities shelf offering)
- GILD -0.7% (receives EC Marketing Authorization for Sunlenca)
Analyst comments:
- GRTS -12.2% (downgraded to Sell from Neutral at Goldman)
- COUP -4.1% (downgraded to Underperform from Sector Perform at RBC Capital Mkts)
- DOCU -4.1% (downgraded to Sector Perform from Outperform at RBC Capital Mkts)
- ITCI -2.8% (downgraded to Neutral from Buy at Goldman)
- VFC -2.7% (downgraded to Market Perform from Outperform at Cowen)
- NEO -2.5% (downgraded to Hold from Buy at Needham)
- UPS -2.1% (downgraded to In-line from Outperform at Evercore ISI)
- CNI -1.6% (downgraded to In-line from Outperform at Evercore ISI)
Early premarket gappers
- Gapping up:
- MSPR +40.9%, GTH +6.8%, VXX +1.6%, DSX +1.5%, PODD +0.6%, SKYT +0.5%
- Gapping down:
- ADES -20.4%, BBBY -8.6%, RVLP -4.4%, TSLA -2.3%, QQQ -1.3%, VOD -1.3%, OXY -1.3%, INST -1.2%, SPY -1.1%, GILD -1.1%, CS -1.1%, IWM -1%, WEN -0.9%, VIAV -0.8%, DIA -0.8%, MREO -0.8%
Europe’s Natural-Gas Crunch Sparks Global Battle for Tankers
Charter rates and prices for new LNG tankers surge as Europe looks for alternatives to throttled Russian gas supplies
Europe’s energy crisis has unleashed a global battle over natural-gas tankers, leading to a shortage of ships and further boosting the fuel’s record prices.
European countries ramped up their purchases of liquefied natural gas from the U.S., Qatar and other sources this year as Russia cut supplies to the continent. They are competing with peers in South Korea and Japan—where gas demand has surged during a heat wave—for a finite amount of supply ferried by a limited number of vessels.
The jostling has increased orders for new tankers transporting LNG—specialized ships the length of three football fields—as well as their price. Rates to charter existing tankers have jumped too, which helped push gas prices to records in Europe and Asia last week. Traders expect gas prices and tanker rates to zoom even higher if China, where demand has been curtailed by Covid-19 lockdowns, steps back into the market before winter.
The race to secure tankers is another sign of the reshuffling of the global energy map following Russia’s invasion of Ukraine. The war has intensified competition for tight energy supplies, reoriented commodity flows and fractured parts of the global oil-and-gas market, with supporters and opponents of Russia paying different prices.
LNG and the tankers that carry the fuel were in high demand even before the conflict, as extreme weather curtailed hydropower and many economies sought to ditch coal to reduce carbon emissions. The war has turbocharged that trend.
Before the war, Russia covered 40% of the European Union’s gas supplies, mostly via a network of pipelines. Given that it will take time to upgrade the continent’s pipeline network to receive imports from other nearby exporters, the main short-term alternative is LNG, which can be bought from producers further away and shipped, albeit at a higher price.
In the production of LNG, gas is chilled to minus 260 degrees Fahrenheit and shrunk to a liquid that can be stored and shipped to terminals. There it is returned to a gas state and used to power factories and heat homes.
Just one LNG tanker is available to be chartered for a single voyage in Asia two months or more from now, said Jason Feer, head of business intelligence at Poten & Partners, a shipbroker. None is available in the Atlantic Ocean.
“Everything out there is going to be snapped up,” said Toby Copson, head of trading and advisory at Shanghai-based Trident LNG. “Effectively you’ve got Europe and Asia bidding against each other and propping the market up.”
The scramble for ships adds another challenge for Europe, where governments are racing to fill storage facilities ahead of the heating season and companies are buckling under high gas prices. Russia has capped deliveries to Germany via the key Nord Stream pipeline at 20% of its capacity, blaming Western sanctions. German and European officials have called the throttling an economic attack.
Amid the gas rush, daily charter rates for existing tankers that traders will take hold of between mid-September and mid-November have risen to $105,250 a day, up from about $64,000 now and about $47,000 a year ago for vessels heading from the U.S. to Europe, according to Spark Commodities.
Rates were above $100,000 a day in June, before dropping when a fire at an LNG export facility in the U.S. reduced exports and demand for boats. Analysts and traders expect them to rebound because trading companies have booked many more boats on a long-term basis to make sure they can ferry LNG, in turn reducing the pool of vessels immediately available.
To avoid getting caught out in the future, traders are going on a buying spree for ships. Customers have shelled out $24.1 billion on orders for new LNG tankers—including orders for eight vessels in August—so far in 2022, according to Stephen Gordon, managing director at London-based shipping firm Clarkson. They have already blown past the full-year record of $15.6 billion from 2021.
Currently, 257 vessels are on the order book globally, according to consulting firm Rystad Energy. Shipmakers in South Korea, the world’s biggest producer of LNG tankers, don’t have free capacity for new orders until 2027, Rystad estimates.
Among the biggest buyers of LNG tankers is Qatar, one of the world’s largest LNG exporters. This tiny Persian Gulf kingdom has emerged as one of Europe’s best hopes to wean itself off Russian gas, and European countries have been in talks with it about long-term LNG contracts.
Demand for tankers has raised the price of the new vessels. Surging steel prices and limited shipyard capacity are also contributing to the tanker inflation, with newbuild prices approaching $240 million a ship from $190 million a year ago, according to Rystad.
Higher tanker prices and rising rates for chartering ships are feeding into the LNG value chain and boosting already high gas prices worldwide, said Kaushal Ramesh, an analyst at the consulting firm. “The recent focus on energy security means the entire market has gone back to taking a long-term view on supply and shipping,” he said.
Demand has also risen for so-called floating storage and re-gasification units, which are often converted LNG tankers moored at the coast. Setting up these facilities, known as FSRUs, is faster than building a dedicated LNG terminal, which usually takes years.
Across Europe, 14 FSRUs are currently planned. FSRU charter rates have risen to $200,000 a day in some cases, more than double the rate in early 2021, according to Rystad.
Germany, which had for years been dependent on cheap Russian piped gas, doesn’t have a single LNG terminal. Now, Berlin is planning to have two such FSRUs ready by the end of the year, with several others following next year.