FT : ‘Colossal’ central bank buying drives gold demand to decade high

‘Colossal’ central bank buying drives gold demand to decade high
Fallout from US sanctions on Russia helped fuel 18 per cent leap in purchases last year

Demand for gold surged to its highest in more than a decade in 2022, fuelled by “colossal” central bank purchases that underscored the safe haven asset’s appeal during times of geopolitical upheaval.

Annual gold demand increased 18 per cent last year to 4,741 tonnes, the largest amount since 2011, driven by a 55-year high in central bank purchases, according to the World Gold Council, an industry-backed group.

Central banks hoovered up gold at a historic rate in the second half of the year, a move many analysts attribute to a desire to diversify reserves away from the dollar after the US froze Russia’s reserves denominated in the currency as part of its sanctions against Moscow. Retail investors also piled into the yellow metal in a bid to protect themselves from high inflation.

Central bank purchases of gold hit 417 tonnes in the final three months of the year, roughly 12 times higher than the same quarter a year ago. It took the annual total to more than double of the previous year at 1,136 tonnes.

Krishan Gopaul, senior analyst at the WGC, said “colossal” central bank buying is a “huge positive for the gold market”, even as the industry group predicted that it would be tough to match last year’s purchases because of a slow down in total reserve growth.

“Since 2010 central banks have been net purchasers of gold following two decades of net sales. What we have seen recently in this environment is central banks have accelerated their purchases to a multi-decade high,” he said. He added that a lack of “counterparty risk” was a key attraction of the metal for central banks, compared with currencies under the control of foreign governments.


Only about a quarter of the fourth-quarter central bank purchases were reported to the IMF. Reported purchases in 2022 were led by Turkey taking in almost 400 tonnes, China, which reported buying 62 tonnes in November and December, and Middle Eastern nations.

Gold industry analysts widely believe the remainder is accounted for by central banks and government agencies in China, Russia and the Middle East, which can include sovereign wealth funds.

James Steel, a veteran precious metals analyst at HSBC, said that “portfolio diversification is the main reason” for US dollar-laden central banks buying gold. He adds that “a key reason for choosing gold is that central banks are limited in what assets they can hold, and they may be reluctant to commit to other currencies”.

Demand among retail investors for bar and coins also jumped to a nine-year high in 2022 above 1,200 tonnes with strong demand in Europe, Turkey and the Middle East offsetting weakness in China where buyers were housebound by Covid lockdowns.

Gold prices slid from a record high last March above $2,000 to just above $1,600 per troy ounce in November as rising interest rates led to outflows from gold-backed exchange traded funds equivalent to $3bn over the year. Gold produces no yield, dulling its appeal to investors when interest rates on low-risk bonds climb.

However, demand from central banks and retail investors helped prevent the yellow metal sliding further and set the stage for a powerful rally since November.


In those three months, gold has jumped almost a fifth to $1,928 per troy ounce — its highest level in nine months — helped by the US Federal Reserve signalling that it would slow down the pace of rate hikes.

The WGC expects a revival in gold demand from institutional investors this year as interest rates in main economies approach their peak, while falling inflation could damp demand for bars and coins.

As a result of exceptional central bank buying and an expected return of inflows for gold-backed ETFs, UBS raised its year-end target for the precious metal to $2,100 per troy ounce, up from $1,850 previously.

>>> US After Hours Summary: SYM +10.9% and WHR +1.5% up on earnings, CRK +6.6% u

After Hours Summary: SYM +10.9% and WHR +1.5% up on earnings, CRK +6.6% up on news it will replace ADC in the S&P SmallCap 600; HLIT -8.6%, ITGR -5.4%, NXPI -3.3%, PCH -2% on earnings, DASH -2% on future stock sales announcement by co-founders

After Hours Gainers:

Companies trading higher in after hours in reaction to earnings/guidance: SYM +10.9%, CSWC +2.5% (also increases dividend), ARE +2.3%, HP +1.5%, WHR +1.5%, PFG +0.7%, CFLT +0.4%

Companies trading higher in after hours in reaction to news: CRK +6.6% (replacing ADC in the S&P SmallCap 600), GRPN +1.6% (to reduce 500 global positions), ALB +0.2% (launches subsidiary Ketjen), AAPL +0.1% (executives violated worker rights, according to Bloomberg)

After Hours Losers:

Companies trading lower in after hours in reaction to earnings/guidance: HLIT -8.6%, ITGR -5.4% (Q4 and FY23 guidance; to offer $375 mln principal amount of its convertible senior notes), NXPI -3.3%, PCH -2%, AGNC -0.7%, CADE -0.4%, ELS -0.1%, JJSF -0.1%

Companies trading lower in after hours in reaction to news: BBAI -6.1% (stock offering by selling shareholders), ADC -2.9% (replacing STOR in S&P MidCap 400), DASH -2% (announces future stock sales by co-founders), STZ -1.8% (prices public offering of $500 mln senior notes), PARA -0.5% (Showtime to merge with Paramount+, according to The Information), DG -0.4% (CFO to retire), LOGI -0.2% (names new CEO and COO), GABC -0.1% (increases quarterly dividend)

>>> US Close Dow -0,77% S&P -1,30% Nasdaq -1,96% Russell -1,35%

Closing Stock Market Summary

This busy week for the stock market got started on a downbeat note as investors took some money off the table following a strong showing this month. Entering today, the Nasdaq and S&P 500 were up 11.0% and 6.0%, respectively, so far in January. The main indices spent most of the session on a steady decline, ultimately settling near their worst levels of the day. 

Investors took a more cautious approach today in front of policy decisions from the Fed, the ECB, and the Bank of England later this week. The skittishness around the FOMC decision largely relates to Fed Chair Powell's press conference and the possibility that Mr. Powell will make a concerted effort on Wednesday to rein in the market's enthusiasm by tamping down its optimism over any potential rate cuts this year.

On a related note, Nick Timiraos of The Wall Street Journal wrote over the weekend that Fed officials are concerned that inflation could reaccelerate due to tight labor markets. Mr. Timiraos added in a Monday article that the Fed's interest rate strategy could depend on how much members believe the economy will slow.

Some hesitation today on the part of buyers stemmed from a wait-and-see mindset ahead of several market-moving data releases, including the Q4 Employment Cost Index, the January ISM releases, and the January Employment Situation Report.

In addition, more than 100 S&P 500 companies will be reporting earnings this week, headlined by Meta Platforms (META 147.06, -4.68, -3.1%), Apple (AAPL 143.00, -2.93, -2.0%), Alphabet (GOOG 97.95, -2.76, -2.7%), and Amazon.com (AMZN 100.55, -1.69, -1.7%). Mega cap stocks had been leading the January charge, but trailed the broader market today as they succumbed to profit-taking interest. The Vanguard Mega Cap Growth ETF (MGK) closed down 1.9% versus a 1.1% loss in the Invesco S&P 500 Equal Weight ETF (RSP) and a 1.3% loss in the S&P 500.

Downside leadership from the mega cap space was evident in S&P 500 sector performance. The information technology (-1.9%), communication services (-1.8%), and consumer discretionary (-1.7%) sectors were among the worst performers today. 

Energy (-2.3%) was the top laggard for the 11 sectors as oil prices faded ahead of the OPEC+ meeting later this week. WTI crude oil futures fell 1.9% to $77.94/bbl.

Only one sector -- consumer staples (+0.1%) -- was able to maintain a slim gain by the close.

  • Nasdaq Composite: +8.9% YTD
  • Russell 2000: +7.3% YTD
  • S&P Midcap 400: +6.8% YTD
  • S&P 500: +4.6% YTD
  • Dow Jones Industrial Average: +1.7% YTD

There was no U.S. data of note today.

Caterpilllar (CAT), Exxon Mobil (XOM), General Motors (GM), Marathon Petroleum (MPC), McDonald's (MCD), Pfizer (PFE), Phillips 66 (PSX), PulteGroup (PHM), Spotify (SPOT), Sysco (SYY), and UPS (UPS) are among the notable companies reporting earnings ahead of tomorrow's open. 

Looking ahead to Tuesday, market participants will receive the following economic data:

  • 8:30 a.m. ET: January Chicago PMI ( consensus 45.4; prior 44.9), Q4 Employment Cost Index ( consensus 1.1%; prior 1.2%)
  • 9:00 a.m. ET: November FHFA Housing Price Index (prior 0.0%), November S&P Case-Shiller Home Price Index ( consensus 6.8%; prior 8.6%)
  • 10:00 a.m. ET: December Consumer Confidence ( consensus 108.1; prior 108.3)

Business Of Fashion : Matchesfashion Secures £60m Support Package From Owner

Matchesfashion Secures £60m Support Package From Owner

Apax Partners, the private equity firm which acquired the luxury retailer in 2017, has agreed to inject £60 million ($74.2 million) into the business, a spokesperson for the company confirmed Monday.

The retailer’s support package was first reported by Sky News.

The financing is intended to support the business through its turnaround plan under chief executive Nick Beighton, who became the company’s fourth chief executive in as many years when he joined the business in July.

The additional financing means Matchesfashion will be in a better position to use “technology, product, logistics and culture, to help grow the top line of the business as well as our profitability,” Beighton told BoF over email on Monday.

In November, former Asos chief Beighton told BoF that “a recovery is already underway” at Matchesfashion after a turbulent few years for the retailer.

WWD : Sotheby’s to Auction Hong Kong Property Tycoon Joseph Lau’s Rare Hermès Ba

Sotheby’s to Auction Hong Kong Property Tycoon Joseph Lau’s Rare Hermès Bags
The collection of 77 limited-edition bags, including six diamond Birkins, is valued at $2 million.
The first batch of 77 rare bags, which Lau acquired over the past two decades, is valued at 16.3 million Hong Kong dollars, or $2 million. Part of the sale proceeds will go to charity, Sotheby’s revealed.
Touted as the largest single-owner handbag sale in Asia, the lot includes a shearling Teddy Kelly 35 and a So Black Kelly 35, both from the Jean-Paul Gaultier era at Hermès, circa 2004 to 2010.

There is also a rare bespoke multicolored Fringe Birkin 35 in red leather, as well as six diamond Birkins of various sizes in blue jean, matte, electric blue, red, violet and fuchsia.

The blue jean shiny croc Bikin 25 with 18-karat white gold and diamond hardware is valued between 1 million and 2 million Hong Kong dollars, or $127,000 to $254,800, and is the priciest item on offer. The rest of the diamond Birkins are valued between 400,000 and 700,000 Hong Kong dollars, or $50,960 to $89,180.
Hermès Limited Edition Bronze Chèvre Metallic Kelly 25 Sellier Gold Hardware, 2005
SOTHEBY’S
Other prized pieces in the auction include a Rose Bonbon mini Kelly 20, an Orange Kelly Doll and a Bronze Metallic Kelly 25, which according to Sotheby’s was only in production between 2004 to 2005. The color of the bag was inspired by the window displays designed by Leïla Menchari for the Hermès flagship store at Rue du Faubourg Saint-Honoré in Paris. The Metallic Kelly bag is valued between 400,000 to 600,000 Hong Kong dollars, or $50,960 to $76,440.

Morgane Halimi, global head of handbags and accessories, said, “The limited-edition pieces that have made and shaped the history of handbags in the past two decades can all be found in this collection.”
With a net worth of $13.6 billion, according to Forbes, Lau is the former chairman of property developer Chinese Estates. He is best known by the public in Hong Kong for love affairs with several high-profile actresses in the past two decades, which often involved gifting rare bags and high jewelry as proof of affection.

He has been married to former showbiz journalist Kimbee Chan since 2016. They have two children.
In 2017, Lau transferred 75 percent of his shares in Chinese Estates to Chan and their son, citing serious health issues. This made Chan the richest woman in Hong Kong. Chan is also an avid rare Hermès bag collector.

>>> RheinMetall : American Rheinmetall Vehicles and GM Defense awarded multi-pha

American Rheinmetall Vehicles and GM Defense awarded multi-phase program to replace the US army's heavy tactical trucks with production of up to 40K new trucks valued at up to $14B

American Rheinmetall Vehicles (Sterling Heights, MI) and GM Defense LLC (Washington, DC) have won a contract for the first phase of the U.S. Army’s Common Tactical Truck (CTT) Program. The aim of the multi-phased program is to replace the Army’s family of heavy tactical trucks with production of up to 40,000 trucks valued at up to $14 billion. The two powerhouse defense companies formed a strategic collaboration in 2022 to compete in the program; bringing together two world-class engineering and manufacturing giants to deliver a modern, tactical truck that enhances Soldier capability through advanced technologies including advanced driver assistance systems (ADAS) for safety, increased off-road mobility, cybersecurity, machine learning, artificial intelligence, improved survivability and fuel efficiency, among other emerging technologies.

The team offered the HX3 Common Tactical Truck (HX3-CTT). The HX3 is the latest generation of trucks in the highly successful, combat proven, HX family of trucks which are in service with a number of NATO and U.S. allied nations. The HX family of trucks derives from MAN Truck and Bus commercial truck offerings bringing a high degree of commerciality to the fleet, a priority for the Army in the CTT program. The HX3-CTT next-generation system has enhanced on and off road mobility, integrated survivability, and an open digital architecture supporting ADAS and enabled for autonomous vehicle operation. Combined with the open architecture, the commercial backbone of the HX3-CTT will support persistent modernization and allow for rapid increases in capability as technologies mature. With a global footprint of both current military user nations and commercial dealer networks, the HX3-CTT provides a basis for optimized lifecycle costs and service support to the Army across the globe.

FT : Renault/Nissan: equal footing is the first step back to relevance

Renault/Nissan: equal footing is the first step back to relevance
Drastic measures to revive a venerable alliance are not the end of the road

Cars can register as classics after 20 years. But creaky auto alliances, such as Renault’s with Nissan of Japan, are another matter. A two-decade relationship designed to foster trust, co-operation and prosperity instead grew rusty. Drastic measures led by Renault chief executive Luca de Meo were formalised on Monday.

Renault’s dominance will be reined in. Its stake in Nissan will fall to 15 per cent or equal to Nissan’s cross holding in Renault. This ends a rivalry where the smaller manufacturer was viewed as too powerful. The balance of Renault’s 43.4 per cent stake in the Japanese company will go into a French trust. Economic benefits are maintained, but voting rights are neutralised. No commitment for a sale has been made.

Markets had begun to price in an improved collaboration between Renault and Nissan, hoping for more on electric vehicles and growth in emerging markets. Even after outperforming the global sector by 85 per cent since the start of last year, Renault shares remain historically cheap in Europe at about 4 times 2023 earnings.

If doubts remain they rest with Renault’s plans for its electric vehicle unit Ampere. Nissan promises to buy into its upcoming IPO late this year. Perhaps one-fifth of the shares would be sold. This will split Renault into EV and internal combustion engine makers, a first for the industry. Ampere could be worth €10bn, thinks Jefferies. Bulls expect at least double that based on Tesla’s past success.

Most important is the road directly ahead. New, more profitable models from next year should help boost operating margins above 5 per cent by 2025. These peaked at 6.5 per cent in 2017. More important, free cash flow of more than €2bn from this year to 2025 should begin to accumulate, thinks Bernstein.

Renault and Nissan deserve credit for achieving a compromise. Yet this one does not immediately simplify the structure — it leaves an overhang for lots of Nissan shares. The listing of Ampere is the next test for Renault.

(ZH) "Recession Is On Its Way" - Dallas Fed Shows Factory Activity Slumps For 9t

"Recession Is On Its Way" - Dallas Fed Shows Factory Activity Slumps For 9th Straight Month

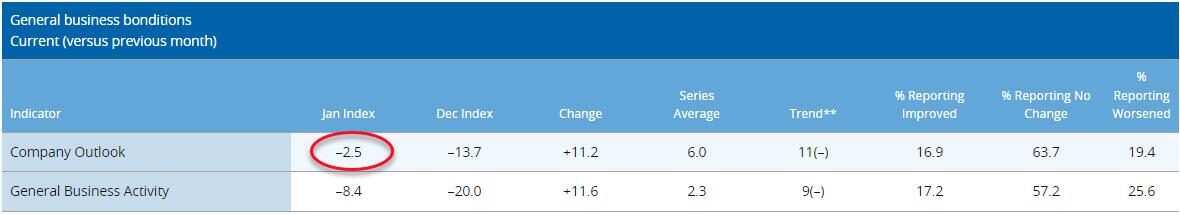
While the headline Dallas Fed Manufacturing Activity Index printed better than expected (-8.4 vs -15.0), it remains in contraction (less than zero) for the 9th straight month (the longest streak since 2016)...
Source: Bloomberg
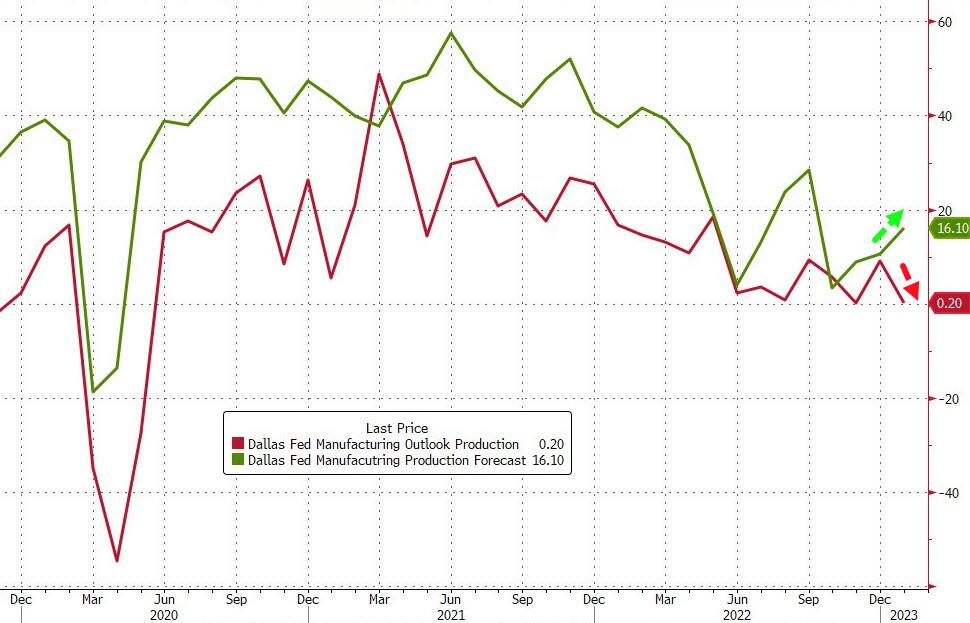
And in fact, the better than expected print was driven solely by 'hope' as current production tumbled in January but 'expectations' for future production rose...
Source: Bloomberg
Surprisingly, while the outlook for six-months ahead improved (but remains negative)...
...you wouldn't know it judging by the responses that The Dallas Fed decided to release for publication... notice a pattern?
Food manufacturing
  • We had a customer in the pet food segment significantly decrease its orders due to an inventory backlog.
  • Uncertainty from the overall economic downturn is affecting our long-term strategy.
  • Business is sluggish. We’re seeing increased illiquidity in our customer base.
Beverage and tobacco product manufacturing
  • We are still seeing input costs increase. We had let our gross margin erode over the last couple of years and are now playing catch-up. We are raising prices faster than our inputs increase in a bid to restore an acceptable gross margin. This is resulting in slightly increased dollar sales and increased gross margin, but decreased unit sales. We also had many of our older 3G-based [wireless] credit card readers that we mistakenly thought also had 4G capability stop working due to the phase-out of 3G. New 4G/5G radios are on a several-month back order. Some unknown share of our sales decline is due to lack of credit card readers at the point of sale.
Textile product mills
  • Uncertainty is high. Holiday sales were stronger than expected, but January is slow versus last year. Delivery times are down, but future demand and sales sentiment are low.
Paper manufacturing
  • Activity continues to slip, and selling prices are coming down. We still can’t find any workers and, with our six-month projection, we have quit looking.
Printing and related support activities
  • We have definitely seen a slowdown in activity compared to prior months. It's as if the spigot got turned off. All our supply-chain constraints are pretty much gone, with delivery times much more like prepandemic times. We have work coming up but right now are very slow and struggling to get our hourly workers even 32 hours per week.
Chemical manufacturing
  • Lost production due to Winter Storm Elliot caused tightening of our inventory levels.
  • We are seeing a slowdown in orders and clients unwilling to hold additional inventory.
Primary metal manufacturing
  • Recession is on its way.
  • The residential building and construction industry has seen a significant decrease in orders across the extrusion industry. Also, imports of aluminum extrusions from South America, Mexico, Malaysia, Vietnam, Turkey and India are at record highs. Mexico is gaining more and more business in the U.S. due to not having to pay Section 232 tariffs, whereas U.S. domestic extruders are paying the tariff via our raw aluminum or billet purchases. If action is not taken, the U.S. aluminum extrusion industry as we know it today will be shutting down capacity and plants.
Machinery manufacturing
  • We are seeing improvement in the business climate. Our competitors are coming to us to supply their customers. Additionally, we are purchasing new machines to add capabilities in our business and further vertically integrate our manufacturing. This will improve our profitability and reduce lead time to produce our products.
  • Order volume has been going down, and we expect the trend to continue. Raw material pricing seems to be stable at the present time.
  • Current federal policies are killing small businesses. From diesel prices to shortages, everything costs so much more.
Computer and electronic product manufacturing
  • We provided significant (10 percent or more) raises in December after a midyear raise in July 2022. We felt that this was essential in order to keep our employees, and we have successfully retained everyone we wanted to keep. We hope not to need to do another round of raises midyear. Since our employees are blue-collar workers, inflation hits them particularly hard, and they are more willing to look for another job for a 10–15 percent pay increase. We are investing in more automation and removing process bottlenecks to increase productivity and reduce lead time.
Transportation equipment manufacturing
  • We have a bleak outlook until the Federal Reserve stops interest hikes and the administration seeks energy independence.
  • We are starting to see some customers pushing delivery out due to market uncertainty.
Furniture and related product manufacturing
  • Requests for bids continue at a steady rate; we have not yet seen a contraction. The only change is, when posting job openings, we actually have people responding—this is a big change and likely a sign of some layoffs after the holidays from other companies. The biggest issues facing our company are increased regulations and contact from federal, state and local entities regarding a variety of topics. Often it feels as a small business that the government does not want us to succeed.
Miscellaneous manufacturing
  • We continue to see large fluctuations in raw material pricing from order to order. Pricing has not corrected from the metals market shutdown in March 2022. Most lead times for raw material remain longer than in previous years.
  • Order volumes remain flat across all markets we serve—automotive OEM [original equipment manufacturers], plumbing and ammunition. Raw material costs and lead times have declined since 2022.
Not exactly a picture of the 'strong as hell' economy we hear from The White House?