Business Of Fashion : What Hermès Really Thinks About NFTs

What Hermès Really Thinks About NFTs
In the opening days of its trial against the MetaBirkins creator, the luxury house revealed some of its own thinking around web3 and virtual worlds.

Hermès’ battle against the MetaBirkins NFTs isn’t just about protecting its brand in the physical world, it turns out.

The French luxury house sees web3 and virtual worlds as part of the future and has been investigating releasing its own NFTs, the company’s global general counsel, Nicolas Martin, testified Tuesday in a high-stakes trial pitting Hermès against Mason Rothschild, creator of the colourful digital interpretations of its iconic Birkin.

Hermès, unlike a number of peers in the luxury world, has so far abstained from jumping into the blockchain-based digital assets, suggesting perhaps it saw NFTs and other virtual goods as incompatible with its brand, known above all for its exquisite materials and meticulous craftsmanship. But the company has been actively researching a variety of virtual opportunities, according to Martin. (Hermès has also applied for trademarks on various virtual assets, though sometimes brands use the tactic just to keep others from grabbing them.)

Martin shared the behind-the-scenes details while taking questions from Hermès’ attorneys in the case, which is taking place in a Southern District of New York courtroom in lower Manhattan. For a year now, Hermès has been in a legal battle with Rothschild, who it accuses of infringing and diluting its trademarks on the Birkin’s name and design. Rothschild contends his MetaBirkins NFTs are artistic expression and therefore protected as free speech in the US. The two sides were unable to reach a settlement or win a summary judgment, so a jury trial has now commenced.

Of course, it serves Hermès’ case to say the company was planning its own NFTs. It wouldn’t just be physical goods then but also any forthcoming digital items it could claim are affected by Rothschild’s MetaBirkins. Martin said in his testimony the company suffered by having lost the opportunity to be first into the digital market with a Birkin product.

He also described a number of other virtual products Hermès is considering.

One he mentioned was an NFT-based digital twin of a physical good. In an example, Martin said you might buy a scarf from Hermès and receive access to a digital file — presumably the NFT-linked asset — that shows the scarf moving and gives you the story behind the product.

Hermès has also looked into offering NFTs to attendees of events. He didn’t specify what type of event but one could imagine guests of one of the brand’s runway shows might receive one.

Not least of all, he noted that the communications department is working on what he described as a small metaverse where individuals could interact.

The ideas aren’t entirely novel. Digital twins are one of the more widely explored roles for NFTs in luxury, with proponents including the Aura Blockchain Consortium — founded by LVMH, Prada and Cartier — touting them as a means to provide an item with a public and tamper-proof certificate of authenticity. And NFTs given out as proof of attending an event are common in the web3 world. They’re called proof of attendance protocols, or POAPs.

There’s also no guarantee any of these products will ever be released to the public. Hermès — and other luxury companies in a similar position — could ultimately decide they aren’t a fit for the brand and abandon them in the research phase. But they show Hermès isn’t simply sitting by watching others dive into virtual goods without considering the opportunities.

Whether the existence of Rothschild’s MetaBirkins would have any impact on Hermès’ success in these spaces is debatable. They’re effectively collectables without any utility; they can’t be used in any virtual environments, for instance. It doesn’t seem as if Hermès planned to release NFTs of this sort.

But that’s far from the only issue that will determine the outcome of the case. Some other vital matters involved include whether the MetaBirkins confused consumers into thinking the project was somehow sanctioned by Hermés; whether their artistic value is trivial compared to how much they infringed on Hermès trademarks for financial profit; and not least of all, whether the technical underpinnings of an NFT matter here.

We commonly talk about NFTs as whatever image they show, whether a digital Birkin or mutant ape. But an NFT is just a bit of code on a blockchain. To keep the file size smaller — and thus processing workloads and transaction fees lower — many collectable NFTs, including the MetaBirkins, use a workaround where the image isn’t on the blockchain itself. It exists in a separate repository and the NFT just points to it. In theory, whoever controls that repository could change that image, though the NFT code would stay the same. So is the NFT just the code or is the image included?

Already the trial has delved into these technical issues, leaving the judge, Jed Rakoff — who also happened to preside over Adidas’ losing trademark dispute with Thom Browne — frustrated at the lack of clarity. He seemed inclined to say an NFT and the image are one and the same. It’s too early to say whether if or how any of these technical distinctions will factor into the jury’s decision.

Business Of Fashion : Swatch Group Raises Prices For Omega SpeedMaster Watches,

Swatch Group Raises Prices For Omega SpeedMaster Watches, Following Rolex’s Lead

Luxury watch conglomerate Swatch Group AG raised prices across a slew of its brands, increasing the cost of the flagship Omega Speedmaster by about 7 percent in the UK and Europe, according to investment bank Jefferies.

The price of an Omega Speedmaster automatic watch with a moonphase complication in the UK is now £10,600 ($13,060) as of Feb. 1, up 7.1 percent compared to January last year, Jefferies analysts led by Kathryn Parker said in a report. Prices for the same model rose an average of 6.8 percent in Italy and 2 percent in the US.

Increases at Swatch brands including Omega, Longines and Tissot follow a similar move by the top Swiss watchmaker Rolex SA to boost prices by about 2.5 percent in the UK and Europe in January. Rolex had already raised prices across the continent in the autumn, in an unusual move, to counter rising costs and currency fluctuations caused by a strong US dollar and Swiss franc against a weaker sterling and euro. Rolex usually raises prices just once a year.

The uplift shows Swatch brands believe consumers will accept steeper prices as demand for high-end timepieces stays strong.

Luxury watch brands including Rolex and Omega are ramping up prices in the UK, Japan and South Korea by more than other locations to offset weaker currencies and to prevent price discrepancies across regions and countries, according to the note. For example, the cost of an Omega Seamaster 300 dive watch rose by at least 6.5 percent in all three countries, compared to more modest uplifts in the US and China.

The price of the hit MoonSwatch, the budget-friendly, bio-plastic Swatch version of the Omega Speedmaster, rose in Korea and Japan by more than 7 percent. Swatch Group, which sold a million MoonSwatch units last year, did not increase prices in the US, UK and Europe where the popular timepiece sells for about €260 ($283).

A spokesman for Swatch Group declined to comment on the report.

Swatch chief executive Nick Hayek told Bloomberg News last week that the company could hit record sales of as much as 9 billion Swiss franc ($9.8 billion) in 2023 as China reopens.

Swiss watch exports hit a record 24.8 billion Swiss francs by value in 2022, rising 11.8 percent from the year before. Export growth slowed in December to 5.8 percent.

WSJ : EA Shows Why Mobile Games Are a Minefield

EA Shows Why Mobile Games Are a Minefield
‘Apex Legends Mobile’ misfire drives videogame publisher to pull plug amid tough period

When one of the biggest videogame makers in the business gets hung up in the mobile end of the market, it can say something for the whole industry.

With annual revenue now over $7 billion, Electronic Arts EA -11.51% is the largest stand-alone game publisher in the U.S. save for Activision Blizzard. ATVI -0.42% EA also has a few games capable of generating more than $1 billion a year on their own, including “Apex Legends.” The battle-royale style shooter was EA’s answer to the blockbuster “Fortnite” and has been a resounding success since its surprise launch in 2019 for consoles and PCs. Analysts estimate the game’s total revenue has surpassed that of “Madden NFL” to become EA’s second-biggest property next to the blockbuster soccer franchise “FIFA,” according to Visible Alpha.

But even that is not enough to ensure success in the finicky mobile game market. EA surprised investors Tuesday with the news that it is pulling the plug on the mobile version of Apex, which has been in release for less than a year. It wasn’t a quality problem; “Apex Legends Mobile” was named Game of the Year for 2022 by both Apple and Google for their respective mobile platforms. But during a conference call to discuss the company’s fiscal third-quarter results, EA Chief Executive Andrew Wilson said that while the game resonated with many core players, failure to keep enough casual players engaged still limited the audience. “And in a game that relies a lot on team play and competitive play, liquidity of the overall player base is really, really important as you think about the future experience for players over time.”

The experience with “Apex Legends Mobile” also caused EA to kill a planned mobile version of its “Battlefield” franchise, which has been in development since at least mid-2021. And that wasn’t the only bad news in the results. EA delayed the release of the console game “Star Wars Jedi: Survivor” from mid-March to late April. Net bookings for the December quarter also came up about 6% shy of Wall Street’s forecasts, as EA’s games faced stronger competition during the crucial holiday quarter, which included a newly resurgent “Call of Duty” iteration from rival Activision Blizzard.

All told, EA cut its projected net bookings for the fiscal year ending in March by 8%, to around $7.1 billion. That implies a shortfall of about $500 million for the March period relative to the company’s prior target, much of which is owing to the “Star Wars” title delay. EA’s stock price slid 11% Wednesday morning.

Delays are now common in a videogame market where each release is expected to be merely a starting point for years of recurring revenue from live services. But EA’s struggles in mobile might prove a bigger problem over the long term. Mobile is the game industry’s largest addressable market. Apple alone said at this time last year its global installed base surpassed 1.8 billion devices. Market research firm Newzoo estimates that mobile games accounted for half the game industry’s total revenue in 2022—and was 78% larger than what console games generated for the year.

But mobile has still proven a hard market to crack—at least in a way that reliably moves the needle for a company the size of EA. The industry remains dominated by casual titles—“Candy Crush Saga” and “Clash of Clans” are still top-five grossing games more than a decade after their initial releases. And the slowing economy has hit just as mobile game makers were grappling with changes made by Apple to its iOS operating system that makes it harder to effectively market games to new players. That has hurt even well-established players. Take-Two Interactive, which acquired mobile game maker Zynga last year, cut its own forecast for the March fiscal year by 7% during its last quarterly report, citing release delays as well as the impact of the weakening economy “particularly in mobile.”

EA’s struggles also call into question the idea that popular games on PCs and consoles easily translate to mobile. That logic not only underpinned Take-Two’s acquisition of Zynga, but also is a major theme of Microsoft’s effort to buy Activision. “There’s cognitive dissonance in the desire to unite global gaming communities around core IP vs. the reality of that IP not always translating so well across platforms,” wrote Clay Griffin of MoffettNathanson in a note Wednesday morning. EA is hardly in a space to disagree.

>>> US Early premarket gappers


Early premarket gappers

  • Gapping up:
    • MESO +14.8%, OI +7.1%, GRND +6.5%, LI +6%, ATKR +6%, SRI +5%, RLYB +4.9%, AMD +4.1%, XPEV +3.8%, RIG +2.7%, SYK +2.6%, MDLZ +2.4%, TMO +2.4%, NIO +1.8%, EW +1.7%, APAM +1.7%, NMR +1.5%, DAR +1.4%, CACC +1.4%, CVLG +1.2%, LPG +0.8%, OTIS +0.8%, SBCF +0.7%, ROKU +0.6%, ODFL +0.5%
  • Gapping down:
    • TSHA -22%, SNAP -15%, EA -11.2%, MTCH -9.3%, PSTX -8%, HA -7.8%, AUY -6.6%, VREX -5.5%, PIXY -5.2%, WDC -4.5%, NVS -3.1%, ITGR -3%, UNM -3%, BMBL -2.9%, VOD -2.8%, PINS -2.5%, HLI -2.4%, WM -2.2%, BXP -2.1%, TTWO -2%, MRCY -1.8%, JNPR -1.5%, TTD -1.4%, JWN -1.4%, META -1.3%, FTI -1.2%, ASH -1.2%, PUBM -1%, GSK -0.9%, STX -0.8%, MGNI -0.7%, PAAS -0.7%

(ZH) Fed Preview: 25bps Tomorrow And Then "The End Is Very Much In Sight"

Fed Preview: 25bps Tomorrow And Then "The End Is Very Much In Sight"

Cutting to the chase, ahead of tomorrow's Fed decision (due at 2pm, Powell press conference 2:30pm, no projections so no new dots so no way to push back more on market expectations for sub-5% terminal rate), the key question - as Goldman puts it - is "what the FOMC will signal about further hikes this year" since 25bps tomorrow is in the bag and what matters to stocks is i) will this be the final rate hike and ii) how long will the Fed keep rates here before starting to cut.
"The Fed is approaching a critical inflection point and whether they finish with 25bp tomorrow (at 4.75%) or 25bp on 3/22 (at 5%), the end is very much in sight (but what really matters is how long they hold this level which i am betting will be much longer than most currently expect)." - Goldman trader John Flood
As Goldman further discusses in its FOMC preview (excerpted below, full note available to pro subs), "we expect two additional 25bp hikes in March and May, but fewer might be needed if weak business confidence depresses hiring and investment, or more might be needed if the economy reaccelerates as the impact of past policy tightening fades. Fed officials appear to also expect about two more hikes and will likely tone down the reference to “ongoing” hikes being appropriate in the FOMC statement."
Some more big picture observations from Goldman's David Mericle:
The FOMC’s goal for the year is clear. It aims to continue in 2023 what it began so successfully in 2022 by staying on a below-potential growth path in order to rebalance the labor market so that inflation will return to 2% sustainably. We agree with Fed officials that there is still a long way to go—after all, our jobs-workers gap is still about 3 million above its pre-pandemic level.
How many hikes will be needed to stay on this path is less clear. We expect two additional 25bp hikes in March and May, but fewer might be needed if weak business confidence depresses hiring and investment, or more might be needed if the economy reaccelerates as the impact of past policy tightening fades. Fed officials appear to also expect about two more hikes and will likely tone down the reference to “ongoing” hikes being appropriate in the FOMC statement.
FWIW, the market gives just 2% odds of a 50bps hike tomorrow (i.e., 25bps tomorrow), and just 26% odds that there will be more than one more hike by May (i.e. another 25bps in March), at which point the Fed will be done and is then expected to start cutting as much as 50bps in the second half of 2023, and more in 2024. It is here that one should expect the most pushback from Powell tomorrow if indeed, as consensus overwhelmingly expects, the Fed Chair will be extra hawkish during his press conference.
But why just 25bps tomorrow? After all, if the Fed really wanted to punish stonks - as he clearly did at Jackson Hole with has hastily rewritten 8 minute speech, why not just do 50bps and crush risk? Here Goldman has an explanation too:
Since the FOMC last met in December, two trends in the economic data have made the case for slowing the pace of rate hikes to 25bp next week surprisingly easy.
  • First, incoming data on wage growth and inflation have been encouraging, including a deceleration in average hourly earnings and the Atlanta Fed wage growth tracker, another round of soft inflation data, a continued collapse in alternative leading indicators of rent inflation, and a further decline in one-year Michigan consumer inflation expectations, which have now fallen 1.5pp since the Fed started hiking.
  • Second, signals on activity growth have become more mixed and at times concerning. A large gap has opened up between GDP and our current activity indicator (CAI), and between the “hard data” components of our CAI and the “soft data” components like surveys. We suspect that nominal bias and negative sentiment driven by recession fears are depressing the survey data, similar to the pattern seen during the 2019 trade war, and that activity growth actually remains modest but positive. But uncertainty about the near-term outlook has risen.
While tomorrow's 25bps may be a done deal, where the Fed will clash with the market is how many more hikes are on the way. As noted above, the market now expects at most 1 more 25bps rate increase before May. However, the Fed December dots indicated that the median FOMC participant expects two additional 25bp hikes after tomorrow's rate hike. As a result, Goldman - if not the market - expects the FOMC will probably tone down the reference to “ongoing” hikes being appropriate in the FOMC statement, perhaps by replacing “ongoing” with “further.
There is more in the full Goldman note available to professional subs.
One more point from Goldman economist Zach Pandl, and this has to do with today's Employment Cost Index, which came in softer than expected, and which sparked today's frenzied rally as it hinted potential dovishness from Powell tomorrow, to wit:
Zach Pandl on ECI: “Clear deceleration in ECI; even larger downshift than in average hourly earnings growth during the quarter; very big drop in one of the underlying series that people focus on (wages ex-incentive paid occupations); more good news for soft landing camp/team transitory; on the margin I would think this raises odds of more dovish message from Powell tomorrow, although employment report on Friday will still have a lot to say about their overall read of labor market.”
Away from GS, here is what JPM thinks, starting with today's powerful rally following the weaker than expected ECI, and culminating with a warning that even a hint that Powell may not keep rates at 5% through year-end "could be enough to lead to a market rally. "
Stocks rallied as Employment Cost Index came in cooler than expected this morning, which provides more comfort on slowing wage inflation. While expectations on Fed’s terminal rates remains stable, equities and bonds are rallied on optimism around a Fed pause in May and potentially rate cuts in 2023. Despite recent Fedspeaks all supports holding terminal rate at 5% for the entire year, the OIS market currently expects the FFR to be around 4.5% by YE, implying a 50bp cut in 2H23. Will tomorrow’s meeting reshape this expectation? Feroli expects Powell’s speech to remain hawkish to push back against the easing financial conditions, but given this consensus view, any pivot from the view of holding FFR at 5% till YE could be enough to lead to a market rally.
As usual, much more from JPM - and other Wall Street firms - to pro subs in the usual place.
JPM is not the only one listening closely to what Powell will say: Jeff Gundlach just tweeted that he expects the Fed to "push back against the pivot narrative and thereby current bond market pricing." Which of course they will: the question is all about the nuances.
Finally, here is a quick and dirty FOMC preview snapshot from our friends at Newsquawk:
  • OVERVIEW: The analyst consensus sees the FOMC lifting its Federal Funds Rate target by 25bps to 4.50-4.75%, with a small minority noting the potential for a larger 50bps hike increment. Money markets are pricing the smaller move with almost certainty, but further through the year, are underpricing the December SEP-implied terminal rate of 5.1% and are even pricing risks of Fed easing at the back half of 2023. Chair Powell is likely to stay the course around the fight against inflation not being over and the "higher for longer" policy stance, guiding to more hikes in the future despite the latest encouraging disinflationary data, but it's seen as unlikely that any efforts to jawbone tighter financial conditions will be successful barring a change in the data, with markets themselves in data-dependency mode. Meanwhile, Powell may provide the Fed more optionality to cater for a 'soft landing' by leaning into recent Fed Speak regarding the potential for disinflation absent a meaningful rise in unemployment.
  • STATEMENT: The Fed is priced with almost certainty for a 25bps hike to take the FFR to 4.50-4.75%, with a less than 5% chance of a 50bps hike implied by money market pricing. The statement is expected to be updated to reflect the deceleration in the hiking pace and acknowledge the cumulative tightening already in place. With speculation building over whether the Fed will follow through with its guided rate hike path to 5.00-5.25%, it's worth keeping an eye out for any adjustments to its line that "ongoing increases in the target range will be appropriate", albeit it's probably a bit premature.
  • POWELL: The Fed Chair is likely to reaffirm the party line of more work needing to be done on inflation. He likely highlights the promising string of declines in the inflation data, but also warns that it is still far above the 2% target, whilst expressing concerns over the stubbornly high services inflation. Perhaps more interestingly will be if Powell warms further towards the possibility of falling inflation without the need to cool the labour market. Members of the Board, from dove Brainard to hawk Waller, have recently alluded to the possibility of such. So, if Powell looks to cement that line of thinking, that the Fed doesn't require rising unemployment to bring inflation back down, recession risks/pricing are likely to reduce greatly, something that could be a driving factor in the recent pick-up in stock appetite given the data lately has evolved in favour of a 'soft landing'.
  • DATA: Core PCE Y/Y has now declined for three consecutive months, sitting at 4.4% in December, and down from cycle peaks of 5.4% in February 2022, building belief that the peak may be in. A lot of that decline has been spurred by falling goods prices, asking the continued strength in the services sector, particularly core services ex-housing, which many Fed officials keep pointing to as an area that needs to be addressed. That decline has also come against the backdrop of initial jobless claims reaching 9-month lows and limited progress in JOLTS job openings falling to support a loosening in the labour market, but at the same time, wage growth data has shown some signs of cooling, with Tuesday's Employment Cost Index for Q4 a key focus after the promising wage data in the BLS employment report. Meanwhile, fears over an imminent recession have abated, with US GDP rising again in Q4 (+2.9%), and despite the dip in November and December real personal consumption, as well as December retail sales, real-time credit card data has picked up again into January and earnings commentary has been sanguine on the consumer.

Epoch Health : Ivermectin: Could Population-Wide Distribution Have Prevented Chi

Ivermectin: Could Population-Wide Distribution Have Prevented China’s Recent Mass COVID Outbreak?

China’s state-run medicare program recently failed to reach an agreement with Pfizer to import more Paxlovid, claiming the COVID-19 treatment drug is too expensive. This is despite the drug being offered to the state at a reduced rate in comparison with that offered to other developed countries. Lack of Paxlovid will leave only Azvudine, an anti-HIV drug the Chinese communist regime rushed through development and re-branded as an anti-COVID drug, as a treatment option.
Given the recent explosive spread of COVID and the resulting skyrocketing rates of hospitalization, finding viable treatment options is paramount.
Ivermectin in India and Peru
When the Delta variant broke out in 2021 across India, many states offered ivermectin population-wide. The efficacy of ivermectin in treating early and mild COVID-19 infections was confirmed in large states such as Uttar Pradesh—home to 241 million residents—where the use of the prophylactic dramatically reduced both the infection rate and the death toll.
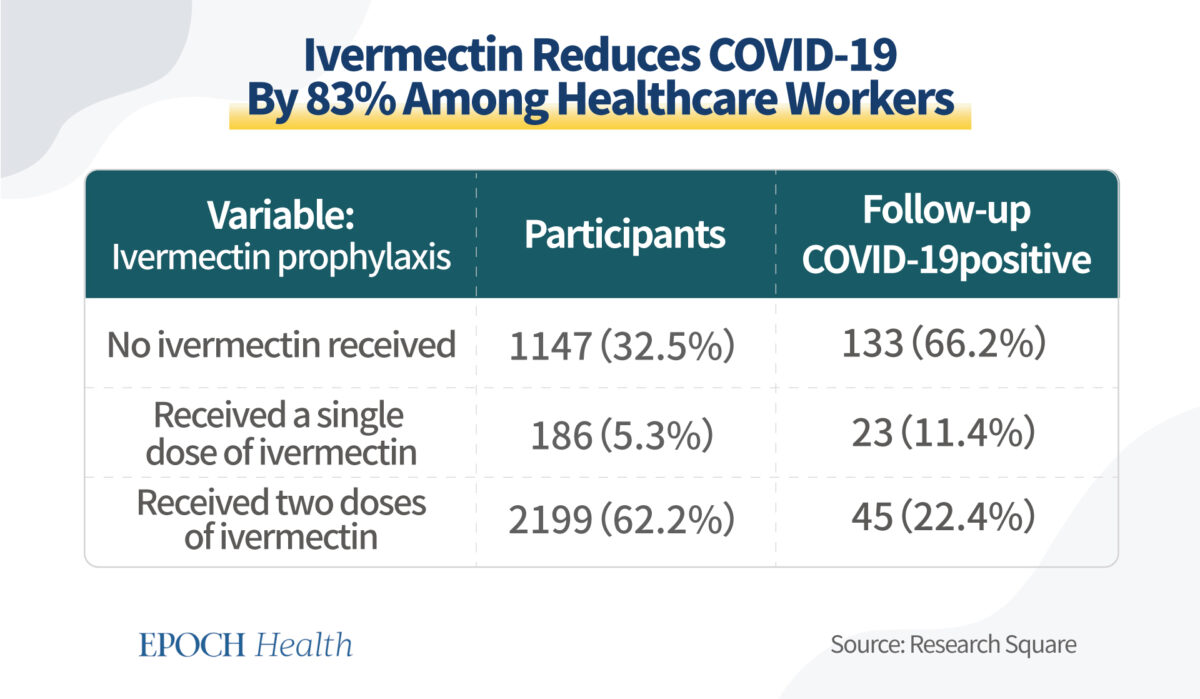
Data from a study comparing the efficacy of ivermectin in frontline health care workers. (The Epoch Times)
Even among frontline health care workers, ivermectin proved to be an effective prophylactic against COVID-19. One study with 3,532 frontline health care workers from the All India Institute of Medical Sciences Bhubaneswar found that two doses of oral ivermectin (300 μg/kg given 72 hours apart) as chemoprophylaxis among health care workers reduced the risk of COVID-19 infection by 83 percent in the following month.
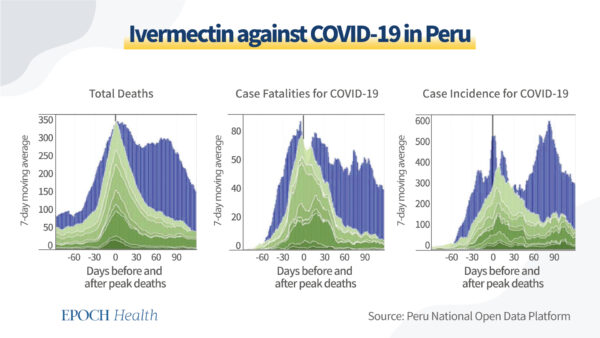
In Peru, mass ivermectin treatments were conducted through a broad-scale effort called Mega-Operación Tayta, or MOT for short. Operation MOT was led by the Peruvian army and involved 10 states, where the excess death rate saw a sharp decline with an average of 74 percent over 30 days. In 14 states where ivermectin was administered locally, the mean reduction in excess deaths over 30 days compared with deaths was 53 percent.
Lima, the capital of Peru, where the distribution of ivermectin was restricted, saw only a 25 percent reduction in excess deaths. The findings of researchers, detailed in the diagram below, show infection numbers, deaths, and fatalities across Peruvian states which implemented ivermectin (blue) and those which did not (red). The conclusion is that a reduction in deaths correlated with the distribution of ivermectin with a statistically significant p-value of less than 0.002.
COVID-19 data from Peru’s 2021 Delta outbreak comparing states that dispensed ivermectin (green) and those that did not (blue). (The Epoch Times)
Ivermectin–The Wonder Drug
Ivermectin was discovered in Japan during the late 70s as a derivative of Avermectin, produced from a single organism isolated at the Kitasato Institute in Tokyo. Since then, ivermectin has played an immeasurable role in improving the lives of billions with its humble beginnings as an anti-parasitic drug.
Ivermectin, approved by the U.S. Food and Drug Administration and deployed worldwide since 1987, has made major inroads against two devastating tropical diseases—onchocerciasis and lymphatic filariasis. In addition, some topical forms of ivermectin are approved to treat external parasites like head lice and skin conditions such as rosacea.
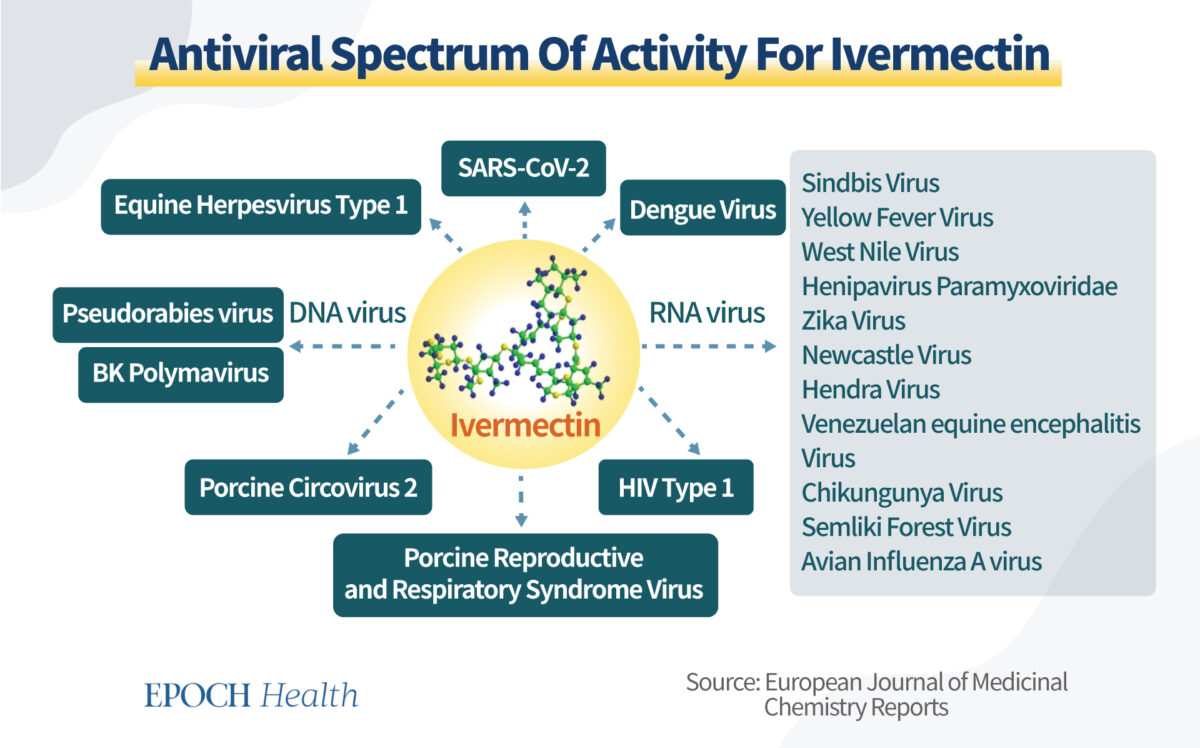
Ivermectin is potentially effective against a host of viruses. (The Epoch Times)
In addition to its anti-parasitic effects, a 2022 study published in the European Journal of Medicinal Chemistry Reports found that ivermectin has a strong potency at low concentrations against many DNA and RNA viruses, including HIV-1, yellow fever, malaria, West Nile virus, Zika, dengue fever, etc.
According to the study, ivermectin has an amazing inhibitory effect across multiple species and can interrupt motility and reproduction in both arthropods (such as insects) and nematodes (such as roundworms). This explains why ivermectin is prescribed for parasite infections, and also sheds light on its potential as a prophylactic against vector-borne diseases. In insects and other arthropods specifically, it can interrupt the transmission of disease.
Ivermectin’s Potential Mechanisms Against COVID
SARS-CoV-2 is a virus that takes over host cells to multiply in the body. To enter the host cells, the virus binds to the ACE-2 receptor on the surface of cells which grants them entry. Ivermectin prevents the bonding process by interfering with the virus’s spike proteins—this is the same mechanism the vaccines use.
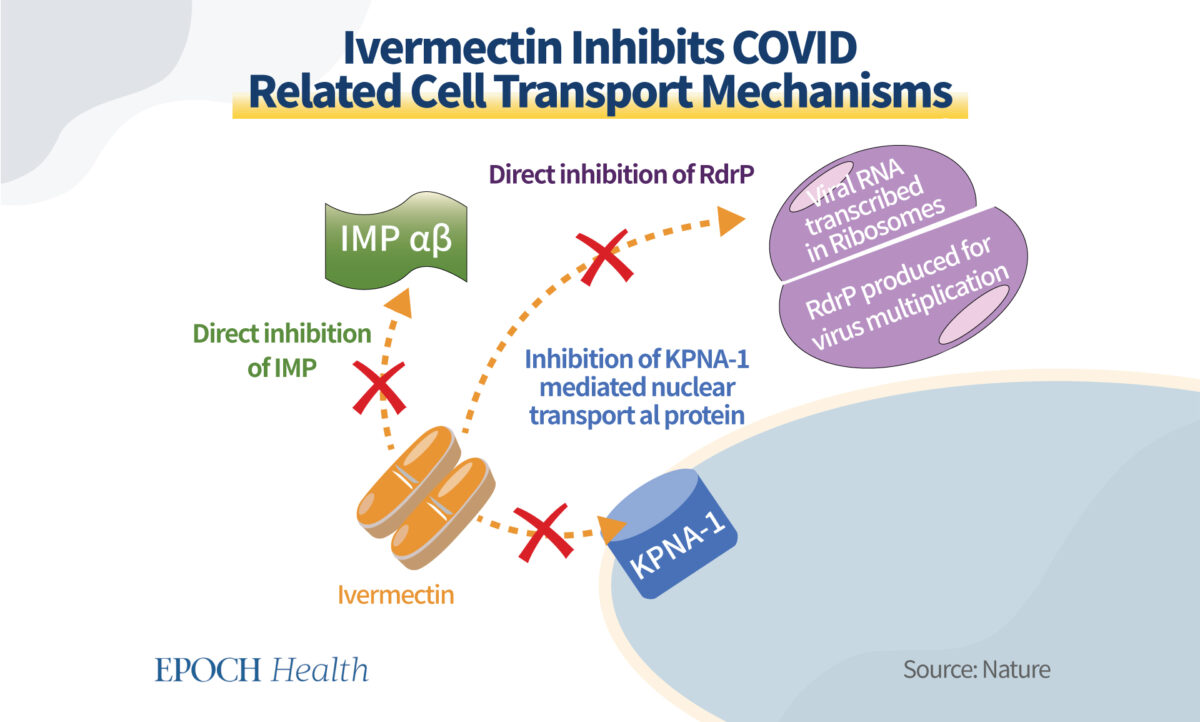
If the virus slips past the cell membrane, its top priority is to infiltrate the brain of the cell—the DNA-containing nucleus—to start mass-producing itself. SARS-CoV-2 latches itself onto a special class of transport proteins called IMPs that have enough security clearance to enter the nucleus. In the case of a viral infection, ivermectin binds to these transport proteins and halts the interaction.
Ivermectin inhibiting intracellular transport and viral production. (The Epoch Times)
Ivermectin also inhibits the nuclear transport mechanism mediated by the KPNA-1 protein, which has a similar effect when compared with IMPs. Both proteins can enter the nucleus and ivermectin can effectively stop the virus from getting to the nucleus. In the event that the virus does manage to invade the nucleus—ivermectin also has a backup plan.
For example, when the virus has taken over and initialized self-replication, it does so through a protein called RdRp, which is at the centerpiece of viral replication—and is directly inhibited by ivermectin with very high efficacy.
Ivermectin Could Reduce Severe Lung Damage in COVID Patients
Once COVID-19 reaches later stages, it may require intensive care for recovery. For example, white lung syndrome (a hallmark symptom of acute respiratory distress syndrome) now occurring in severe COVID infections in China, is a sign that the virus has deeply infected the lungs and may have caused cytokine storms (a severe immune reaction in the body) in patients.
Other complications that arise from COVID-19 involving the lungs are conditions such as pulmonary fibrosis and hypoxia. Hypoxia occurs when the virus infects lung tissue to the extent that the alveoli, tiny sacs of air at the end of lung branches responsible for oxygen exchange, become scarred causing a severe loss of oxygen in the body.
Cytokines and chemokines are responsible for inflammation, a natural immune system response to foreign invaders. However, a large number of cytokines released into the body all at once can cause a “cytokine storm,” wherein the body is flooded with armies of white blood cells that harm the body.
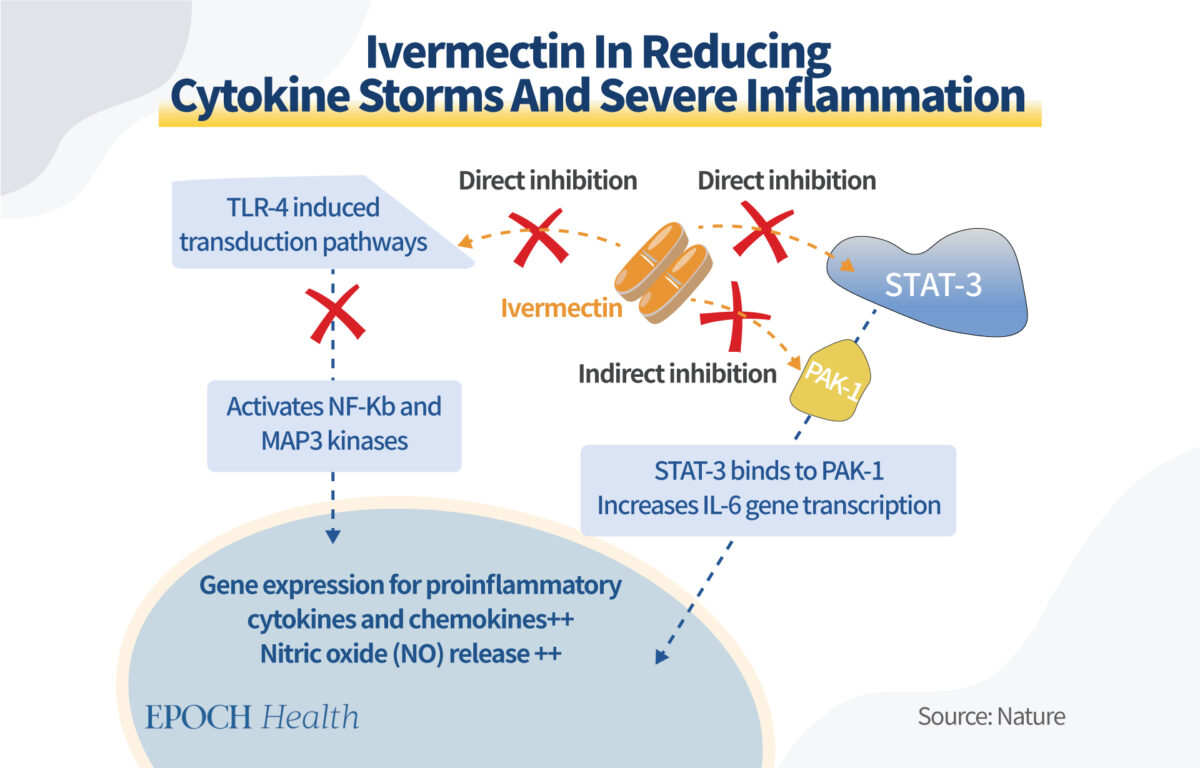
A cytokine storm can be triggered through the TLR-4 pathway by the virus. The same pathway also triggers the release of nitric oxide, causing fluid leaks, dilating blood vessels, or even sepsis and fluid buildup in the lungs.
Ivermectin’s intracellular mechanisms in reducing severe inflammation. (The Epoch Times)
A cytokine storm is related to the viral components that change how the body regulates certain signal molecules like STAT-3 and TLR-4. Too much STAT-3 will lead to the production of more TLR-4 through PAK-1 and is how the virus induces a pathway such that a heavy inflammatory response is initiated in the body.
Ivermectin directly inhibits the NF-kb and STAT-3 pathways by degrading the signal molecules that promote the vicious cycle. Thereby, Ivermectin can reduce the chance of cytokine storms and reduce the risk of patients having severe lung damage such as “white lungs.”
Ivermectin Can Reduce Bacterial Co-Infections for COVID Patients
Bacterial coinfections are common in respiratory viral infections, and patients with COVID-19 are no exception. Patients with co-infections were more likely to die in intensive care than those without coinfections. Among the group of compounds in the avermectin family, ivermectin stands out for its antibacterial effects.
In clinical isolates of multidrug-resistant tuberculosis, the use of ivermectin has been proven effective. At the same time, ivermectin inhibits the growth of a flurry of other bacteria such as Staphylococcus aureus (heavy skin infection), Mycobacterium Bovis, and others at clinically significant concentrations ranging from 1-8 µg/ml, signifying a strong potency.
Ivermectin can also activate P2X4 receptors in macrophages, increasing its ability to destroy bacteria and protect against sepsis, which is the most prominent antibacterial effect of ivermectin.
Repurposing drugs, if successful, is the best accelerator for prophylactic development because it can save developers anywhere from three to 12 years as experts can reuse the data from previous clinical trials and other experiments.
A “wonder drug” like ivermectin should be strongly considered as a defense against viruses given its success both in mechanism studies and clinical trials as well as applications in a variety of diseases and infections. The suppression of ivermectin usage during the COVID-19 pandemic by government agencies and Big Pharma is one of the world’s most tragic events in modern medicine.
Particularly sad was when the Chinese regime did not fulfill its social responsibilities when loosening the zero-COVID restrictions by offering prophylactics such as ivermectin to prepare its people for a tsunami of infections—as Peru did with their ivermectin distribution operation. It would have been greatly beneficial to equip the Chinese people with ivermectin to reduce the exorbitant infection numbers and needless deaths of COVID-19.

WSJ : FBI Searched Biden’s Former Think-Tank Office in November

FBI Searched Biden’s Former Think-Tank Office in November
Search for classified documents was undertaken after agreement with White House

WASHINGTON—The Federal Bureau of Investigation searched President Biden’s former office at a Washington think tank for classified documents in November, people familiar with the matter said, shortly after his aides earlier that month found such material and surrendered it to the National Archives.

The search came after Mr. Biden’s lawyers agreed to let agents search his former office at the Penn Biden Center for Diplomacy and Global Engagement, where aides on Nov. 2 discovered roughly a dozen documents marked classified. It couldn’t be determined whether investigators found any additional items in the search, which was reported earlier by CBS News.

Revelations that classified material was found in the office as well as his home in Wilmington, Del., have raised concerns about Mr. Biden’s handling of the nation’s secrets and put the White House on the defensive over the manner in which it disclosed to the public the scope of the mishandled documents.

Neither the White House nor the Justice Department mentioned the November office search even as officials offered timelines of the discoveries and Attorney General Merrick Garland appointed a special counsel to examine why and how the documents followed Mr. Biden. Mr. Garland said the FBI on Nov. 9 began assessing whether classified material had been mishandled in violation of federal law.

A Justice Department spokesman declined to comment. A spokesman for the White House Counsel’s Office didn’t immediately respond to requests for comment.

Ron Ozio, a spokesman for the University of Pennsylvania, referred questions about the search to the Justice Department.

After the initial discovery at the Washington think tank, the Justice Department considered having FBI agents monitor the Biden legal team’s search for additional classified documents at the president’s homes, but decided against it, The Wall Street Journal previously reported.

After Mr. Biden’s team found additional documents in his garage, and turned them over to law enforcement, FBI agents searched the Wilmington home on Jan. 20, taking six additional items with classified markings and some related materials. Mr. Biden’s lawyers said they gave the FBI full access to the property ahead of the search, which lasted 12 hours.

The special counsel, Robert Hur, resigned from Gibson, Dunn & Crutcher LLP on Tuesday and is expected to be sworn in on Wednesday, people familiar with the appointment said.

Meanwhile, the general counsel of the National Archives and Records Administration sat Tuesday afternoon for a transcribed interview with the GOP-led House Oversight and Accountability Committee. That panel, which has jurisdiction over NARA, has been conducting a broad probe into the document discoveries, requesting information from the Archives, the White House, the Secret Service and the Penn Biden Center.

Lawmakers from both parties have been frustrated that the intelligence community hasn’t turned over or provided a detailed briefing on the classified documents found among Mr. Biden’s personal possessions, or another set of documents found in former President Donald Trump’s possession. Senate Minority Leader Mitch McConnell (R., Ky.) on Tuesday backed a request from Intelligence Committee Chairman Mark Warner (D., Va.) and the panel’s top Republican, Sen. Marco Rubio (R., Fla.), for details about the classified documents found among Mr. Biden’s personal possessions.

“What they’re asking for here would not interfere with these ongoing criminal investigations. And I hope the administration will come up with a better answer than no, which is apparently what both the chairman and the vice chairman were told recently,” Mr. McConnell said. “Their request to find out exactly what kind of documents were in improper custody seems to me squarely within their oversight mission on the Intel Committee.”

The Biden document saga has drawn comparisons to the efforts by the National Archives and the Justice Department to retrieve classified and other documents from Mr. Trump’s Florida residence, which escalated over more than a year to include a criminal investigation into possible obstruction, and a warrant-backed search of the resort in August. Mr. Trump has called the probe a witch hunt and denied wrongdoing.

Last week, lawyers for former Vice President Mike Pence revealed that he, too, had discovered classified material at his home in Indiana, adding that he took the documents by mistake and was unaware he had them.