>>> Europe : Brokers Upgrades & Downgrades - 26th of May 2023

>>> Up
* Avance Gas Raised to Buy at Pareto Securities; PT 92 kroner
* Faurecia Raised to Buy at Jefferies; PT 24 euros
* NN Group Raised to Buy at HSBC; PT 45 euros
* Nvidia Raised to Buy at First Shanghai; PT $400
* Rio Tinto Raised to Overweight at Morgan Stanley; PT 5,800 pence
* Sabre Insurance Raised to Buy at Berenberg; PT 153 pence
* SGL Raised to Add at AlphaValue/Baader
* Schoeller-Bleckmann Raised to Buy at Berenberg; PT 66 euros
* Tele2 Raised to Buy at Citi; PT 115 kronor
* Telia Raised to Neutral at Citi
* Valeo Raised to Buy at Jefferies; PT 22 euros

>>> Down
* Apple Cut to Hold at First Shanghai; PT $190
* Atlantica Sustainable Cut to Sector Perform at National Bank
* Elisa Cut to Sell at Citi
* Halfords Cut to Sector Perform at RBC; PT 220 pence
* K+S Cut to Add at Baader Helvea; PT 18 euros
* Linde Cut to Underperform at Oddo BHF; PT $339
* Salmar Cut to Hold at DNB Markets; PT 565 kroner
* Suedzucker Cut to Underperform at Oddo BHF; PT 16 euros

>>> Initiation
* BBVA Reinstated Equal-Weight at Barclays; PT 8.80 euros
* CaixaBank Reinstated Overweight at Barclays; PT 5 euros
* FD Technologies Rated New Overweight at JPMorgan; PT 2,500 pence
* HydrogenOne Capital Growth Rated New Overweight at Barclays
* Oxford Instruments Rated New Hold at HSBC; PT 2,900 pence
* Sabadell Reinstated Equal-Weight at Barclays; PT 1.20 euros
* Telenor Resumed Neutral at Citi; PT 121 kroner
* Uber Rated New Strong Buy at President Capital Management

>>> Call
* CITI STRATEGISTS LIFT US EQUITIES TO NEUTRAL FROM UNDERWEIGHT
* CITI STRATEGISTS CUT CHINA OVERWEIGHT, GO UNDERWEIGHT EU STOCKS
* Faurecia Double-Upgraded, Valeo Raised to Buy at Jefferies
* Halfords Cut to Sector Perform at RBC With Stock Fairly Valued
* Ryanair Now a Top Pick at Morgan Stanley on Cash Generation
* Tele2 Top Pick in Nordic Telcos at Citi, Telia Raised, Elisa Cut

>>> What to look at today - 26th of May 2023

A gauge of Asian shares was on course to snap a three-day losing streak, buoyed by the tech sector, while US equity futures slipped after artificial intelligence stocks fueled a sharp rally in the prior session.  Benchmark indexes rose in Japan, South Korea, India and Australia, while those for mainland China fell. Hong Kong’s market was closed Friday for a public holiday.  It was the second day of gains for chip stocks in the region following a bullish sales forecast from Nvidia Corp. late Wednesday that ignited a frenzy of interest in AI. Among notable moves in Asia, Japan’s Screen Holdings Co. surged as much as 9%, South Korea’s SK Hynix Inc. jumped 5.5% and Taiwan Semiconductor Manufacturing Co. advanced 4.6%. The AI rally continued after hours in the US, when Marvell Technology Inc. projected 2024 revenue from the technology will at least double from a year ago. Earlier, shares of Nvidia soared 24%, propelling the company to the cusp of a $1 trillion market value.  Yields on treasury-bills slated to mature early next month were off recent highs while still showing that investors demand a premium on securities seen most at risk of non-payment if the government exhausts its borrowing capacity.   The yen strengthened slightly versus the greenback while remaining near 140 level. The Japanese currency has depreciated amid bets that the Federal Reserve will hike rates within the next two policy meetings while its counterpart in Tokyo sticks with ultra-loose policy. Data Friday indicated slowing inflation in Tokyo, which supports expectations for continued divergence between the Bank of Japan and the Fed. This keeps a lid on the yen and in turn helps Japanese stocks. The debt-ceiling wrangling in Washington adds to the risks assessed by Fed officials as they consider pausing interest rate increases. Wagers for another quarter-point hike within the next two policy meetings came amid mixed data on Thursday, including a higher revised first-quarter GDP and fewer-than-expected jobless claims.  oil was steady after falling more than 3% on Thursday as Russia suggested OPEC+ wasn’t likely to change production levels at its next meeting.  Copper and iron ore have both breached key levels this week, pulling down the Bloomberg Commodity Index. US After Hours MRVL +17.8%, GPS +14.4%, WDAY +7.9% higher on earnings; ULTA -7.3%, DECK -2.7%, RH -2.2%, COST -0.2% lower on earnings.

Nikkei +0.64% Hang Seng -1.93% CSI +0.11% Shanghai +0.46% Shenzen +0.31%

Eur$ 1.0738 CNH 7.0707 CNY 7.0592 JPY 139.74 GBP 1.2334 CHF 0.9046 RUB 80.1219 TRY 19.9953 WTI$ 71.74 -0.13% Gold 1,948.33 +0.36% BTC 26,422 -0.25% ETH 1,807 -0.14%

S&P -0.13% Nasdaq -0.09% EuroStoxx +0.14% FTSE +0.05% Dax +0.06% SMI +0.11%

Macro :
- CITI STRATEGISTS CUT CHINA OVERWEIGHT, GO UNDERWEIGHT EU STOCKS
- CITI STRATEGISTS LIFT US EQUITIES TO NEUTRAL FROM UNDERWEIGHT
- UK Regulator Probes Sustainable Loans Market: FT
- Equal-Weighted Index Is Not a Harbinger of Doom for US Stocks
- Britain Loses its Luster for Job Seekers From Poland to Portugal
- Iron Ore Can Go Lower

Keep an eye on :
- ALTR PL : Altri 1Q Net Income EU19.6M Vs. EU29.8M Y/y
- ASC LN : Asos to Conduct Equity Raise of £75m Placing, £5m Retail Offer
- ATO FP : Atos Gets Cash Cushion for Spin in Cognizant Damages Trim: React
- BG US : Glencore’s Viterra Said in Merger Talks With Grain Rival Bunge
- BWLPG NO : BW LPG CFO Elaine Ong Steps Down
- CO FP : Casino Says Paris Court to Open Conciliation Proceedings
- CO FP : Les Mousquetaires to Take €100M Equity Stake in Casino
- COFA FP : Coface 1Q Net Income EU61.2M Vs. EU52.3M Y/y
- OLE SM : CVC Taps Lazard to Seek Investor for Olive Firm Deoleo: Cinco
- DTE GY : Deutsche Telekom Exposed If Dish's Amazon Plan Goes Ahead: React
- EQNR NO : Statfjord A Production Shut After Gas Alarm Triggered, BT Says
- ERICB SS : Record $279 Million Whistleblower Award Went to a Tipster on Ericsson -- WSJ
- Florence Group : Permira Buys Majority Stake in Florence Group
- GLEN LN : Glencore’s Viterra Said in Merger Talks With Grain Rival Bunge
- INPST NA : Advent International to Sell 15% Stake in InPost to PPF Group
- ISN SW : Intershop Group CFO Thomas Kaul to Leave Company in 1H of 2024
- LHA GY : Italy Agrees to Sell ITA Airways Stake to Lufthansa
- ORP FP : Orpea Sells Latvia Operations to Adoro SIA; No Terms
- PSM GY : ProSieben 1Q Adj. Ebitda Misses Estimates, FY Outlook Confirmed
- SFQ GY : SAF-Holland SE Maintains FY Sales Forecast
- SAN FP : Sanofi Board Names Frederic Oudea as Chairman After AGM
- SAN SM : Smartfit Says Banco Santander Brazil Joins Banks in Patria Offer
- TSLA US : Tesla Probed in Europe for Suspected Data Lapse: Handelsblatt
- TLRY US : Tilray Brands Prices $150m of Unsecured Convertible Notes -17%
- UQA AV : Uniqa 1Q Gross Written Premiums EU1.98B Vs. EU1.86B Y/y
- DG FP : Avoiding Water Scarcity Creates Long-Term Investment Opportunity

TechCrunch : Elon Musk says Tesla might ‘open source more code’ to other automak

Elon Musk says Tesla might ‘open source more code’ to other automakers

Elon Musk suggested Thursday during a Twitter Spaces with Ford CEO Jim Farley that Tesla might open up some of its automotive operating system code to other automakers.

“In the same way that maybe Android is helpful to the phone industry as sort of a general standard, like we could potentially open source more code,” said Musk. If Tesla takes that leap it will compete with Google, which has developed an automotive operating system based on Android, as well as Apple.

Musk was responding to Farley’s note that making a “fully software updatable vehicle” is “super hard.” The billionaire executive said Tesla would be happy to “be helpful on the software front.”

Musk made the comment during a Twitter Spaces that was used to announce a milestone agreement between Tesla and Ford. Under the deal announced Thursday, Ford’s EV customers will get access to the Tesla Supercharging network in the U.S. and Canada. More importantly, Ford agreed to incorporate Tesla’s charging port into its second-generation of EVs, which includes a truck and three-row SUV, starting in 2025.

Musk often spitballs ideas for Tesla at live events, some of which come to fruition and some of which don’t. If Tesla were to try to commercialize its over-the-air updatable software to other vehicles, it would put the automaker in direct competition with Google and Apple.

Google offers automakers Android Automotive OS, which is modeled after its open source mobile operating system that runs on Linux and is modified for use in cars. Apple also jumped into the OS game last June when it announced that its next-gen CarPlay aims to power a vehicle’s entire instrument cluster. Both tech companies also offer a middleware product called Apple CarPlay and Android Auto that connects a user’s phone to a car’s infotainment system.

Supply chain partnerships
Musk and Farley also hinted Thursday at other potential partnerships in the future, including in the supply chain.

The Ford CEO questioned Musk about Tesla’s new Corpus Christi lithium refining plant. Ford recently struck a series of deals, including with Albemarle and SQM, to ensure the automaker’s access to lithium.

Musk repeated previous woes that there are not enough entrepreneurs in the U.S. digging into raw materials mining and processing, and that he wishes Tesla didn’t have to pick up the slack. He said the company has a nickel-based cathode refinery in Austin, and might also have to get involved in anode manufacturing, but “hopefully not.”

Musk noted that there’s going to be a huge market for synthetic graphite (graphite is the main material in most lithium-ion anodes).

The two CEOs have remained friendly at times despite competing against each other. Musk has praised the automaker in the past, noting on several occasions that only Tesla and Ford have avoided bankruptcy.

Ford, like other legacy automakers, is still aiming to unseat Tesla as the No. 1 seller of EVs in the United States. Ford has a ways to go.

In 2022, Ford sold 61,575 electric vehicles in the U.S. Tesla sold 1.3 million EVs globally. The company doesn’t break out sales by country. Over the past two years, Ford said it lost about $3 billion on its EV and digital services business, a unit now known as Model e. The company doesn’t expect Model e to be profitable until late 2026 with an 8% operating profit margin. Ford’s traditional gas-powered engine units were profitable enough to offset those losses, though.

In terms of production, Ford aims to reach 600,000 EV units by the end of 2023 and 2 million by the end of 2026.

Tesla said it wants to hit a 50% compound annual growth rate in 2023 that should see the automaker produce 1.8 million cars

TechCrunch : Electric truck maker Nikola at risk of being delisted from Nasdaq

Electric truck maker Nikola at risk of being delisted from Nasdaq

Nikola, the beleaguered electric truck developer, is at risk of being delisted from Nasdaq, the company disclosed Thursday in a regulatory filing.

Nikola said that on May 24 it received a delisting notice from the public exchange because its share price has been below $1 for the past 30 days. The company has until November 20 to comply with Nasdaq’s minimum price rule, which requires the share price to be above $1 for 10 consecutive business days.

Nikola shares were as high as $65.90 in 2020 when the buzzy SPAC was being led by Trevor Milton, the company’s co-founder and former CEO, who has been indicted on federal securities fraud. Shares have since fallen 20% to $0.62.

Nikola is among a growing number of companies that went public via a merger with a special purpose acquisition company to see its market cap go into a free fall, and in some cases, land in delisting limbo. Lordstown Motors said this month it also received a delisting notice. The notice, and its failing deal with Foxconn, prompted Lordstown to issue a reverse stock split. Many of these mobility companies were attracted to the capital that public markets can access. And the use of the SPAC as a financial instrument seemed to work at first with many becoming buzzy meme stocks in 2021.

Now the fundamentals are catching up to companies like Nikola as well as other SPACs like Arrival, Bird and Canoo.

Nikola has been working to raise more money by issuing more shares. It is urging shareholders to vote for a proposal that would allow it to increase the number of shares of its company’s common stock. The passage of this proposal requires more than 50% of its outstanding shares to vote favorably.

(ZH) Who Made The Most US Unicorn Acquisitions Since 1997?

Who Made The Most US Unicorn Acquisitions Since 1997?
The elusive unicorn is no longer a myth in the U.S. startup world, with over a thousand private startups reaching a $1 billion valuation in the last 25 years.

While some of these startups eventually go public and go on to become household names, it’s also common for founders to exit through mergers and acquisitions (M&A), by selling their startup to another organization. In fact, over half of the 1,110 unicorns in the U.S. have made some sort of an exit—either through an IPO, a direct listing, a SPAC or an acquisition—since 1997.

Ilya Strebulaev, professor of finance and private equity at the Stanford Graduate School of Business, brings us this visualization featuring the companies that acquired the most unicorns over the last 25 years.

Strebulaev’s database lists 137 private and public companies along with PE firms who’ve acquired at least one unicorn since 1997, totaling 177 acquisitions.

The Biggest U.S. Unicorn Acquirers
In total, 27 companies have acquired two or more unicorns, accounting for nearly 38% of all acquisitions. 110 companies have acquired just one unicorn.
Company/ PE Group Acquired
Meta 5
Cisco 4
Alphabet 4
Amazon 3
Nortel Networks 3
Bristol-Myers Squibb 3
Johnson & Johnson 3
Merck & Co. 3
AT&T 3
Recruit Holdings 2
IBM 2
Microsoft 2
Thoma Bravo 2
Headspace Health 2
Allergan 2
Qualcomm 2
Rakuten 2
Adobe Systems 2
Eli Lilly 2
Vista Equity 2
Dell 2
Uber 2
Oracle 2
Nestle 2
Lucent Technologies 2
Broadcom Corporation 2
GlaxoSmithKline 2
BlackBerry 2
Searchlight Capital Partners 1
Singtel 1
Vmware 1
Internet Capital Group 1
Hellman & Friedman 1
AppLovin 1
Ciena Corporation 1
Redback Networks 1
Aether Systems 1
Fresenius Medical Care 1
Electronic Arts 1
Genentech 1
Inktomi 1
VistaJet 1
Ariba 1
Keurig Dr Pepper 1
Fullscreen 1
Sycamore Networks 1
Novartis 1
TP ICAP 1
eBay 1
DoveBid 1
McKesson 1
IG Group 1
Empower Retirement 1
Dentsply Sirona 1
Novo Nordisk 1
Centocor 1
Bausch Health 1
Dainippon Sumitomo Pharma 1
Medtronic 1
Mubadala Investment Company 1
Cint Group 1
Qualtrics 1
Rocket Companies 1
Saudi Arabia's PIF 1
Prosus 1
Cigna 1
One Medical 1
Exact Sciences 1
Teladoc Health 1
Ericsson 1
SoFi 1
PayPal Holdings 1
Bayer 1
Monsanto 1
AMD 1
Aurora 1
Marvell International 1
Bill.com 1
ADC 1
Dealertrack 1
Cox Enterprises 1
L'Oreal 1
AstraZeneca 1
Workday 1
Iron Mountain 1
Splunk 1
Stonepeak 1
American Express 1
OfferUp 1
VMware 1
Ontario Teachers' Pension Plan 1
Groupon 1
Allstate Corporation 1
LinkedIn 1
SAP 1
Mindbody 1
Mallinckrodt 1
Walmart 1
GMT Communications 1
Brightstar Capital 1
Enterprise Holdings 1
Healtheon Corporation 1
Apple 1
PetSmart 1
Epiphany 1
Rice Energy 1
Unilever 1
SBA Communications 1
Bridgepoint Advisers 1
Aurea 1
Vector Capital 1
FireEye 1
Littlejohn & Co 1
Alexion 1
SoftBank Investment Advisers 1
Francisco Partners 1
Betfair Group 1
Shift Technologies 1
Hudson's Bay 1
Illumina 1
Hewlett Packard Enterprise 1
AbbVie 1
Salesforce 1
Hanergy 1
Teleflex 1
Twilio 1
Okta 1
Celgene 1
NantCell 1
VMware & EMC Corp 1
Intuit 1
Yahoo! 1
Netmarble Games 1
F5 Networks 1
Roche 1
Centerbridge Partners 1
Total 177
Meta, the parent company of Facebook, leads the pack with the most unicorn acquisitions in the U.S., purchasing five unicorns since its founding in 2008, including: Kustomer, WhatsApp, Instagram, CTRL-Labs, and Oculus VR.

Notably, WhatsApp—which closed at a purchase price of $19 billion—was Meta’s most expensive acquisition yet, over nine times their next most expensive purchase, Oculus VR.
Meanwhile, Alphabet (now the parent company of Google) and Cisco are tied in second place with four U.S. unicorn acquisitions each.
  • Alphabet: YouTube, Actifio, Nest Labs, Looker Data Sciences
  • Cisco: Cerent, Duo Security, AppDynamics, Jasper
Unlike its Big Tech peers, Apple has only made the one U.S. unicorn acquisition: navigation company HopStop that helped bring public transit features to Apple Maps.
Meanwhile, 56% of acquirers received venture capital funding of their own when they were private companies. This includes pack leaders like Meta, Cisco, Alphabet, and Amazon.

Are Unicorn Acquisitions Slowing Down?
Unicorn acquisitions are driven by two factors: the rate at which new unicorns are minted, and the climate for M&A transactions more broadly.

To begin with, the minting of new unicorns is largely influenced by the venture funding environment. Funding opportunities increase when interest rates go down, which makes riskier, venture-scale ideas more enticing. During the last decade of persistently low interest rates up until 2022, unicorns flourished more than ever.

Meanwhile, as tech companies like Apple, Microsoft, Alphabet, and Meta began seeing outsized profits in the 2010s, venture investors and their LPs looked to get in on the ground floor of tech startups that could emulate their success, often paying premium valuations for the chance. Simultaneously, big tech looked to acquire unicorns themselves, both to augment their business lines and to squash potential competitors.

However, the era of “easy money” may have come to an end, and privately-held startups have seen valuations drop in recent years. This means that for the next little while—at least until monetary policy stops tightening—unicorns could become a rarer sight.

Unicorn acquisitions may also see a similar fate. Persistent inflation and the government anti-trust push are just some of the other factors that have led to VC-backed startup acquisitions falling to their lowest quarterly levels in a decade. The more expensive the valuation, the harder to find a buyer, which means that some unicorns may even lose their $1 billion tag even when they do get acquired.

(ZH) Antibiotic-Resistant Bugs Will Kill As Many As Cancer By 2050; UN Report

Antibiotic-Resistant Bugs Will Kill As Many As Cancer By 2050; UN Report

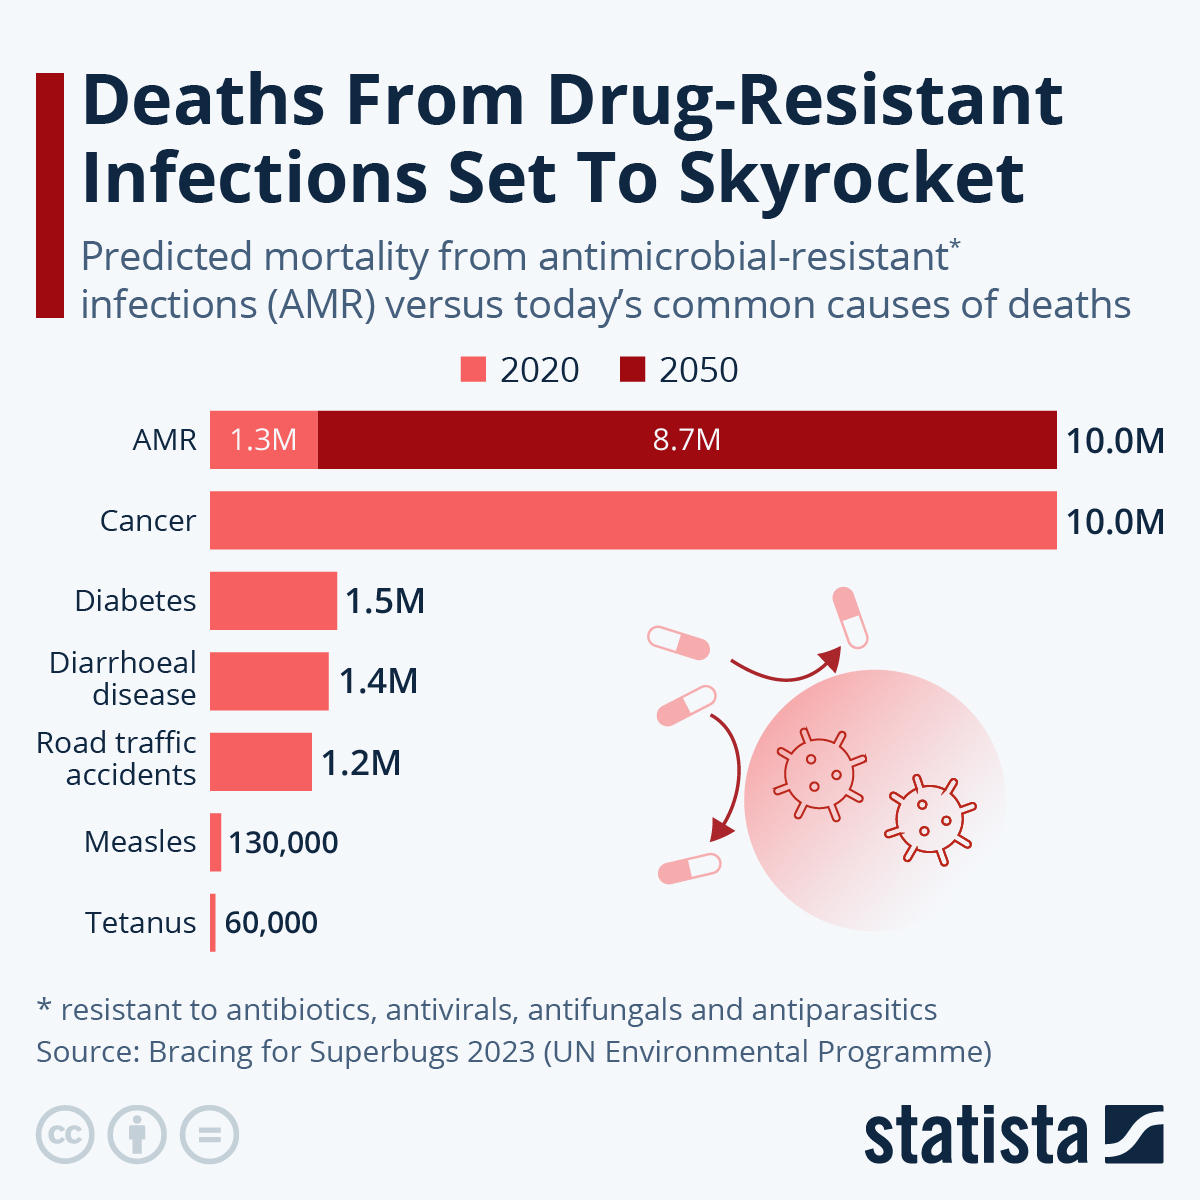
Deaths from drug-resistant infections are set to skyrocket by 2050, according to the UN 2023 report ‘Bracing for Superbugs: Strengthening environmental action in the One Health response to antimicrobial resistance.’
Unless drastic action is taken to tackle the problem, it could also lead to a GDP shortfall of $3.4 trillion annually in the next decade and push 24 more people into extreme poverty.
As Statista's Anna Fleck reports, according to recent estimates, in 2019, 1.27 million deaths were directly attributed to drug-resistant infections globally, while 4.95 million deaths were linked with bacterial AMR. That’s now well above the death counts of major killers HIV/AIDS and malaria, which were estimated to have claimed the lives of 860,000 and 640,000, respectively, that year. As the following chart shows, antibiotic-resistant infections could kill as many as 10 million people in just three decades - on par with the 2020 death toll from cancer.
You will find more infographics at Statista
Although the risks of AMR will impact people worldwide, Low-Income Countries (LICs) and Lower-Middle-Income Countries (LMICs) are expected to see the highest death tolls. By region, Asia is predicted to see the highest number of AMR-related deaths per 10,000 population in 2050 (4,730,000), followed by Africa (4,150,000), Latin America (392,000), Europe (390,000), North America (317,000) and Oceania (22,000).
According to the report, AMR also exacerbates inequalities within societies and so groups including women, children, migrants, refugees, people employed in sectors such as agriculture or healthcare, as well as those living in poverty will be particularly vulnerable to drug-resistant infections.

Business Of Fashion : At Unilever Prestige, An Acquisition Model Focused on the

At Unilever Prestige, An Acquisition Model Focused on the Future of Beauty
Unilever Prestige’s brand portfolio, including Dermalogica, Ren and Tatcha, generated €1.2 billion in revenue in 2022, with ambitions to grow through acquisitions, innovation and digital commerce. BoF meets CEO Vasiliki Petrou to learn her acquisition criteria and how quick decisions, R&D capabilities, a founder mindset and brand-centric strategy are driving the portfolio’s growth.

Unilever Prestige — Unilever’s arm for premium beauty brands, which includes brands such as Dermalogica, Ren and Tatcha — contributed €1.2 billion to the beauty multinational’s reported revenues in 2022, in excess of $63 billion.

Having launched the Prestige category in 2014, CEO Vasiliki Petrou describes the brand portfolio as a collection of “gems,” with every brand maintaining a distinct identity and a founder’s mindset. However, they share core identifying factors: a clear, meaningful purpose; an engaged brand leader; and a willingness to utilise tech and innovation to drive growth.

Growing revenues by $500 million in 2021, the category continues to perform despite challenging market conditions due to its “disciplined and selective approach to capital allocation.” The US Unilever Prestige beauty, skincare and colour cosmetics portfolio grew at twice the market rate, and digital commerce accounts for approximately 50 percent of all Prestige Beauty portfolio sales. China is now the category’s third biggest market.

The company plans to scale Unilever Prestige to a €3 billion business by acquiring best-in-category brands and investing in innovation. Unilever Prestige brands can leverage Unilever’s mighty research and development (R&D) capabilities. For example, Hourglass’ Red 0 Lipstick was created with the aim to remove carmine, an ingredient used across the industry to achieve red pigmentation that is derived from crushed female beetles. This innovation took three years, 17 formulations and 170 colour experimentations.

Now, BoF sits down with CEO Vasiliki Petrou to learn how purpose and innovation inform its decision making on acquisitions and act as the foundation of their strategy to scale the business to €3 billion.

What criteria does Unilever Prestige use when analysing potential acquisitions?

Unilever believes in the power of purpose. We believe in the positive social impact and we know that that this translates into strong advocacy within our communities. The Prestige brands all have their own authentic approach to social impact: Dermalogica support female entrepreneurs; Tatcha champion the right for girls’ access to education; REN have an embedded planet initiative through all that they do. I assess how well a brand fits with the purpose-driven mission of Unilever Prestige, and then we look at whether a brand has high growth potential with longevity — I’m always thinking 20, 30 years into the future.

My responsibility is to determine those brands that have long-lasting glide versus the quick viral wonders that could come and go. I’m looking for brands that operate in a unique benefit space, and also that behave or do things a little bit differently because I believe in whitespace thinking. If brands were doing the same things again and again, it wouldn’t be interesting for us.

Why is the leadership of a brand so important in your assessment?

In my experience, there is usually a team of two co-pilots successfully leading a company — the visionary founder and the business genius. Founders will always stay to continue to shape the vision and innovation and we then look to hire CEOs that take on the day-to-day of the global management of the P&L and the end-to-end management of the business.

When hiring CEOs, I’m looking for people that have a founder’s mindset, which means an entrepreneurial spirit, the hunger of making a difference, a passion to leave a legacy, and high integrity, high morals. We are managing big businesses and we always want to do the right thing, whether it is for the world, for our employees or for consumers’ rights — at all times.

Obviously, expertise is important — people who have done it before, that are demonstrably highly skilled. But I think the people who have made a huge difference are the people who have the thirst and passion to win, to succeed, to make a difference. They don’t take no for an answer, which is very much a founder’s mindset.

How do you approach the group’s retail strategy?

We are proud to say that more than 50 percent of the business is now through e-commerce. I have created a centre of excellence across the globe so that leaders from each brand get to share their data day-to-day. It is no overstatement to say the shared learnings are extremely powerful. By sharing intelligence across them, you achieve this exponential learning curve where people don’t learn from scratch every time, but they learn exponentially from it.

By sharing intelligence across brands, you achieve this exponential learning curve where people don’t learn from scratch every time, but they learn exponentially from it.

However, in terms of retail channels, we manage a decentralised business for a reason. People are looking for authentic brands that have depth and have a soul. A consumer will often feel a connection with that soul of the brand. So I am not a big proponent of flattening brands to something that looks and feels cookie-cutter. I want people to experience differentiated brands that deliver distinct benefits — different people have different needs after all.

When we represent a sizeable chunk of business with our retail customers, whether it is Sephora or Ulta, you have a joint partnership, a business relationship, where you can talk about where we are going as a group — that is our North Star.

How are you using technology to innovate the connection between brands and consumers?

We have maintained the freedom of individual brands to experiment and play within their differentiating genres and lead the way in the areas they excel. So Dermalogica are continually using advanced technology initiatives to strengthen their global education programmes for their professional skincare therapists and medi-spa services.

Tatcha uses technology in a different way as an enabler to connect with their consumers through virtual immersive experiences — they have just done this with a forest bathing immersion that brought to life my dream of how to take our global consumers to Japan and bring our heritage to life. How to make people experience, digitally at least, a sense of forest bathing — both the inspiration and the benefits.

This year, Paula’s Choice also launched a Beautypedia ingredient checker. Paula wrote a famous beauty ingredient-focused book — Don’t Go To The Counter Without Me — that became something of an industry and consumer bible. Now you can scan any ingredients list on any product with your phone and it will give you an analysis of the quality of ingredients measured against specific, transparent principles. That is another example of a brand that is anchored to their DNA and make it accessible to consumers around the world.

How does Unilever Prestige help the brands it acquires leverage Unilever’s R&D capabilities?

Whether it is epigenetics, or expertise on vitamin C, retinol, skin pigmentation, melanin-rich skin, Unilever has outstanding R&D capabilities. All businesses have the opportunity to tap into this rich resource which when combined with our own brand research, and scientists can work in a way that one plus one can sometimes equal ten — and that’s exciting.

One powerful example — Unilever R&D worked for three years in the search for a vegan alternative to [the red pigment] carmine. To achieve a true deep red lip colour in colour cosmetics, traditionally the industry used crushed female beetles. However, Hourglass is a cruelty-free brand and we were obsessed with finding a vegan alternative to carmine.

After three years of research and testing, I believe we are the first premium brand that has delivered an alternative to carmine, which is something we are very proud of. This is the beauty of tapping into the best of the best that R&D has.

What do you believe will define success for beauty brands in the near to mid-term?

If we don’t serve the consumer, what do we do? What makes me get out of bed is to make an impact every day. The emotional letters of gratitude we receive due to the transformation our products can achieve are extremely inspiring. For example, we get a lot of letters from women dealing with chemotherapy that are using scalp and hair care products. This is what gives me the fuel for continuing to make a difference in people’s lives. This is much bigger than simply skin or hair care.

What do you believe will drive the growth of the group to $3 billion in revenue?

To win, we have to be fast. So quick decision-making from me, but also from the CEOs, is a critical ingredient and I think key to what we have done well so far. We are often the first to market with a lot of breakthrough innovation — both in product, technology and experiences. We have been able to quickly turnaround superior diagnostics, personalised advocacy and immersive experiences and our consumer wants that.

Positive social impact will continue to be an important part of our business model because, even now, it is still rare to see truly authentic purpose-driven brands.

Positive social impact will continue to be an important part of our business model and that has helped us to stand out because even now, it is still rare to see truly authentic purpose-driven brands. Typically, some brands like ticking boxes. But for us, it’s part of who we are, and that’s difficult to do. You have to believe it and then you have to make it part of the DNA of the brands, the business model, everything. Our business model is based on a brand-centric approach versus more of a synergistic commercial approach because I don’t think that’s a good long-term strategy.

The priorities are always there, but we have only just started from my perspective. In the US, in 2022, in the skincare premium market, we grew double the market growth rate. We are substantially present in the UK market and growing. We have launched a successful business in China — there is a big business to build there. So, I believe we have billions of lives to impact and I can’t wait for more people to experience the brands and their values. The impact is magical and I want everybody to experience that magic.
FT : Wim Dejonghe: the Belgian rainmaker sealing Allen & Overy’s deal with Shear

Wim Dejonghe: the Belgian rainmaker sealing Allen & Overy’s deal with Shearman
The magic circle law firm’s senior partner has long held ambitions for a transatlantic merger

When troubled New York law firm Shearman & Sterling’s merger talks with its transatlantic rival, Hogan Lovells, collapsed in March, Shearman’s Adam Hakki knew who to call.

Days into his role as senior partner last month, Hakki picked up the phone to ring Wim Dejonghe, the long-serving leader of Allen & Overy, one of London’s elite magic circle law firms. In a matter of weeks, the two were cloistered in a Manhattan office hashing out a $3.4bn merger, which — if voted through — will be one of the biggest the industry has ever seen. 

For Belgian-born Dejonghe — A&O’s first foreign senior partner and before that, managing partner — a tie-up with a Wall Street firm will be the fruition of a two-decade-long project to crack the most lucrative legal market in the world, leaving its British rivals in the dust. For Shearman, it offers a route out of a torrid period of partner exits and difficult restructuring.

“I’ve known Shearman for a long time. [Hakki] got into the role [and] he knew we were interested,” Dejonghe, 62, told the Financial Times. “The initial conversation was between me and him. After a number of meetings between the two of us, we thought: ‘this might work, actually’.”

Shearman, a storied 150-year-old firm that once advised the cream of corporate America, is the far smaller entity, with $907mn in revenues last year and about half of A&O’s more than 40 offices. But it has long been on Dejonghe’s dance card as a potential suitor because of crossovers in banking and finance.

Both firms had also learned lessons from previous failed mergers: in A&O’s case, collapsed talks with California-headquartered O’Melveny & Myers, which ground to a halt in 2019 after 18 months of negotiation.

“We knew [if] this leaks before we go to our partners, we’re dead,” said Dejonghe. “So we agreed the only way we could deliver something to [partners] was to sit together in a room for weeks and hammer out all the details.”

Shearman declined to comment.

With a small core team — including advisers from heavyweight Wall Street law firms Simpson Thacher & Bartlett, and Davis Polk & Wardwell — Hakki and Dejonghe decamped to investment bank Lazard’s offices in Manhattan to pull together what would land on Sunday as a slick announcement, complete with website, client FAQs and video. 

Dejonghe’s predecessor, David Morley, credits him for the speed of the Shearman talks, which were executed within weeks. “Very few people could have done this, but Wim has had this clear strategic vision for a long time.” 

Morley, who led the firm alongside then-managing partner Dejonghe for eight years to 2016 says: “Wim didn’t wake up yesterday and say: ‘it’d be great to do a merger’…. The firm has been thinking about and debating it for at least two decades, and looking at options . . . So they were ready to move really quickly when this came up.”

Morley and Dejonghe, viewed as a modernising force at A&O, spent years pounding the pavements in New York and on the US west coast in the wake of the financial crisis, dining with law firm leaders in powerbroker hotspot Estiatorio Milos in Manhattan.

“Some people would see us,” says Morley. “Others were frightened of even being seen in a restaurant with us in case their partners saw us or it got into the press . . . We weren’t asking people: ‘do you want a merger?’ — just building relationships and gaining insight.” He said this meant Dejonghe had built up a “pretty good Rolodex of American firms”.

A&O has long had offices in the US. But growing there has not been plain sailing. Like its international rivals, A&O has struggled to break into a market dominated by a pack of highly profitable domestic firms with greater firepower to pay star partners. Wall Street’s top firms tend to be tightly focused, with only a handful of international offices and a pipeline of lucrative private equity and finance work.

By contrast, A&O and its magic circle peers in the UK have sprawling global networks, offering clients a far wider variety of work. That has made them one-stop shops for many corporations, but less profitable than their US peers. Partners at Wall Street firms such as Simpson Thacher and Davis Polk took home more than $5mn on average last year, for example, while M&A powerhouse Wachtell Lipton Rosen & Katz partners pocketed more than $7mn. In contrast, A&O’s partners took home £1.9mn ($2.3mn) on average last year.


Tony Williams, a consultant who was managing partner at Clifford Chance when it merged with American firm Rogers & Wells in 2000, said: “The magic circle have been challenged in the last decade by the strength of the US economy . . . And Brexit didn’t help: sterling is now at $1.23.”

One former high-ranking A&O partner said: “Every magic circle firm has been looking to come into the US market for the last 30 years, and a merger has always been the most logical way but it’s extremely difficult to do. The top American firms have always been much more profitable, which for them is a proxy for excellence.”

He added, “Shearman has had some difficulties over the past few years, and suddenly they were available and there’s an opportunity for a match.”

Vast differences in partner pay made it difficult for UK firms to compete in the US, a problem compounded by the stronger dollar. As a result, under Dejonghe, A&O has gradually chipped away at its so-called lockstep pay structure, where partners are paid according to time served, to pay star performers more.

Dejonghe, who another former partner described as “charismatic and entrepreneurial”, is no stranger to overseas mergers, where marrying two different cultures is vital to success. The corporate lawyer, who has five sons, joined A&O when it tied up with part of Loeff Claeys Verbeke — a Brussels-based firm Dejonghe led as managing partner.

He said the Shearman merger is a “merger of equals” in the same way as that deal. “You can’t say to your future colleagues, we’re acquiring you,” he said. “That’s not the mindset . . . It doesn’t work like that.” 

Becoming managing partner at A&O meant leaving Belgium’s cobblestoned streets and its many cycling races. Dejonghe, who cycles to A&O’s Spitalfields office each day, is a veteran of amateur events including the Etape du Tour and the Tour of Flanders.

“I’ve sat in his slipstream going up and down mountains for many years,” said Morley. “We used to tease him that he was good on the flat . . . He used to retort that in Belgium you’re always cycling against the wind. We were always joking with each other; it was kind of a metaphor for the way we worked together.”

“Hills are not my favourite to be honest,” Dejonghe conceded. “Give me the Tour of Flanders anytime.” 

The Shearman deal ahead of him is likely to be a challenge of a very different kind, and potentially the pinnacle of his 15 years at the top. But Dejonghe is sanguine: “I’ve always had a forward-thinking mindset. I’m probably a bit more optimistic than some lawyers.”

FT : Why EU cuts to red tape could hamper environmental ambitions

Why EU cuts to red tape could hamper environmental ambitions

Green tape
Some EU officials worry that a push to cut red tape could let companies off the hook regarding their efforts to reach the Paris climate goals.

New draft rules seen by the Financial Times would make reporting on climate impacts voluntary rather than mandatory for EU companies, writes Alice Hancock.

Context: this year, an update of the bloc’s corporate reporting standards came into force, increasing the number of companies covered by the rules. It sets out that businesses have to report to a set of standards, which will be laid out in further legislation this year.

According to the draft of that legislation, companies won’t have to disclose efforts to come in line with the Paris climate agreement unless the company deems them “material” to its activities.

A specialist advisory group, EFRAG, had advised making reporting climate impacts mandatory, while others, such as employment conditions, could be submitted according to an assessment of their importance done by the company itself.

But the European Commission seems to have disregarded that advice and wants to make all areas, including climate, subject to a “materiality assessment”.

The change has prompted disquiet among more environmentally-minded officials. They argue that it will be more difficult to track the effect of businesses’ activities on the climate. Finance institutions would also have a harder time keeping tabs on businesses they invest in for their own financial reporting.

It also means that companies can set their own terms when it comes to decarbonisation, one EU official said, as seen at the ExxonMobil annual meeting last week.

The move is part of Brussels’ wider effort to cut red tape, after commission president Ursula von der Leyen promised to reduce reporting requirements for businesses by a quarter.

A document circulated this week by Denmark and Estonia showed that there was support among member states for the anti-bureaucracy push.

But in an ironic twist, the changes mean the work for companies might not actually decrease. An executive at a major multinational firm said that while there might be less actual reporting, “it will still take the same amount of work for us because we need to do the assessment for all”.

The commission declined to comment on the change. It said that the standards “will be published for public consultation as soon as possible”.

WWD : Printemps Teases NY Flagship With New Deauville Concept Store

Printemps Teases NY Flagship With New Deauville Concept Store
The French retailer has scrapped brand counters in favor of a cross-merchandising approach.


DEAUVILLE, France — Department store chain Printemps has transformed its smallest store in France into a colorful concept store aimed at wealthy holiday-makers, in a preview of the new format it will roll out on a larger scale at its New York flagship, set to open next year.

The 12,900-square-foot store in the seaside town of Deauville is set to reopen on Friday after a five-month renovation that involved knocking down walls and opening windows to give the neo-Norman style building, originally constructed in 1912, the feel of a lush private home.

“It’s a store that will become a memorable and essential destination in Deauville,” said Printemps chief executive officer Jean-Marc Bellaiche. “It’s our first store of this kind. It’s really a unique concept.”

Printemps has scrapped brand counters in favor of a cross-merchandising approach, eliminating any labels that are available elsewhere in town and replacing them with a selection of 300 brands, of which 85 percent are exclusive to the store and 85 percent are new.

It has a sales staff of 40, including six personal shoppers, all of whom are directly employed by the retailer and trained to sell across categories including womenswear, menswear, watches and jewelry, shoes, beauty, gifts and homewares.

Bellaiche touted it as the latest example of Printemps’ strategy of rolling out unique concepts, such as the temporary rooftop café it opened recently in partnership with jeweler Messika at its Boulevard Haussmann flagship in Paris.

“There is always a more intimate side, a more human side to what we do compared with our competitors, who are sometimes too big or too diverse,” he said.

“This store is also taking a risk,” Bellaiche added. “Deauville will give you a foretaste of what New York will be like. New York will represent an even bigger investment, particularly in terms of architecture, but in terms of offer, in terms of rationale, it will also be a very large concept store rather than a department store.”
The atrium of the Printemps store in Deauville.
ROMAIN RICARD/COURTESY OF PRINTEMPS

Spread over two floors, rooms are decked out in bright hues inspired by local landscapes, with mosaic floors set off with carpets in oversized motifs drawn from the Printemps archives.

The curved outline of the clothing racks is inspired by traditional local furniture, and shelves are dotted with thrift store finds, including a battered brown hat box and a yellow sewing machine.

New features include an atrium with 33-foot-high suspended sculpture consisting of 1,500 brass leaves, 80 ceramic magnolia flowers and LED lights.

Sophie Bocquet, chief network officer of Printemps and its urban apparel chain Citadium, said the Deauville store caters to an affluent crowd made up of 43 percent tourists, 22 percent people with second homes in the area, and 35 percent local residents.

Its average basket of 250 euros was already the highest of its regional network in France, and Bocquet expects the renovation to boost annual sales by at least 25 percent.

“This store is a real game-changer. It’s something that’s never been done, either at Printemps or elsewhere. We practically started from a blank page, as if we were opening a store and not reopening it,” she said.

With products ranging from hostess gifts such as 95-euro Guerlain candles, to a giant ceramic urn that retails for 1,050 euros, the store is an impulse shopper’s delight. “Deauville is synonymous with pleasure, so when you come to Deauville, you really want to treat yourself or someone close to you,” Bocquet said.
The Printemps store in Deauville.
ROMAIN RICARD/COURTESY OF PRINTEMPS

When the location originally bowed in 1912, it marked the first time any French department store had opened a branch outside Paris, noted Stéphane Roth, chief marketing and communication officer at Printemps.

It was built at the same time as the Normandy hotel across the street to cater to a growing leisure class, drawn by attractions including a casino and a racetrack.

Printemps renovated the facade of the listed building between 2017 and 2019, and has replicated its timber structure in the décor of the watches and jewelry department on the first floor, which is now flooded with natural light. The floor is also home to shoes and beauty, including a treatment room offering FaceKult facials.

On the ground floor, clothing and accessories from labels including Burberry, Céline, Chloé, Courrèges, Jacquemus, Khaite, Loewe, Miu Miu, Prada and Valentino sits alongside items like Cire Trudon candles, Baccarat crystal objects and a porcelain edition of Jeff Koons’ Ballon Dog (Blue) sculpture by Bernardaud that retails for a cool 50,400 euros.

There is also plenty of casual fashion on offer, from Carhartt, Diesel and Levi’s, to Erès and Atalaye swimwear, embroidered beach dresses from Benaras by Citrus, and summer-ready footwear from K. Jacques, Ancient Greek Sandals and Alohas, among others.

Among the selection of vintage clothing and accessories in the Second Printemps room is a hard-to-find black Hermès Kelly bag, while the retailer’s own Saison 1865 label offers accessibly priced contemporary styles with a sustainable bent. “It’s a selection worthy of a world capital, both in terms of quality and creativity,” Roth remarked.

Already France’s second most popular destination for conferences, Deauville should receive a visitor boost next year when the region marks the 80th anniversary of the D-Day landings. And next September, Printemps will partner for the first time with the Deauville American Film Festival.

“We are betting on the fact that Deauville will continue to see strong international growth. It already has a very high visibility,” said Bellaiche.

He said Printemps is considering opening similar stores in other French cities, although the offer might be tweaked in line with the location’s potential. “We believe that a smaller format brings us closer to the customer,” he said.

Group comparable sales at Printemps were up 25 percent year-on-year in the fiscal year ended in March 2023, according to Bellaiche, and remain down 2 percent versus the year before the outbreak of the coronavirus pandemic.
Printemps has 16 department stores, including one overseas branch in Doha, Qatar; nine Citadium stores, and four e-commerce sites: printemps.com, citadium.com, fashion e-commerce site Place des Tendances and online homewares retailer Made in Design.
The Printemps store in Deauville.
ROMAIN RICARD/COURTESY OF PRINTEMPS