Haaretz : Record-breaking Spike in Countries Buying Israeli Arms and Cyber

Record-breaking Spike in Countries Buying Israeli Arms and Cyber
Last year, Israel approved the marketing of drones to 145 different countries, with a 25% increase in the number of countries to which intelligence and cyber systems were sold – reveals data disclosed in response to a Freedom of Information request

The number of countries to which the Defense Ministry has authorized exports of weapons and security-related cyber systems has skyrocketed in recent years, according to its own official data. The figures coincide with the export records of Israel’s defense industries, which broke their own records two years in a row.

Reasons for the boom in defense exports include an increase in arms deals with signatories of the Abraham Accords, and the war in Ukraine, which led to increased security expenditures in Europe and NATO countries. The record-breaking growth is expected to continue, in part due to the unprecedented sale of an Arrow 3 missile defense system to Germany for about $3.5 billion, a deal that was signed last week.

The data, provided by the Defense Ministry in response to a Freedom of Information request from human rights lawyer Eitay Mack, reveals that the number of countries to which the ministry approved the sale of drones grew by 40 percent in three years: from 40 to 56 countries in 2022. The number of countries to which munitions were exported grew by 45 percent, from 42 to 61; training programs were sold to two countries three years ago, but is currently being supplied to 17; and the sale of cyber and intelligence systems grew from 67 to 83 countries in 2022.

These numbers concern countries to which the Defense Ministry’s Defense Export Control Agency approved export. Prior to this approval, arms companies must obtain a marketing license, which is required for any action from sending an email to mounting an exhibition or hosting at the companies’ factories. “It’s a two-stage mechanism,” said Racheli Chen, head of DECA, last year in a Knesset hearing on the sale of Israeli weapons to dictatorial governments. “The marketing license is the filtering stage. … Those who are refused a marketing license will not apply for an export license. Those we approve for marketing, we’ll probably approve for an export license. That’s the mechanism’s rationale as we have determined.”

The number of countries with a marketing license is thus the true indicator. Here, there is no category in which the number of countries was under 100. In each category except for the export of training, there has been an increase in the last three years. That number is likely even higher, since Israel has exempt over 100 countries from needing a marketing license for some technologies.

At the top of the list is the drone-sale sector – in 2022, marketing of drone technologies was approved for 145 countries. In the intelligence and cyber category, 2022 marketing licenses were granted to 126 countries – a significant increase after the dramatic decline of 2021 brought about by the exposure of widespread use of Pegasus spyware in non-democratic countries, and by NSO and Candiru being blacklisted by the U.S. government.

Exposing the international Pegasus Project, in which TheMarker and Haaretz took part, shocked the Israeli defense establishment. When the dust settled it was reported that Israel had dramatically restricted the list of “exempt countries,” or countries to which offensive cyber capabilities can be marketed without a special marketing license, to 37. However, the Defense Ministry refuses to disclose which countries and cyber products were on the list.

Determining whether qualification for offensive cyber exports was indeed made stricter following the Pegasus scandal is made even more difficult by the ministry’s choice to include intelligence exports and cyber technologies together in the same category.

Speaking in the same Knesset hearing, DECA head took pride in the rigor of the agency’s criteria preserving human rights. “This is a process that is set in law… it is not a process that we change according to whether one minister or another minister is elected.” “It is a policy to be careful and pay attention to human rights as one of the very central criteria that we consider in every request,” she said.

Chen added that DECA first examines whether a potential buyer is on the list of pre-approved countries, then inspects the regional and intra-country security and political maps: “what is the state of human rights in the state itself? Who is the final user? If they are asking for a product for police use that is not appropriate for the police to have, we will not allow it.”

And yet, if one cross-references the number of countries in each of the Defense Ministry’s export categories with the The Economist Democracy Index, one is hard-pressed to find the results of such rigor. In the latest index, 59 countries were defined as “authoritarian regimes”; only 24 countries were defined as “full democracies”; 48 were defined as “flawed democracies” (including Israel, the United States, Hungary, Poland, and Ghana); and 36 were defined as “hybrid regimes” (including Zambia, Bangladesh, Pakistan and Sierra Leone). In total, there are 108 countries that are not explicitly tyrannical regimes (and at least a third of them are notorious for violating human rights). Simple math shows that apart from the “ammunition and armament” category, the State of Israel must have signed off on the marketing of military and dual-use technologies to “full-fledged” dictatorial regimes.

FT : Is carbon insetting the next big thing?

Is carbon insetting the next big thing?
As voluntary offsets lose favour, the ‘insetting’ approach has quietly gained steam

One thing to start: Litigation finance — the investing technique that involves funding lawsuits in the hopes of sharing in any damages awarded in court — has often been viewed as a potential threat to oil and gas companies, without coming to fruition in a big way.

But now there has been a major development. Our colleague Brooke Masters reported at the weekend that US hedge fund Gramercy has struck one of the largest-ever litigation funding deals to back separate environmental lawsuits against miners BHP and Vale, and 14 global carmakers, with both cases set to go to trial next year.

The $552.5mn funding is in the form of a secured loan to law firm Pogust Goodhead, and is the largest ever to a UK law firm in the nearly $16bn litigation funding market. That could be a significant development and one that will surely make big polluters nervous.

Today, I have a report on the rise of “insetting” – as companies shift their focus towards tackling the carbon emissions of their suppliers, rather than offsetting their emissions in the controversial voluntary carbon market. Thanks for reading. — Patrick Temple-West

Carbon offsets are out
One of the big themes at the cocktail parties and luncheons during last month’s Climate Week NYC was the souring mood towards the voluntary carbon market.

Voluntary carbon credits — different from the government-regulated credits seen, for example, in the EU’s emission trading scheme — have been widely used by companies as an inexpensive way to offset emissions. For years, the market has been dogged by claims that it is an unregulated, unreliable wild west and a vehicle for corporate greenwashing. And, as Kenza’s piece last month highlighted, carbon offset projects, even when well intentioned, can come with significant risks for corporate users.

The Commodity Futures Trading Commission this summer issued a rare whistleblower alert, asking people to come to the agency with tips about potential fraud in carbon markets. The agency also created a new “environmental fraud task force” to investigate misconduct in the market for carbon credits and other environmental products. Even if a company’s carbon credits are found to be faultless, the fact that the CFTC is snooping around is certain to have a chilling effect for the offsets market.

The offsets market was “facing a reckoning amidst a continuous stream of news around concerns that the vast majority of carbon offsets are ‘worthless’”, Morgan Stanley warned in a September 6 report. Certain voluntary carbon offset futures traded on the CME Group exchange in Chicago have fallen from a range of $15 to $5 in 2022 to below $1 now, the bank said.

As a result, “we think companies [will] continue to focus on ‘within’ value chain decarbonisation”, Morgan Stanley said.

As voluntary offsets lose favour, this “insetting” approach has quietly gained steam. In an article last year, the World Economic Forum characterised carbon insetting as “doing more good rather than doing less bad within a value chain”.

With insetting, companies spend to improve their suppliers’ carbon footprint, whereas typical decarbonisation spending targets companies’ own decarbonisation efforts (which appear in sustainability reports and sometimes in regulatory filings). Rather than spend cash on carbon offsets in far-flung parts of the world, the insetting concept brings decarbonisation spending closer into a company’s orbit.

But only a few companies are talking about insetting openly. Nestlé has adopted a framework that includes 25-year contracts with coffee suppliers in Nicaragua to implement restoration projects. Since most of Nestlé’s carbon emissions came from agriculture production for its food and beverage products, its supply chain presented an important opportunity, Nestlé spokeswoman Dana Stambaugh told me.

“Our net zero road map does not rely on offsets,” she said. “We focus on greenhouse gas emissions reductions and removals within our value chain to reach our net zero ambition.”

In the US, Gevo, a Colorado-based alternative fuels company, has promoted the insetting approach and announced a system to measure carbon intensity. For example, Gevo said insetting offered an airline that bought sustainable aviation fuel the benefit of the renewable energy used in the production process. By contrast, offsets were a mitigation strategy for what were often unrelated value chains. 

Regulations in Europe and California were also driving companies to think more about insetting, said Michael Smith, a co-founder and general partner of venture capital firm Regeneration. The EU’s Corporate Sustainability Reporting Directive (CSRD) requires companies to disclose certain information about their scope 3 emissions, which come from their supply chains and from the use of their products by customers.

Insetting, Smith said, “is not just a Patagonia thing,” referring to the clothing company known for its energetic approach to sustainability. Walmart, with its “Project Gigaton,” as well as Unilever and Ikea had also been actively experimenting with insetting in their supply chains, he said. Regeneration has been investing in start-ups that sell tools to big businesses that need to cut supply chain emissions. For example, Smith’s firm has invested in Greyparrot, a London-based waste analytics company.

As companies shifted from carbon offsets to insetting, “now you have gone from planting trees in a country that you probably have never gone to, to incentivising your [suppliers] to make key changes, which makes more business sense”, Smith said. 

But insetting has its sceptics too. “Many of the same criticisms of nature-based offsetting could be applied to insetting projects,” Nora Mardirossian, a senior legal researcher at the Columbia University Center on Sustainable Investment, told me.

Moving away from the loosely-defined term “insetting” was a good first step, Mardirossian said. “To help avoid a new hot-button term from popping up only to find out it’s just traditional offsetting repackaged, there is a serious need for stricter rules on respect for human rights across all nature-based solutions and on the integrity and transparency of carbon credits,” Mardirossian said.

There was definitely a near-term need for the voluntary carbon offset market, Smith said. And the market is racing to set standards. The Integrity Council for the Voluntary Carbon Market, an independent governance body for this market, in July launched a core carbon principles assessment framework and procedure. It is now beginning to assess carbon-crediting programmes to define which are eligible.

Insetting might seem obvious. Why wouldn’t companies be doing this already? But if standards can be set for this area, enabling regulators and shareholders to make meaningful comparisons of companies’ approaches to it, then insetting could pose a viable alternative to the offsetting model that may be losing steam. (Patrick Temple-West)

Smart read
UK exporters are facing huge payments under the EU’s new carbon border adjustment mechanism — money which would otherwise have flowed to the UK Treasury, the FT reports. This follows a collapse in prices on the UK’s own carbon market, amid a rollback of green policies by Rishi Sunak’s government.

>>> US Research Calls

Research Calls
  • Upgrades:
    • Cintas (CTAS) upgraded to Conviction Buy from Buy at Goldman
    • Clorox (CLX) upgraded to Buy from Neutral at DA Davidson; tgt $152
    • Datadog (DDOG) upgraded to Overweight from Neutral at Piper Sandler; tgt raised to $115
    • FedEx (FDX) upgraded to Positive from Neutral at Susquehanna; tgt raised to $315
    • Insulet (PODD) upgraded to Buy from Hold at Jefferies; tgt lowered to $240
    • LGI Homes (LGIH) upgraded to Neutral from Sell at BTIG Research
    • Macerich (MAC) upgraded to Neutral from Underweight at Piper Sandler; tgt raised to $12
    • Mr. Cooper Group (COOP) upgraded to Outperform from Mkt Perform at Keefe Bruyette; tgt raised to $65
    • NVIDIA (NVDA) upgraded to Conviction Buy from Buy at Goldman
    • Okta (OKTA) upgraded to Conviction Buy from Buy at Goldman
    • PennyMac (PFSI) upgraded to Outperform from Mkt Perform at Keefe Bruyette; tgt raised to $81
    • Quanterix (QTRX) upgraded to Conviction Buy from Buy at Goldman
    • Rivian Automotive (RIVN) upgraded to Outperform from In-line at Evercore ISI; tgt $35
    • U.S. Steel (X) upgraded to Overweight from Equal-Weight at Morgan Stanley; tgt raised to $40
    • Zscaler (ZS) upgraded to Overweight from Neutral at Piper Sandler; tgt raised to $190
  • Downgrades:
    • Adecoagro S.A. (AGRO) downgraded to Market Perform from Outperform at Itau BBA; tgt $12
    • Bread Financial (BFH) downgraded to Sell from Neutral at Goldman; tgt lowered to $32
    • Chubb (CB) downgraded to Neutral from Overweight at JP Morgan; tgt $250
    • Fidelity National (FNF) downgraded to Mkt Perform from Outperform at Keefe Bruyette; tgt lowered to $43
    • Johnson Controls (JCI) downgraded to Buy from Conviction Buy at Goldman
    • NatWest Group plc (NWG) downgraded to Equal-Weight from Overweight at Morgan Stanley
    • NextEra Energy Partners (NEP) downgraded to Equal Weight from Overweight at Wells Fargo; tgt lowered to $33
    • Norfolk Southern (NSC) downgraded to Neutral from Buy at BofA Securities; tgt lowered to $215
    • Salesforce (CRM) downgraded to Buy from Conviction Buy at Goldman
    • Sandy Spring Banc (SASR) downgraded to Neutral from Buy at DA Davidson; tgt lowered to $22
    • SolarEdge Technologies (SEDG) downgraded to Equal Weight from Overweight at Barclays; tgt lowered to $152
    • Toast (TOST) downgraded to Neutral from Buy at Mizuho; tgt lowered to $16
  • Others:
    • pellis Pharmaceuticals (APLS) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • Atlassian (TEAM) initiated with a Neutral at UBS; tgt $225
    • BigBear.ai (BBAI) initiated with a Market Perform at TD Cowen; tgt $2
    • Caesars Entertainment (CZR) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • Carnival (CCL) resumed with an Outperform at William Blair
    • Celldex Therapeutics (CLDX) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • Credo Technology Group (CRDO) initiated with an Overweight at Barclays; tgt $18
    • Datadog (DDOG) initiated with a Neutral at UBS; tgt $100
    • Etsy (ETSY) initiated with a Neutral at Wedbush
    • Everest Group (EG) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • L3Harris (LHX) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • Maxeon Solar (MAXN) initiated with a Neutral at UBS; tgt $13
    • Microsoft (MSFT) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • Nextracker (NXT) initiated with a Buy at UBS; tgt $50
    • Sunnova Energy (NOVA) initiated with a Buy at UBS; tgt $16
    • SunOpta (STKL) initiated with a Buy at Mizuho; tgt $9
    • UnitedHealth (UNH) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • Western Digital (WDC) added to Q4 2023 Tactical Ideas List at Wells Fargo
    • WK Kellogg Co (KLG) initiated with a Hold at Jefferies; tgt $15
    • Xenon Pharmaceuticals (XENE) added to Q4 2023 Tactical Ideas List at Wells Fargo

(ZH) US Meteorologist Warns: "Winter This Year Going To Be Very Different" As El

US Meteorologist Warns: "Winter This Year Going To Be Very Different" As El Nino Ramps Up

"Winter in the US this year is going to be very different. El Nino is ramping up in the Pacific. Sea surface temperatures in the Atlantic Ocean are still off the charts, and we're going to have an amplified southern jet stream," US meteorological analyst and YouTuber Ryan Hall said in a video published on Saturday. He said the El Nino weather phenomenon will "affect how much snow we get and how often we see it, but it's also going to change when the snow starts."
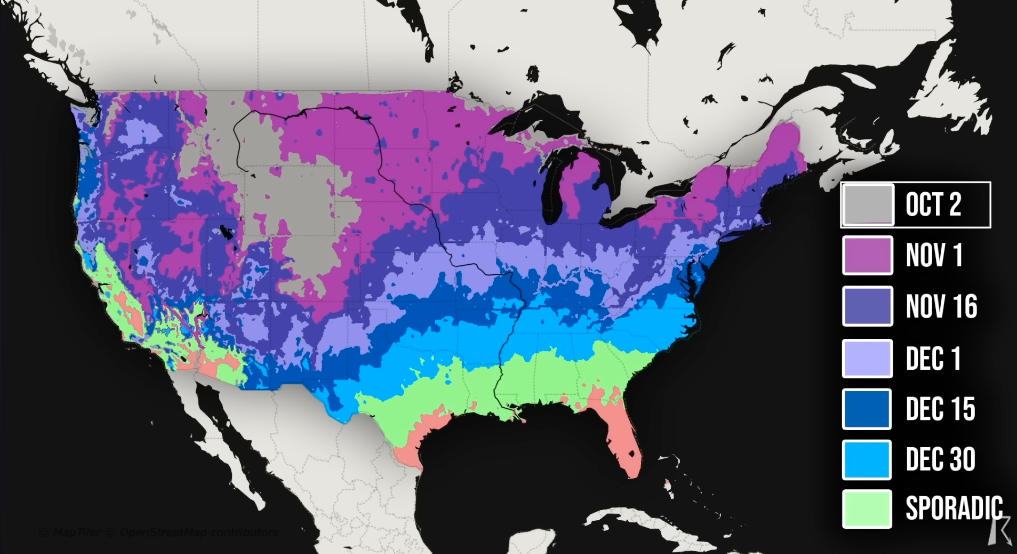
Hall constructed a map of the US regions that usually see the first measurable snowfall:
  • Moving on to this light blue region, this is where we have a lot of data supporting an average first snowfall of around December 30th. This includes Raleigh, North Carolina, Nashville, Tennessee, Little Rock, and Dallas. Essentially, sometime in January is when you're going to see your first snow down here. But beyond this, we can get a little bit more detailed with our first snowfall date because we have a lot to work with as far as historical averages go.
  • In the darker blue here, we typically see our first snow either after December 15th or before December 30th. So that narrows it down a lot. This includes places like Bowling Green, Kentucky, and St. Louis.
  • This light purple zone indicates an area where we expect to see snowfall sometime between December 1st and December 15th. And now we're talking about places like Washington DC and Cincinnati and Peoria, Illinois.
  • Now, once we get into this darker shade of purple, we're talking about a large area of the US seeing their first measurable snowfall between November 16th and December 1st. This is Chicago, Pittsburgh, and a lot of southern New England. It's very important to remember that these are just historical averages.
  • Especially in this pink zone, where on average, we see our first snow between November 1st and November 16th. There tend to be some major swings up here.
  • And then, of course, the final gray zone here shows us where snow can occur as early as October 2nd, which is actually around the time that this video goes up. But there you have it.

Here's the first snowfall prediction map:
Hall pointed out, "But I want you to think back to what I said at the beginning of this video. This is not a typical year. The 2023-2024 winter season is going to be very different" due to "2023-2024 winter is an El Nino pattern."
He said for the past three La Nina winters have kept "areas in the South and East drier and warmer, and it keeps the North and Northwest a little bit colder and wetter. But for the first time in a while, we're entering this upcoming winter in a full-blown El Nino."
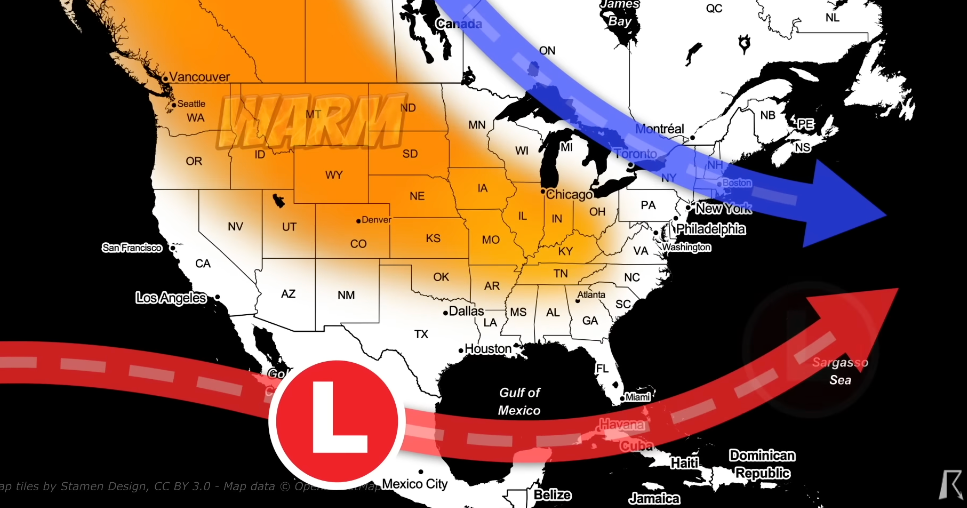
"This is when those waters down in the Pacific are warmer than usual, and the thunderstorm activity starts going crazy. This actually amplifies the Southern Jet Stream, sending several storm systems flying across the Southern US. And a lot of times, those storm systems are very strong, and they can latch on to some of the colder air up north and cause very big snowstorms. For example, some of you guys might remember the North American blizzard of 2003," Hall explained.
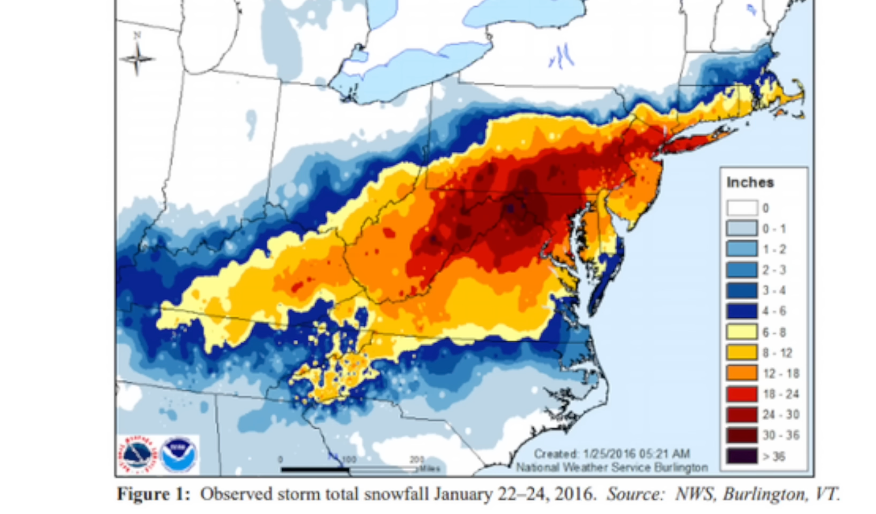
He also reminded folks of the "January blizzard of 2016 dumped three feet of snow across a huge chunk of the Mid-Atlantic region, and caused $500 million in damage. Now, we can't say that either of those storms were directly caused by El Nino, but it's something to keep in mind as we develop our forecast. And El Nino years are notorious for keeping things mild, especially in the East."
Here's the full forecast:
-->
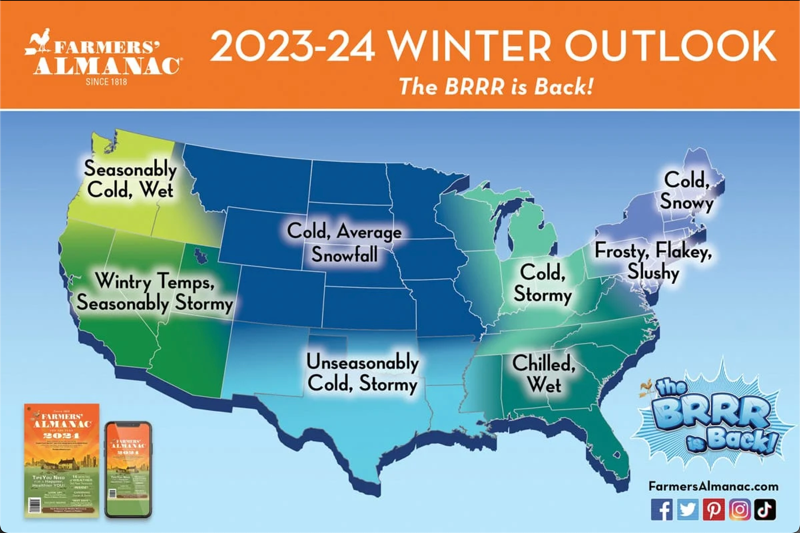
Besides Hall, Peter Geiger, editor of the Farmer's Almanac, warned in an August weather note: "The 'brrr' is coming back! We expect more snow and low temperatures nationwide."
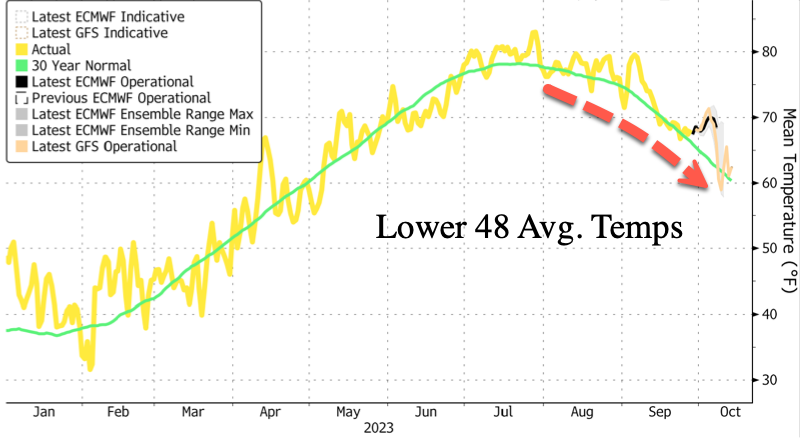
Last week, we pointed out several notable meteorologists who expect average temperatures to dive across the Lower 48 as early as next weekend.
And all we hear from corporate media and their climate warrior cheerleaders is crickets as the climate changes into fall.

>>> US Gapping down

Gapping down
News:
  • SNDX -10.1% (Pivotal AUGMENT-101 Trial of Revumenib in Relapsed/Refractory KMT2Ar Acute Leukemia)
  • ARCH -8.6% (provides Q3 update; revises FY23 outlook)
  • EGO -2.2% (reports Q3 production; provides project update on Skouries)
  • ARR -2.1% (announces effectiveness of one-for-five reverse stock split)
  • IMAX -2% (Independent Proxy Advisory Firm Glass Lewis Recommends IMAX China Shareholders Vote "FOR" the Privatization Transaction with IMAX Corporation)
  • ORGN -1.6% (appoints Matt Plavan as CFO)
  • NSC -1.5% (provided an update Saturday on a technology outage that impacted rail operations; downgraded to Neutral from Buy at BofA Securities)
  • TAK -1.1% (announces amendment of compensation recoupment policy)
Analyst comments:
  • SEDG -2.8% (downgraded to Equal Weight from Overweight at Barclays)
  • BFH -2% (downgraded to Sell from Neutral at Goldman)
  • CB -0.8% (downgraded to Neutral from Overweight at JP Morgan)

>>> US Gapping up

Gapping up
News:
  • BITF +9.3% (mines 411 BTC in September)
  • HOLI +4.3% (announces formal sale process as part of review of strategic options)
  • DFS +3.9% (disclosed Friday night that FDIC issued the previously disclosed consent order which addresses shortcomings in Discover Bank's compliance management system for consumer protection laws and related matters)
  • TLRY +3.3% (closes its all-cash previously-announced acquisition of eight beer and beverage brands from Anheuser-Busch (BUD))
  • VTRS +2.4% (announces agreements on remaining planned divestitures; Upon closing would achieve its original total target of a multiple above 12x on 2022 estimated adjusted EBITDA)
  • APLS +1.9% (announces that the U.S. Food and Drug Administration has approved the EMPAVELI Injector)
  • DXCM +1.8% (Solidifies Global Leadership in Continuous Glucose Monitoring With New Clinical Data Presented at EASD)
  • CABA +1.8% (receives FDA Clearance of IND Application for Treatment of Systemic Sclerosis with CABA-201)
  • BBVA +1.7% ( announces EUR1.0 bln share buyback)
  • HUM +1.5% (2024 Medicare Advantage Health Plan Offerings)
  • GNL +1.5% (declares dividend of $0.354 per share)
  • LI +1.4% (Sep deliveries)
  • XPEV +1.2% (Sep deliveries)
  • RCKT +1.2% (receives FDA acceptance of Biologics License Application with Priority Review for RP-L201)
  • DHR +1% (completes separation of Veralto Corporation)
Analyst comments:
  • PODD +3.4% (upgraded to Buy from Hold at Jefferies)
  • ZS +3.1% (upgraded to Overweight from Neutral at Piper Sandler)
  • MAC +1.7% (upgraded to Neutral from Underweight at Piper Sandler)
  • CLX +1.3% (upgraded to Buy from Neutral at DA Davidson)
  • LGIH +1.3% (upgraded to Neutral from Sell at BTIG Research)
  • FDX +0.8% (upgraded to Positive from Neutral at Susquehanna)

WSJ : Rivian’s Quest to Build the Ultimate Truck Burns Through Billions

Rivian’s Quest to Build the Ultimate Truck Burns Through Billions
The EV maker has struggled to keep production up and costs down

Rivian Automotive set out to build the ultimate electric vehicle for American consumers—a pickup truck with sports-car handling and a dizzying array of features.

Engineers gave the truck a beefy underlying metal frame for higher crash-test ratings and one of the most complicated suspension systems on the market for a smoother ride on- and off-road. It can go from zero to 60 miles an hour in 3 seconds. Rivian added pop-out flashlights stored away in the doors and a portable Bluetooth speaker.

All that comes at a cost. Rivian vehicles sell for over $80,000 on average. Yet they’re so expensive to build that in the second quarter the company lost $33,000 on every one it sold. That’s roughly the starting price of a base model Ford F-150.

When Rivian launched onto the electric-vehicle scene, industry watchers expected it to beat rivals to market and become the “Tesla of trucks.” Investors piled into its splashy market debut in 2021, when it raised nearly $12 billion in cash and became the U.S.’s largest IPO in years. For a short while, Rivian was worth more than Ford Motor and General Motors.

In two years, Rivian has blown through half of its $18 billion cash pile, in part because it struggled to master the nuts and bolts of manufacturing. While production is now growing and losses have narrowed, Rivian still loses money on its vehicle sales. In an industry known for narrow margins and tough competition, Rivian pays too much for parts and produces too few vehicles to cover its costs.

The company currently sells three models: the R1T pickup truck, the R1S SUV and an electric delivery van for Amazon.com. Rivian’s truck and its SUV, which share many parts, accounted for 83% of its August sales, according to Motor Intelligence data.

As of the end of June, Rivian had only built a total of around 50,000 vehicles, a fraction of what other car companies manufacture at a single U.S. factory in a year. Even with output increasing, Rivian’s factory in Normal, Ill., is operating at less than one-third of its build capacity. It aims to produce 52,000 vehicles this year.

Rivian’s share price is down around 70% from its IPO price of $78.

Founder and Chief Executive RJ Scaringe is rushing to slash expenses and slim down operations. He has said he is focused on reducing how much Rivian pays suppliers for parts, simplifying some aspects of the design and boosting production to move closer to profitability.

Losses have narrowed as Rivian produces more vehicles, but its cash burn continued at over $1 billion a quarter at the end of June.

Scaringe said the billions of dollars spent so far were a necessary part of the company’s growth. Company executives say Rivian aims to make a gross profit on its vehicles by the end of 2024.

“We’re competing to build something that’s truly better than all the alternatives, and to try to do that on a limited budget would be detrimental to us achieving our mission,” Scaringe said. Designing and manufacturing a vehicle with “supercar-level stiffness” has been expensive, he said, but is driving demand for Rivian’s trucks and SUVs.

Many new auto companies have stumbled in their attempts to turn an innovative idea into a vehicle that can be manufactured in large volumes. Billions of investor dollars plowed into such startups have evaporated in recent years.

Some, like fellow EV truck startup Lordstown Motors, have already gone bust. Lucid Group is struggling to stem heavy losses on sales of its first model, the luxury Air sedan. Fisker has only begun selling vehicles but has encountered launch delays and cut its production outlook.

Starting up a new factory and launching a new vehicle are two of the most fraught efforts in the car industry.

To limit losses, carmakers try to run their factories at full speed as quickly as possible. Companies take several years to design, engineer and practice manufacturing new vehicles so they can ramp up production in a matter of weeks or months.

It’s unusual for a car company to take as long as Rivian has to run its factory at full production, which in the auto industry usually means running a plant over at least two full shifts.

“You should be able to start to make money after three to six months,” said Mark Wakefield, managing director at advisory firm AlixPartners. “By the time you’re ramped up and running at rate, you’re making pretty good money.”

Even established automakers can struggle with new-vehicle rollouts, especially if they involve more advanced technology. GM has been slow to increase factory output of some new EVs, and Ford expects to lose $4.5 billion on its EV business this year. Unlike Rivian, those companies have other profitable parts of the business to absorb the financial impact.

The past few years have been a whirlwind for the 40-year-old Scaringe, who established Rivian in 2009 after receiving his Ph.D. in mechanical engineering from the Massachusetts Institute of Technology.

A Florida native who favors plaid shirts and black, square-framed glasses, Scaringe spent much of the 14 years since he founded Rivian overseeing a small team that operated in relative obscurity.

Rivian’s first vehicles had to be better in every way than the competition or no one would buy them, Scaringe said at a conference in 2019.

“It will be the best-driving truck or SUV in the world. It must be, because if it’s not, why would somebody pick us over a Ford or over a BMW?” he said.

Rivian set high ambitions for the design. Its complicated suspension system can raise and lower a vehicle’s height by 6 inches to optimize for handling, comfort and stability.

Engineers beefed up the underlying metal structure of the so-called skateboard chassis—a part named for its shape that serves as the base of the vehicle that houses the batteries, electric motors and other electrical components.

Engineering firms that have disassembled the truck say its design is overly complicated. The front end of the vehicle contains far more metal than is needed to provide stability and protect occupants in a crash, the firms say. The added metal means that while the R1T pickup is smaller than the Ford F-150 Lightning, its direct competitor, it weighs 685 pounds more.

The skateboard design is also complicated to assemble, requiring multiple layers of metal to slide into one another, say analysts and current and former employees. The tubes have to be welded together twice—once with a robot and then again by hand.

Sometimes, assembly workers had to hammer the pieces to get them to fit, said some of the employees.

“The more sophisticated the engineering is from day one, the harder it is to ramp up the manufacturing and get the vehicles out of the shop floor to fuel the cash flow,” said Frank Bunte, CEO of France-based manufacturing consultants A2Mac1, which has examined the R1T.

Scaringe said Rivian prioritized getting vehicles into production quickly over immediate profitability, which led to some cost issues. It aimed to refine the design afterward. Rivian plans to introduce a redesigned skateboard next year as part of its efforts to increase production volumes.

“We accepted that we’d have a lot of issues in the vehicle to start with,” he said. Rivian’s ability to redesign major aspects of its vehicles so soon after launching is a competitive advantage rather than a costly oversight, he said.

Other criticisms, like the weight of the vehicle and strength of the body, are unwarranted, he said, because Rivian intentionally built it to stand out with superior crash-test ratings.

Another factor driving costs was the company’s push to build components based on in-house designs, rather than buy less expensive parts off the shelf from established suppliers.

Among them were electronic control units, tiny computers that power certain vehicle functions. While these units usually handle multiple functions, from battery power management to steering control, Rivian built multiple units with different functions with the intention to consolidate them later in the rush to hit production deadlines.

In all, Rivian is paying $25,000 per vehicle more than the typical market rate for parts, according to an estimate from Wells Fargo analyst Colin Langan.

Rivian’s difficulties were compounded by pandemic-related shutdowns and supply-chain issues, including a shortage of semiconductors and lithium—a key ingredient in batteries—that drove costs higher and slowed production.

Rivian also decided to launch its three models in quick succession, which the company said has made it harder to work out production kinks.

Former employees say the process of fixing problems and cutting costs has been chaotic. They say Scaringe and other senior executives resisted suggestions to remove some of the less-essential perks in the vehicle, such as the in-door flashlight and Bluetooth speaker.

Scaringe said some of these changes would have made only a minor difference in vehicle costs and the company has made progress on its cost-cutting targets.

The company is making progress renegotiating supplier contracts that were signed in 2018 and 2019 for above-market rates, he said. Scaringe said that at one meeting with suppliers, “I stood on stage and said, you’re overcharging us by 41%.” Either the prices would come down or Rivian would find alternatives, he said.

Ultimately, Rivian has tasked its engineers with cutting up to $40,000 per vehicle in parts and production expenses, former employees say. Rivian declined to comment on the cost-cutting target, but Scaringe said the company doesn’t have to hit all of its targets to achieve gross profit by the end of next year.

Langan, of Wells Fargo, said he believed Rivian would have to both cut costs and raise prices to hit its targets, which will be difficult in this current environment. He estimates Rivian would have to sell its models at an average price of $96,000 per vehicle and run its factory flat out to achieve it.

Rivian last year raised prices up to 20% on some model configurations. Many competitors, including Tesla, have recently cut prices on their EVs.

Rivian has had some successes. It rolled out the industry’s first battery-powered truck and buyers and car reviewers have lauded its models’ features and performance on- and off-road.

Motor Trend described the R1T as “the most remarkable pickup truck we’ve ever driven,” and as of early November last year, Rivian had about 114,000 reservations. It has since stopped reporting this figure, saying it’s no longer an accurate measure of demand now that the company is producing more vehicles.

Sales volume was up 60% in the second quarter over the previous quarter, while revenue was up 69%, to $1.1 billion, helping to shrink per-vehicle losses.

Rivian no longer has the first mover advantage, and there are signs that demand is slowing for its pickup truck. Despite low production volumes, the company has excess inventory of some configurations.

The company is applying lessons learned from the first launches to a new generation of EV models, now being developed under its R2 line, company executives say. These smaller electric SUVs will be built at a new Georgia factory and sell at a lower price point.

Rivian is banking on them to deliver the sales volume needed to fuel future profits and says it has enough cash to last through 2025.

The models’ arrival was pushed back last year and is now expected in 2026.
>>> US Early premarket gappers

Early premarket gappers
  • Gapping up:
    • GNL +4.1%, TT +2.9%, VTRS +1.7%, BBVA +1.7%, LI +1.6%, HUM +1.5%, DHR +1.2%, EGO +1%, XPEV +1%, HOLI +0.9%, DWAC +0.9%, DXCM +0.8%, MGM +0.6%, LVS +0.5%
  • Gapping down:
    • IMAX -2%, NSC -1.2%, ARR -1.2%, TAK -1%, NVS -0.5%

FT : Renewable energy stocks hit hard by higher interest rates

Renewable energy stocks hit hard by higher interest rates
Sector falls 20% in two months, with some wind turbine shares weighed down by contracts struck at unfavourable prices

Renewable energy stocks have sold off sharply in recent months, underperforming fossil fuel companies by a distance, as the sector battles the impact of higher interest rates and contracts struck at unfavourable prices.

The S&P Global Clean Energy Index, which is comprised of 100 of the biggest companies in solar, wind power and other renewables-related businesses, has dropped 20.2 per cent over the past two months, putting it on course for its worst annual performance since 2013. The oil and gas-heavy S&P 500 Energy Index, in contrast, has added 6 per cent.

The declines, which come despite tens of billions of dollars in tax credits, subsidies and loans being offered by governments to green energy companies in the US and Europe, highlight how their finances are being squeezed.

Many companies have agreed long-term contracts, fixing the price at which they would sell energy, before developing the projects. They were then hit by a huge rise in costs as global inflation surged, while elevated interest rates have made their high levels of borrowing more expensive to service.

“There’s a dark cloud hanging over green stocks,” said Martin Frandsen, a portfolio manager at Premier Asset Management. 

“Two years ago we got a huge growth in commitments to hit net zero, which translated into a lot of investment opportunities. Then we hit this inflation wave and companies that locked in their [electricity] prices have been left very exposed,” Frandsen said. “The lag effect is hitting now.”


Solar power and wind turbine groups are among the hardest hit stocks. Swedish wind turbine developer Vattenfall in July said its costs had climbed 40 per cent. Korean manufacturer CS Wind is down 28 per cent since the start of August, while US-based wind and solar generator NextEra Energy on Wednesday announced a cut to its three-year growth expectations.

“Tighter monetary policy and higher interest rates obviously affect the financing needed to grow distributions” to shareholders at 12 per cent, said NextEra chief executive John Ketchum. Turbine manufacturer Vestas fell to a €130mn loss in the second quarter.

The threat of less generous tax credits and delays affecting the US manufacturers of turbine foundations have made life even harder for Danish developer Ørsted, whose shares have tumbled about 30 per cent since late August. Analysts at UBS estimate that sensitivity to higher interest rates could cost Ørsted between DKr5bn ($709mn) and DKr10bn ($1.42bn).

Some traders argue that renewable groups’ business models are poorly suited to a high inflation, high interest rate world.

“Most important is that a lot of these companies disappointed in their profitability,” said David Souccar, a portfolio manager at Vontobel Asset Management. “To support rapid growth you need to keep leveraging the balance sheet or issue equity. In a zero-rate environment, this formula worked. In a higher rate environment, it falls apart.”

“The whole value chain is in trouble,” said Renaud Saleur, a former trader at Soros Fund Management who now heads Anaconda Invest and who is shorting wind stocks Ørsted and Vestas. Shorting means betting on a lower share price.

“The contracts signed for offshore [wind] will be heavily lossmaking for a long time until the different governments realise that they need to give $80-$100 per MWh and not $30-$40.”

European solar module manufacturers last month warned that a flood of cheap Chinese alternatives are pricing local companies out of the market. “Big supply-demand imbalances have been building up over the past year or so,” said Fiona Manning, an emerging markets portfolio manager at Premier Miton. 

Yet manufacturers in China, which dominates the solar supply chain, are nursing heavy share price losses of their own, having been caught up in this year’s sell-off in the country’s equity markets. Since January, S&P Global Clean Energy Index constituents Sungrow Power Supply, JA Solar Technology and Risen Energy have fallen about 32 per cent, 33 per cent and 44 per cent respectively.

The median company in the global solar panel manufacturing sector trades at an enterprise value to ebitda (earnings before interest, tax, depreciation and amortisation) multiple of about nine times, according to BloombergNEF. That is down from about 16 times a year ago.

However, Anaconda’s Saleur said he was no longer shorting solar companies and had bought in to some stocks in the sector. “We believe the large part of the value destruction is over,” he said.

FT : Trade in ‘fear gauge’ at high as investors hedge amid fragile markets

Trade in ‘fear gauge’ at high as investors hedge amid fragile markets
Vix trading is headed for a record amid uncertainty over rally and the impact of rising rates on economic growth

Trading in options tied to the Vix volatility index — popularly known as Wall Street’s “fear gauge” — is on course to hit a record volume this year, as cautious investors look to protect themselves from the risk of a sudden stock market reversal.

So far this year, investors have traded an average of 742,000 options tied to the Vix each day, according to exchange operator Cboe, up more than 40 per cent year on year and above the full-year record of 723,000 set in 2017.

The Vix shows expectations of volatility in the S&P 500 over the next month, and the bulk of the increase in trading this year has come from investors buying call options — a type of derivative that would pay off if the index spikes higher.

The jump reflects the growing need for investors to hedge their positions amid a fragile stock market rally. The S&P 500 has risen 12 per cent this year, but gains have been concentrated in a few large tech groups and investors continue to grapple with uncertainty around high interest rates and the impact on economic growth.

Charlie McElligott, an equity derivatives strategist at Nomura, said the rally had forced even sceptical investors to increase their exposure to stocks after a sell-off in 2022, but “the fact of the matter is there are still a number of [risks] outstanding”.

“Now that people have equity exposure back . . . and cash coming off the sidelines, you need to hedge again.”

Vix options have been particularly popular because the index has been unusually low for most of the year, increasing the chance of a large payout if it suddenly jumps. The Vix has a long-term average of around 20, but so far in 2023 it has averaged around 17, and dipped as low as 12.7 earlier in September. Last year the average was almost 26. 

“When the Vix is in the mid or low teens, a doubling or even tripling of volatility from there is a lot easier,” said Mandy Xu, Cboe head of derivatives market intelligence. “When it was at 25, doubling that would take a once-in-a-generation type event.”

The growth in Vix trading this year marks a sharp turnaround after several years of anaemic volume growth and increasing questions over the index’s effectiveness and relevance. 

Although the index tends to rise when stocks fall, the correlation is not as strong if markets grind slowly lower as they did in 2022, which disappointed investors who had relied on it as a hedge against a downturn. Meanwhile, an increasing percentage of investor activity is concentrated in extremely short-term options, which are not captured by the main Vix index.

Several firms that used to play important roles in the Vix space have also collapsed since the last time trading volumes were so high. McElligott cautioned that this could make it harder for the banks that sell Vix options to investors to hedge their own positions, leaving them potentially exposed in a crisis.