WSJ : Ryan Holmes: Why Twitter, Facebook and Apple Suddenly Want to Handle Your

RYAN HOLMES: As trends go, this one is hard to miss. In the space of a recent week, both Twitter and Apple made major announcements about payments — i.e. how we buy things online and in real life. Twitter has just rolled out a “buy” button, which appears alongside certain tweets and allows users to make purchases directly through Twitter with just a click or two. Apple, meanwhile, unveiled Apple Pay at its iPhone 6 event. The new mobile wallet app will allow users to “tap and pay” with their iPhones at more than 200,000 brick-and-mortar stores in the U.S., as well as execute online purchases.

At the same time, Facebook has been beta-testing its own “buy” button, which shows up next to posts and ads, allowing users to complete a purchase without ever leaving the network. And Google, of course, has been trying to get its tap-and-go Google Wallet app to catch on for years. (Adoption has been stymied by the fact that Apple won’t allow its hundreds of millions of iPhone users to access the app, among other reasons.)

So what’s behind this race to payments and why do social networks now want in?

On one level, in-stream purchasing on Twitter and Facebook represents the next logical step in making it easier for you and your money to part ways. The advent of credit cards freed consumers from the obligation of actually having cash on hand and heralded a new era of impulse shopping. Amazon’s famous “1-click” checkout took this a step further: Once your credit card was on file, just about anything under the sun could be bought and shipped with the press of a mouse. But you still had to go actually go to the Amazon website… and there lies the friction.

The logic behind introducing e-commerce into social networks is that you’re already there anyway, chatting with friends, browsing the latest trends, sharing photos and videos, etc. You don’t have to go to a special site to do your buying; the products come to you. And you don’t have to click away to another site to consummate the purchase — once your payment details are on file with Twitter or Facebook, purchases are a tap or two away. Then it’s back to cat GIFs and catching up with friends.

It’s also important to note that Facebook and especially Twitter are real-time media, perfect for short-term promotions and special deals tied in with fleeting trends. With time-sensitive offers literally streaming by, consumers may well be inclined to act quickly and seal the deal, forgoing the obsessive comparison shopping that characterizes lots of Internet transactions.

Selling directly on social media has another key benefit: Retailers and advertisers get instant confirmation of the impact of their social media marketing efforts. A recent Wall Street Journal report noted that while social media marketing budgets are expected to more than double in the next five years, only 15% of marketing executives can show the quantitative impact of spending. Connecting individual Tweets and Facebook posts with actual purchases has thus far proven to be a huge analytical challenge. But with the advent of buy buttons and in-stream purchasing, concrete revenue and conversion figures can be attached to social media efforts in a way that hasn’t been possible until now.

But what’s in it for the social networks themselves and — more broadly — for Apple and other makers of mobile wallet apps? For now, Facebook and Twitter are testing their buy buttons with a select group of merchants, in many cases free of charge. It’s foreseeable, however, that they’ll start charging a fee for sellers using the feature or even set up a revenue sharing system (akin to Apple’s iTunes model). The buttons — with their promise of rich data on buying patterns — may also prove useful in luring more advertisers to the networks and boosting overall revenue from ad sales.

It’s also critical to note that, to facilitate repeat transactions, both Facebook and Twitter will store users’ credit card information. Twitter, for instance, is partnering with payments processor Stripe to handle transactions. Facebook’s new Autofill feature (a kind of Facebook Connect for credit cards) allows users who enter their credit card info to check out not only on the network but with 450,000 e-commerce merchants across the web. Apple meanwhile already has an astonishing 800 million credit cards associated with iTunes accounts. The new Apple Pay app encourages users to link additional American Express, Mastercard and Visa cards to their accounts. And here’s where things really get interesting.

Right now, Apple, Twitter and Facebook are all content to act as middlemen more or less, connecting consumers with other parties who process payment — from credit card companies to online services like Stripe and PayPal. These processors, of course, skim a healthy chunk off the top of all transactions — around 2% for most credit cards; 2.9% for Stripe. In the U.S. alone, credit card interchange fees — generally borne solely by merchants and vendors — represent a $40-billion-a-year industry.

But who says Apple, Twitter and Facebook have to remain on the sidelines while all this money changes hands on their sites and services? Indeed, it’s already been revealed that Apple will get a per-transaction fee from card-issuing banks each time iPhone users pay with the Apple Pay app. This fee will come directly from the banks, rather than from merchants or consumers. (Banks seem content to part with this extra fee because of the additional business Apple Pay will bring their way.)

But why stop there? Should Apple Pay or in-stream purchasing in Twitter and Facebook truly catch on, it’s foreseeable that these companies will themselves start to act on some level as payment processors. By elbowing out credit card companies and their online equivalents, and possibly offering merchants more attractive fees and terms, Apple and these networks could theoretically have a much bigger chunk of the extraordinarily lucrative payments pot.

This may sound a bit far-fetched, especially considering that Apple Pay’s launch is predicated on partnerships with Visa, MasterCard and American Express. Without these credit card companies on board – willing to let cardholders access their cards through the app — Apple Pay would be a nonstarter. But Apple has embraced more than few strategic partners throughout its recent history only to let them loose once their purpose had been served. Think back to how restricted the Skype calling app was when the original iPhone was unveiled in 2007, in all likelihood due to Apple’s initial partnership with exclusive carrier AT&T. By contrast, the new iOS 8 operating system allows Wi-Fi calling, enabling users to make standard voice calls over a Wi-Fi network and bypass the carrier entirely. The game has changed. I predict that this same playbook is going to be used with payment partners. Expect to see an Apple finance arm in the future.

Nor does the payments arms race have to end there. Google and Microsoft may well dive further into the payments space in the years ahead. Might they perhaps acquire Square, or even Twitter, as a way to connect mobile, social and payments? The service fees charged to merchants are only one potential revenue stream here. The rich pool of data on consumers’ buying habits collected from these transactions may prove equally as valuable, with advertisers and retailers willing to pay top dollar for insight on how to better target buyers.

FT L:No hard landing yet in China (Gavyn Davies)

China’s economic rebalancing has been themain downside risk to global economic activity in 2014, and will probably remain so for the foreseeable future. The industrial production figures for August were the weakest seen since the 2008-09 recession, and they were followed by a statement from finance minister Lou Jiwei to the effect that there would be no change in economic policy “in response to one indicator”.
This echoed Premier Li Keqiang’s recent speech at the summer Davos meetings, which indicated broad satisfaction with the overall thrust of policy. “Just like an arrow shot, there will be no turning back”, he promised.
The possibility of a clash between a slowing economy and a Chinese administration that appears implacably set on a pre-determined course was not what the markets wanted to hear. Many western investors have long been predicting a hard landing for China, and do not need much persuasion to believe that it is finally at hand. But recent data do not suggest that it is happening yet.
The collection of economic activity data published for August were certainly on the weak side. Apart from the industrial production figures, which are normally by far the most reliable single guide to overall activity and GDP, money supply growth was subdued, and there was a sharp fall in electricity consumption. Wei Yao, an analyst at Societe Generale, and a pessimist on China, summarises the data as follows:
The shadow banking system continued to delever, with both trust loans and undiscounted bankers’ acceptances (BAs) showing outright contraction for a second month in a row. The shrinking stock of trust loans is particularly dangerous to property developers and as such to residential investment, whereas dwindling BA financing has probably affected commodity financing and contributed to weak commodity imports.
There is no doubt that the property sector is now undergoing a sharp correction, and that weak demand for commodity imports is having global effects on commodity prices and inflation pressures. To a large extent, this property correction is policy induced, but when it showed signs of getting completely out of control in February, it brought about a significant easing in monetary conditions.
This, apparently, was not considered to be a major change of strategy, just a minor mid-course adjustment. But it demonstrated that the authorities had opted for a long, drawn out economic rebalancing, not a quicker correction that would take GDP growth below the Premier’s 7.5 per cent target for 2014 as a whole.
This still seems to be the case. The “unchanged strategy” described in recent statements indicates a determination to maintain the major economic reforms outlined in last year’s Third Plenum, but only at a pace consistent with the official growth targets.
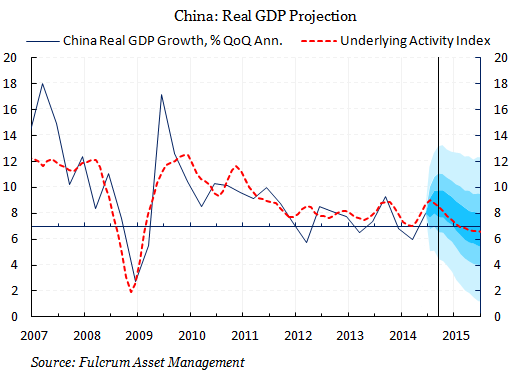
Even taking account of recent weaker data, it seems that the GDP target for 2014 will still be achieved. The HSBC PMI survey in the manufacturing sector published today did not confirm earlier fears that the economy is falling off a cliff. Furthermore, the Fulcrum “nowcasting” factor model of economic growth in China carries the same message. The model, estimated by my colleagues Juan Antolin Diaz and Ivan Petrella, combines all of the available data into a single index of Chinese activity. It has been successful in tracking major and minor inflection points in activity in real time:
Note that the activity indicator rose from about 7 per cent growth in February to a peak of about 9 per cent in mid year, but it has now dropped closer to 8 per cent. The forecasts produced by the model, which are statistical rather than economic in nature, foresee the activity index dropping further to about 7 per cent by year end, and then edging down to about 6.5 per cent (the model’s latest interpretation of the long term underlying growth rate for China) during next year.
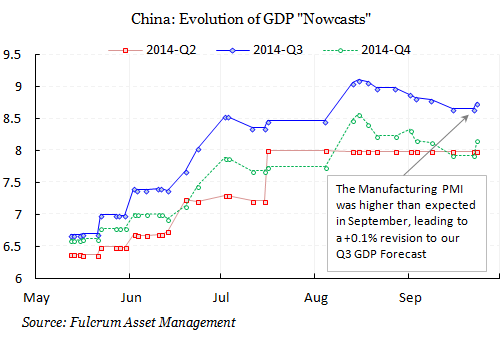
The model also produces estimates for GDP data for specific quarters, and enables us to track these estimates as they evolve through time:
Note that the model indicates that GDP growth in 2014 Q3 has been running at an annualised quarter-on-quarter rate of about 8.7 per cent, which is a little below the highest estimates made earlier in the quarter. It also estimates that the 2014 Q4 figure will be around 8 per cent. This is slower than the predicted Q3 out-turn. Nevertheless, if we translate these quarterly annualised growth rates into a possible out-turn for the entire calendar year, it would be very close to Premier Li’s 7.5 per cent target.
It has taken a lot of fine tuning by policymakers to ensure that growth can attain this figure as the property sector adjusts. It is still very possible that they will eventually lose control of the situation, and suffer a much harder landing than they currently envisage. But that does not seem to be happening yet.

>>> Fed's Bullard (moderate, non voter): Still sees first rate hike towards the


Fed's Bullard (moderate, non voter): Still sees first rate hike towards the end of Q1 
- Concerned that asset bubbles may arise if the Fed moves too slowly and mechanically when tightening policy
- Growth looks good, with the exception of Q1 
- Would be natural to drop the 'considerable time' language at the October meeting 
- Expecting growth to exceed 3% in 2H of 2014 and also in 2015

(BFW) *BULLARD: MORE NATURAL TO DROP CONSIDERABLE TIME AT OCT. FOMC


BFW 09/23 14:33 *BULLARD STILL SEES FIRST TIGHTENING AT END OF FIRST QUARTER
BFW 09/23 14:33 *FED'S BULLARD SAYS UNEMPLOYMENT BEEN A POSITIVE SURPRISE
BN 09/23 14:33 *BULLARD SAYS GROWTH LOOKS `VERY GOOD' OTHER THAN 1Q
BFW 09/23 14:33 *FED'S BULLARD SPEAKS TO REPORTERS IN ST. LOUIS
BFW 09/23 14:33 *FED'S BULLARD SAYS HE SUPPORTED FOMC STATEMENT ON SEPT. 17
BFW 09/23 14:33 *BULLARD SAYS PREMATURE FOR FED TO REMOVE "CONSIDERABLE TIME"

*BULLARD: MORE NATURAL TO DROP CONSIDERABLE TIME AT OCT. FOMC
2014-09-23 14:33:36.132 GMT

--BRENDAN MURRAY

-0- Sep/23/2014 14:33 GMT

(CTX) Three jihadist suspects arrested at Paris airport


Three jihadist suspects arrested at Paris airport
2014-09-23 14:27:16.804 GMT


Sep. 23, 2014 (Xinhua) -- French police on Tuesday arrested
three men at Paris Orly airport, suspected of joining Syrian
insurgents in 2013, local media reported.
The three suspects, among them the brother-in-law of
Mohamed Merah, who killed seven people in southern France in
2012, have been placed under custody, the news channel BFMTV
said.
According to the report, the suspects joined Syria in April
2013 and have been arrested by Turkish authorities at the end of
August on their route to home.
Interior ministry's data showed more than 900 French
nationals and residents joined combats in Syria, among which 36
have been killed and 118 others returned home.
Under the anti-jihadist plan, France said it would ban
travels to conflicts zones where nationals would join fighters
and monitor those who returned home after a stay in Syria.
In the meantime, to curb the alarming number of radicalized
young French that joined fighters in Syria, the French
government has pledged to boost cybersecurity, stay in close
contact with jihadists' families and deport immediately foreign
nationals who are involved in Jihad cells.

Copyright 2014 XINHUA NEWS AGENCY

-0- Sep/23/2014 14:27 GMT

Fwd:>>> WSJ : NATO Says Russia Withdrawing Troops From Eastern Ukraine.

it looks like this news I sent 12mnts ago hitting the tape now

From: LAURENT CHEKROUN () At: Sep 23 2014 16:09:48
Subject: Fwd:>>> WSJ : NATO Says Russia Withdrawing Troops From Eastern Ukraine.
WSJ [Reg]: NATO Says Russia Withdrawing Troops From Eastern Ukraine.
very important especially after Poroshenko earlier said about proper de-escalation.
So local media comments about potential lift of some sanctions on Sep 30 may actually come true

WSJ :Rouhani Criticizes Allied Bombing in Syria, Says Iran Should Take Lead

UNITED NATIONS—Airstrikes by the U.S. and a group of Arab allies against Islamic State targets in Syria are illegal and constitute an attack on the country, Hassan Rouhani, the president of Iran, said Tuesday.
Mr. Rouhani said military action could only be justified if authorized by the United Nations Security Council or if the measures were conducted with the consent of the Syrian government.
"These bombings do not have any legal standing so we can interpret them as an attack," he told journalists on the fringes of the United Nations General Assembly.
Mr. Rouhani condemned Islamic State and described them as "barbarians," but said Iran should lead any coalition in the fight against the group that has seized control of swaths of Syrian and Iraqi territory.
    The Iranian president seemed eager to express Iran's willingness to combat the militant group, but he signaled no willingness to work with the U.S. government in the task.
    "There is no cooperation between Iran and the United States but we are extremely serious about combating extremism."
    Iran has been a long-standing ally of Syrian President Bashar al-Assad and Mr. Rouhani noted that Iran has been fighting Islamic State extremists in the region alongside Syrian forces.
    Also, Mr. Rouhani expressed optimism that a final deal on Iran's nuclear program with the U.S., Russia, China, the U.K., France and Germany could be reached before the deadline set in an interim agreement earlier this year.
    "There are still differences between the two sides but I do believe in the next two months we can reach an agreement."
    The continuing differences go beyond the issue of the number of centrifuges Iran will be allowed to continue operating, he said, and included disagreements over the time-frame of the agreement and over how it will be executed.
    Mr. Rouhani added that this week would be an important one in the nuclear talks. He is scheduled to address the U.N. General Assembly later this week and is expected to hold meetings with diplomats from various countries, though he won't meet PresidentBarack Obama when he visits the U.N. tomorrow.