>>>Tom Tom : +2.8% VZ/Telematics Deal + Uber Investing in Mapping Business

2 news that can explain interst in Tom Tom today...
- Uber to pour $500m into global mapping project - FT - http://www.ft.com/cms/s/0/e0dfa45e-5522-11e6-befd-2fc0c26b3c60.html#axzz4G3uPLjGG I believe it could be too late to invest in mapping business to build its own data, even if they many drivers than can potentially helped them...Uber is not waze...so don't think it will be the good strategy.
- Verizon Agrees to Buy Fleetmatics in $2.4 Billion Deal


I have been talking for months (even years) fo this story and still think that it will make of lot of sens of this one to be taking over...45% of teh capital is still own by 4 shareholders founders of the company, and still believe that there many buyers out there...

stock was trading around the 6 a month a go, rallied almosxt 30% from there, but still down 33% YTD...

have a look.

Laurent

>>> US Gapping Down

Gapping down

In reaction to disappointing earnings/guidance: SOHU -4.7%, NSP -3.2%.

M&A news: SCTY -6.4% (confirms definitive merger agreement with Tesla (TSLA), agrees to be acquired for $25.37/share in stock), RIG -4.7% (RIG to acquire Transocean Partners (RIGP) for 1.1427 shares of RIG stock).

Select European financial related names showing weakness following stress test results: SAN -3.3%, RBS -3.1%, BCS-2.7%, DB -2.2%, HSBC -1.4%.

Other news: ADMA -42.7% ( receives Complete Response Letter from FDA for pending Biologics License Application), KERX-30% (withdrawal of guidance on supply interruption of Auryxia tablets; also reported earnings ), TKAI -12.7% (to reduce workforce by ~60%), GRPN -2.5% (no news today, pulling back following 30% gain last week) MCRB -2.1% (continued volatility), CNI -0.3% (Canadian Natl Rail discloses that it will repurchase common shares under three specific share repurchase programs ; will form part of the previously announced Normal Course Issuer Bid for up to 33 mln shares ).

Analyst comments: BUD -1.7% (downgraded to Neutral from Positive at Susquehanna).

>>> US Gapping Up

Gapping up
In reaction to strong earnings/guidance
: TOPS +55%, WG +22%, CACC +2.7%, DO +1.7%.

M&A news: FLTX +39.7% (to be acquired by Verizon (VZ) for $60/share in cash, or ~$2.4 bln), PN +33.1% (Patriot National Board to consider an offer for a potential transaction with Ebix (EBIX), CZR +14.5% (Chinese consortium to buy Caesars Interactive Entertainment's social and mobile games business Playtika for $4.4 bln in cash).

Other news: IONS +23.3% (Phase 3 trial evaluating nusinersen in infantile-onset SMA met the primary endpoint; as a result, Biogen paid Ionis a $75 million license fee ), HRTX +20.3% (announces preliminary, 'positive', top-line efficacy results from two Phase 2 clinical studies of HTX-011 for the management of post-operative pain in patients undergoing bunionectomy and inguinal hernia repair), KGJI +17.3% (sells all of its interest in the Shanghai Creative Industry Park to Wuhan Lianfuda Investment Management for ~$ 171 mln), DRYS +17.1% (following TOPS earnings/move), SCYX +16.3% (announces its Phase 2 study evaluating SCY-078 as a treatment in patients initially treated with IV echinocandin therapy for invasive Candida infections met all primary objectives), ESEA +14.9% (following TOPS earnings/move), SPHS +5.1% (recent momentum name, not seeing anything new today), SPU +5.2% (recent momentum name, not seeing anything new today), MGT +5% (recent momentum name, not seeing anything new today), IPI +4.7% (light volume; obtains further waivers of certain covenants under its senior notes and its credit facility until September 30, 2016; also reaches agreement in principle with holders of its senior notes regarding revised terms), ESI +3.5% (light volume; Yude Zhang increases active stake ), SVU +0.2% (Several PE firms are preparing offers for Suvervalu's Save-A-Lot unit, according to Reuters).

Analyst comments: ETSY +3% (initiated with a Buy at Citigroup; tgt $14).

>>> Lumo Run’s new jogging sensor launches today – here’s how it stacks up

Lumo Run’s new jogging sensor launches today – here’s how it stacks up

Lumo officially launches its smart running sensor, Lumo Run, today, and we took it for a spin around the park to tell you how it compares to other jogging tech out there.

TechCrunch first caught wind of Lumo’s smart pants with the running sensor last October. It was a breakout product from its posture trainer Lumo Lift and a first step into both connected garments and the running industry. You can check out our video review with Lumo co-founder Monisha Perkash here.
Lumo’s pants needed the sensor to go in a special pocket to work when we last caught up with the company, but now Lumo has separated the sensor from the pants so you can take a run with the tech in any pants you want.
How it works:
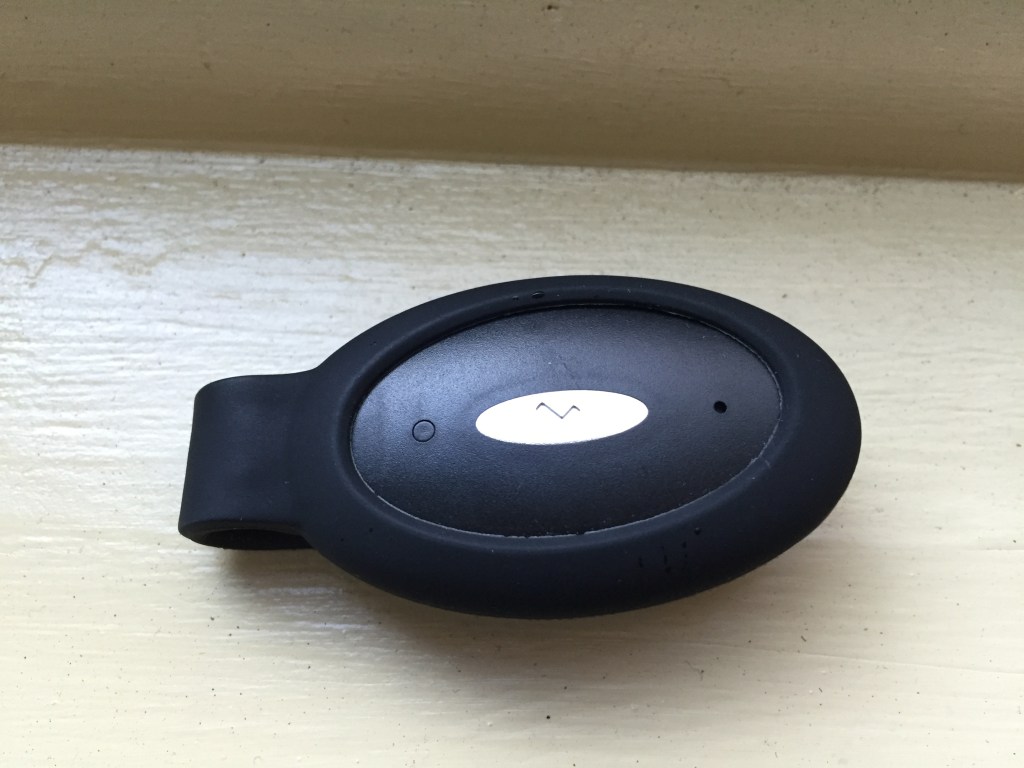
Lumo Run’s sensor works by placing it in a special clip provided and then snapping the clip onto the back of your running pants. Make sure the sensor is powered up first before beginning. You’ll know it’s ready when a little light at the bottom of the sensor flashes green.
Lumo recommends placing the part of the sensor with the USB plug toward the bottom of the clip for more accurate results.The clip is pretty tight when you first get it so it may take some maneuvering to get the sensor inside. Placing the USB connector at the bottom also makes it more convenient to slip off the clip and plug in again.
You’ll then download the Lumo Run app and set up a profile. The app on your phone will locate your sensor if everything is set up properly, and Lumo will begin to guide you on a 10-minute test run to find out all your weaknesses.
The app told me in a delightful Australian woman’s accent that I was moving my hips too much from side to side while running and I needed to work on cadence. Perkash, an avid runner herself, told me cadence, or your running stride, is one of the most common things runners need to work on to prevent injury and improve their form. It can also help you run faster.
A little bell will ding on the app if you are within your cadence goals. Mine was for 170 strides per minute, but elite runners usually get around 180-200 strides per minute. The app knows what you need to hit based on your height, weight, gender and your current fitness level.

How it compares:
Lumo Run tracks distance, pace, and running goals in a similar manner to many other fitness devices and apps. However, the main focus is all on improving the way in which you run.
Your form is important for preventing injury, as most any running expert will tell you. Poor form leads to all sorts of problems with your back and knees and could mean the difference in race time, distance and how much you’ll enjoy the activity down the road.
Perkash told me she actually had bad knees before using Lumo Run but claims the problem went away after using the device.

The device also deviates from other fitness trackers like the Apple Watch, Jawbone or Fitbit in that it does not track such as the calories you burned during activity, your sleep cycle, or overall steps throughout the day – basically Lumo Run snips out any data not pertaining to posture.
If calories burned is important to you like it is to me, you could do what I did on my run and combine Lumo Run with the Moves app or RunKeeper to get your overall mileage with the calories and how much of that was spent running versus walking.
However, posture is something very few running apps and devices take into account and not something more popular devices like the aforementioned Jawbone and Fitbit even consider.
Glance, a running watch by At a Glance, is one of the few other fitness wearables out there aiming to improve your running form while tracking your distance, calories burned, steps and sleep quality. I have not personally reviewed a Glance so I don’t know how the experience compares, but you can purchase one on Amazon for
I have not personally reviewed a Glance so I don’t know how the experience compares, but you can purchase one on Amazon for $129.99. The Lumo Run sensor goes for $99.99 online and the men’s shorts and women’s capris with the sensor clip will round you up to $200.
Lumo’s running app will also guide you through improvements as you run and provides coaching videos to show you how to improve your run over time. You can set goals and let the app
Some of the other features included with Lumo Run:
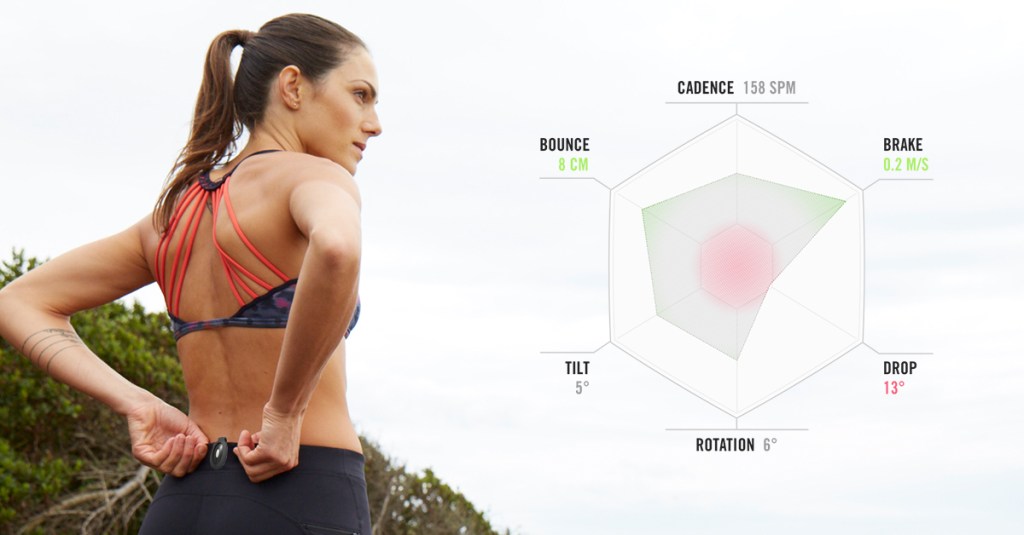
  • lab-grade biomechanic measurements – get feedback on your running bounce, cadence, braking, pelvic rotation, and drop.
  • Feedback using an artificially intelligent coach to help you continue to improve over time
  • Post-run summaries
  • Up to 20 hours on a single charge (during running time)
  • Run phone free – go out on a run with the sensor and leave your phone at home, then come back to wirelessly sync the data and get updates about your running form.
  • Waterproof and machine washable
Room for improvement
Lumo Run offers something an app cannot, but it’s not without competition – and the main competitor, Glance, incorporates a lot of other features like calories burned, steps, and sleep quality data for not a whole lot more money. But that’s not to say Lumo couldn’t add those features in.
When and why I would buy
Overall I thought Lumo Run’s sensor was pretty handy and has the potential to prevent serious injury. It’s also cheaper than hiring a running coach to watch your every stride like elite athletes do. Like almost every wearable on the market, I’m not sure I’d use it over time but it’s not a bad price for the data.
As a not-very-hardcore runner, I would be willing to buy it with a few more additions. However, the sensor would be a definite and immediate buy for me, if I were about to run a marathon. The injury prevention promise and improvement in overall time would be enough for me to make a $100 investment and given my overall experience with the product, I would recommend it.
NY Post : Hedge fund tied to kickback probe used ‘checkered’ valuation firm

Hedge fund tied to kickback probe used ‘checkered’ valuation firm

Platinum Partners, which is under federal investigation over whether it inflated the value of its investments, turned to an outside firm with a checkered past to sign off on its methods, The Post has learned.

Until this year, the $1.3 billion hedge fund, which is at the center of a kickback scandal and a fraud investigation, used Sterling Valuation Group as its valuation firm, company documents show.

The same firm also approved investment valuations for Alphonse “Buddy” Fletcher, whose hedge fund collapsed in 2012. A report by a court-appointed bankruptcy examiner found that Fletcher’s fund had inflated the value of investments and bore “many of the characteristics of a Ponzi scheme.”

Prosecutors are now probing whether some of Platinum’s investments were known to be worth less than what the fund told investors, said a source familiar with the investigation by the Brooklyn US attorney. Platinum has said it stands by its valuation methods.

Sterling, run by Murray Grenville, declined to comment. The New York-based firm hasn’t been accused of wrongdoing.

Platinum is liquidating its three funds after fund manager Murray Huberfeld was arrested and charged in an alleged scheme to bribe a union official to invest $20 million in Platinum.

Before an FBI raid in June, Platinum, run by Huberfeld and Mark Nordlicht, had posted some of the most eye-popping returns in the hedge fund business — at one point showing 119 out of 120 months of gains in one of its main funds, according to investor documents.

Those impressive returns came from esoteric and hard-to-value investments such as life insurance policies of people who were on the brink of dying and risky energy bets.

Since 2008, when it was revealed that Bernie Madoff’s $50 billion Ponzi was audited by a little-known firm operating out of a strip mall, investors in hedge funds have pushed the industry to add another layer of due diligence.

“Accountants are basically medical examiners, they’re performing examination on corpses,” said Jason Voss, content director at the CFA Institute. Investment valuation firms are like physicians and are “interested in the ongoing health” of the company.

It isn’t clear how much independent work Sterling performed to corroborate the values of Platinum’s investments.

“We have not independently verified and have assumed the accuracy and completeness of the information supplied to us by the fund with respect to the borrowers, issuers or investments described herein, and the fund, and do not assume any responsibility with respect to it,” Sterling wrote to Platinum CFO Joseph SanFilippo in a June 6, 2014 letter.

SanFilippo leads Platinum’s valuation committee, which is responsible for valuing Platinum’s assets.

Platinum spokesman Montieth Illingworth declined to detail how Sterling values the hedge fund’s assets except to say it “provided an industry standard valuation within the standards and practices of its profession.”

This year Platinum switched firms and is using Alvarez & Marsal Valuation Services, which declined to comment. The transition was “entirely unrelated” to the investigation, Illingworth said.

“Our valuation needs grew significantly and became more complex,” he said. “The new firm was more suited to meeting those needs.”

>>> Tesla / Solarcity : Agrees to merge with Tesla for $25.37/shr; total deal va

Agrees to merge with Tesla for $25.37/shr; total deal valued around ~$2.6bil

On July 31, 2016, Tesla Motors, Inc. (Tesla), SolarCity Corporation (SolarCity) and D Subsidiary, Inc., a wholly owned subsidiary of Tesla (Merger Sub), entered into an Agreement and Plan of Merger (the Merger Agreement). The Merger Agreement provides for the merger of Merger Sub with and into SolarCity (the Merger), with SolarCity surviving the Merger as a wholly owned subsidiary of Tesla. Capitalized terms used in this Current Report on Form 8-K but not defined herein shall have the meanings ascribed to them in the Merger Agreement.The Board of Directors of Tesla (the Tesla Board), with Messrs. Elon Musk and Antonio Gracias recusing themselves, determined that the transactions contemplated by the Merger Agreement, including the Merger and the issuance of shares of Tesla common stock in connection with the Merger (the Share Issuance), are fair to, and in the best interests of, Tesla and its stockholders, approved the Merger Agreement and the transactions contemplated by the Merger Agreement, and recommended that the stockholders of Tesla approve the Merger and the Share Issuance.Pursuant to the terms and subject to the conditions set forth in the Merger Agreement, at the effective time of the Merger (the Effective Time), each share of SolarCity common stock, par value $0.0001 per share (the SolarCity common stock) issued and outstanding immediately prior to the Effective Time (other than shares of SolarCity common stock owned by SolarCity as treasury stock or owned by Tesla or Merger Sub, which will be cancelled) will be converted into the right to receive 0.110 (the Exchange Ratio) shares of Tesla common stock, par value $0.001 per share (the Tesla common stock).

(UBS) European Luxury : Can the Chinese fire for luxury (29/07)

UBS Evidence Lab suggests Chinese luxury consumption can reaccelerate
The Chinese consumer has underperformed expectations in 2016 declining high single digit globally we estimate. We conducted the second wave of our UBS Evidence Lab survey of 1,094 Chinese consumers (first wave H2 15) and conclude that whilst there are some structural influences behind the weakness, attitudes to luxury remain optimistic suggesting some cyclicality is also at play. We would therefore expect to see an eventual recovery of Chinese consumption which supports our forecast for the sector to return to 4% organic growth in 2017 after a decline of –2% this year. The market is already attributing less of the sector's share prices to long term-growth than history with this standing at 18% today versus 24% in 2013. This looks reasonable but short term negative earnings momentum could still weigh and we sit c.5% below consensus in 2016. We prefer companies where we believe there is good brand momentum such as Kering and Moncler or a restructuring opportunity such as Burberry. LVMH remains our top defensive pick in a challenging market.

How much of the current Chinese luxury consumer weakness is structural?
Our UBS Evidence Lab survey shows that there may be structural factors at play such as consumers looking to spend less time shopping abroad and increased Chinese import restrictions. However, there are also cyclical elements such as the unwind from the FX driven international spending boom last year. The consumer remains optimistic about
their personal finances with attitudes to luxury positive. Responses also suggest that they are looking to increase spend allocation towards luxury relative to six months ago.

Soft luxury: Gucci and surprisingly Prada have gained ground on Louis Vuitton
Whilst Louis Vuitton remains the highest ranked brand with the consumer Gucci and also surprisingly Prada have improved relative over the last 6 months. Elsewhere Burberry and Moncler have also improved whilst Tod's and Hugo Boss have weakened.

Hard luxury: consumer demand surprisingly positive but destocking outweighs
Watches have been weak due to the overhang of stock in the channel post the government's anti-extravagance campaign. Survey responses continue to show surprisingly robust demand from the consumer outside of this albeit we do not yet expect this to outweigh the destocking. Jewellery shows a more upbeat outlook.

(Makor) - SABMILLER / AB INBEV - Our thoughts following the SAB board recomm

August 1, 2016 


MAKOR - SABMILLER / AB INBEV - Our thoughts following the SAB board recommendation of the cash consideration


We note the statement from the SABMiller board that they are unanimously recommending the cash consideration and that SAB shareholders vote in favour of the UK Scheme at the UK Scheme Court Meeting and in favour of the SABMiller Resolutions at the SABMiller General Meeting. 


As per the Co-operation Agreement (dated 11 November 2015), the voting requirements are as follows, but we note, that the SAB board have also today announced their intention to propose to the UK Court that Altria and Bevco be treated as a separate class of shareholders and allow other SABMiller shareholders to vote on the revised £45 offer separately:


(i) UK Scheme Court Meeting – 75% of SAB shares present and voting either in person or by proxy provided that there is a quorum of at least 50% of outstanding SAB shares attending and voting at the meeting. 


(ii) SABMiller General Meeting – 75% of SAB shares present and voting (the SABMiller General Meeting will be held immediately after the UK Scheme Court Meeting. 


It remains undecided if the UK court will determine that the vote should be split into two classes, and, if a decision is made to split the vote, whether the voting threshold will then be 75% of disinterested shareholders (provided that a majority of disinterested SAB shareholders - excluding Altria and Bevco - are present and voting at the meeting).


We spoke to the Takeover Panel who said that the decision to split the vote is a decision for the Court. He believes that the shareholder voting requirement is likely to be the same for both classes of shares, if a decision is made by the Court to split the vote (i.e. 75% of SAB shares present and voting either in person or by proxy provided that there is a quorum of at least 50% of outstanding SAB shares attending and voting at the meeting). 


Now that the SAB board recommendation has been obtained, our source close to ABI confirmed that ABI expect the integration planning to recommence as soon as this weekend. We remind investors that ABI are highly committed to the transaction and are said to be providing “incentives” to their employees to complete the transasction in an October/November timeframe. 


We currently expect the Belgian Offer Document to be published shortly now that all the pre-conditions have been satisfied and for the UK Scheme Document to be published shortly after a decision is made by the UK High Court. We understand that the Court only meets on Mondays and that submissions have to be made by the previous Wednesday in order to get on the agenda for the following Monday. Thus, at the very earliest, SAB have until Wednesday, 3 August to lodge their request with the UK court in order to get on the Court agenda for Monday, 8 August. 


  ​     ​     ​


Makor Capital


11 Menachem Begin St., 26th FL

Ramat Gan 52681
ISRAEL
Tel         +972 3 5453 762

Fax        +972 3 7162 680


Research Disclaimer


This publication has been prepared by Makor Capital Limited (“Makor Capital”) and is intended for professional or qualified investors only. Makor Securities London Ltd (“Makor Securities”)is distributing this material to its clients who are Eligible Counterparties or Professional Clients under FCA Rules. It may also be disseminated to persons who are Investment Professionals within the meaning of the Financial Services and Markets Act 2000 (Financial Promotion Order 2005).  In the United States, Makor Capital only distributes this material to major US institutional investors (as that term is defined in Rule 15a-6 of the Securities and Exchange Act of 1934) and to SEC-registered broker-dealers or  banks acting in a broker–dealer capacity. This material is not intended for distribution to any other persons and should not be redistributed.  If you do not fall into any of these categories you should disregard it.


This material is a marketing communication.  It is not investment research and has not been prepared in accordance with legal requirements designed to promote the independence of investment research. It is not subject to any prohibition on dealing ahead of the dissemination of investment research under U.K. law. This material is not a research report and is not intended to be a research report as defined under U.S. securities laws and regulations.  This material is not intended to provide information reasonably sufficient upon which to base any investment decision.   


This material does not take into account the particular investment objectives, financial situation or needs of individual clients or other recipients. Before acting on this material, clients and other recipients should consider whether it is suitable for their particular circumstances and, if necessary, seek professional advice. 


This material should not be construed in any circumstances as an offer to sell or solicitation of any offer to buy any security or other financial instrument, nor shall it, or the fact of its distribution, form the basis of, or be relied upon in connection with, any contract relating to such action. 


In the United States, Makor Capital does not offer securities services to U.S. persons except pursuant to SEC Rule 15a-6 only to major US institutional investors and SEC registered broker-dealers or  banks acting in a broker–dealer capacity. Transactions in the United States must be effected through the U.S. broker-dealer, Oscar Gruss & Son Incorporated. Oscar Gruss & Son has not prepared, reviewed or distributed this material.


Some of this material is produced by providers which Makor Securities believes to be reliable, but Makor Securities does not warrant or represent (expressly or impliedly) that it is accurate, complete, not misleading or as to its fitness for the purpose intended and it should not be relied upon as such. 

Opinions expressed will be the current opinions of those producing this material as of the date appearing on this material only. We expect those producing the material in  this publication to update it on a timely basis but can give no undertaking that they will do so and regulatory compliance or other reasons may prevent  them from doing so (or us from disseminating updated material).  


Members and employees of Makor Securities London Ltd, employees of Makor Capital, Makor Capital Markets may from time to time have long or short positions in securities, warrants, futures, options, derivatives or other financial instruments referred to in this material. For Makor Securities, this information is set out in our Conflicts of Interest Policy which is available on request.  Policies for the production of research from other research providers are available on request.  Unless otherwise stated, share prices provided within this material are as at the close of business on the day prior to the date of the material.


Neither the whole nor any part of this material may be duplicated in any form or by any means. Neither should any of this material be redistributed or disclosed to anyone without prior consent. This material is issued for general information and discussion purposes only. None of  Makor Securities, Makor Capital, Makor Capital Markets accepts  liability whatsoever for any direct, indirect or consequential loss or damage of any kind arising out of the use of all or any of this material. 


The services, securities and investments discussed in this material may not be available to, nor are suitable for all investors. Investors should make their own investment decisions based upon their own financial objectives and financial resources and it should be noted that investment involves risk, including the risk of capital loss. Past performance is no guide to future performance. In relation to securities denominated in foreign currency, movements in exchange rates will have an effect on the value, either favourable or unfavourable.


All investors. Investors should make their own investment decisions based upon their own financial objectives and financial resources and it should be noted that investment involves risk, including the risk of capital loss. Past performance is no guide to future performance. In relation to securities denominated in foreign currency, movements in exchange rates will have an effect on the value, either favourable or unfavourable.


Entities


Makor Securities London Ltd is authorised and regulated by the Financial Conduct

Authority (FCA registration number 625054) 


Makor Capital, company number 514456466, is incorporated in Israel and is a 100% held

subsidiary of Makor Holdings Pte Ltd incorporated in Singapore. 


Makor Capital Markets SA, company number CH-660.2.999.011-0 is incorporated in Switzerland

and is also a 100% held subsidiary of Makor Holdings Pte Ltd.


Having trouble viewing this email? Click here


This email was sent to lchekroun@makor-cm.com by Research@Makor-Capital.com

Update Profile/Email Address | Unsubscribe | Report abuse


 V.I.Plus e-mail marketing