FT : Meggitt jettisons ballast in bid to lift shares

Meggitt jettisons ballast in bid to lift shares
Chief executive Stephen Young thinks the company might be at the turning point

Meggitt knows a lot about what keeps aircraft in the air. It has been in the aviation business since 1860, when it supplied altimeters to hot-air balloonists.

However, it seems to have lost the knack of keeping its own shares aloft. After a series of profit warnings, Meggitt shares are at 468p, way below the early 2015 heights of 550p. That is despite activist Elliott Advisors arriving on the share register this summer.

Meggitt, which supplies parts and materials for new aircraft, spares to old ones and systems to the energy industry, has been knocked off course by the oil price fall and customers cutting budgets just as its own spending peaked.

Last year, the group spent more than $500m on acquisitions and a tenth of its £1.6bn revenues on research and development. By the half-year to June its net debt had risen to 2.6 times earnings before nasties.

This year, Stephen Young, Meggitt’s boss, has been tipping out the ballast. He has cut costs, reduced debt, rationalised plants, and pushed further into faster growing areas in civil aviation and sold noncore divisions.

On Wednesday, he sold Meggitt Target, which makes smart missile targets, for £57.5m in cash to rival Qinetiq.

Now he thinks Meggitt might be at the turning point. End-of-year net debt will be comfortably between 1.5 and 2.5 times earnings before tax, interest, depreciation and amortisation.

The number of new aircraft coming into service is above trend, pressure on defence spending is lifting, cash generation is strong and returns from acquisitions are accelerating. Meggitt hasn’t had to warn on profits since October last year. Hurrah.

Mr Young has more to do to cut costs and improve the efficiency of supplies. The energy division is still a drag on performance. The shares are unlikely to rocket into the air. But, at about 14 times next year’s forecast earnings, they should drift up.

Bigger, better British pay

For the 51 Footsie chief executives who publicly backed the “Britain Stronger In Europe” campaign, it is perhaps just as well that its successor group, Open Britain, is not holding a Christmas party, writes Matthew Vincent.

Its website lists only a get-together at the Fox & Firkin in High Street, Lewisham, but this seems likely to be about as festive as the group’s “victory” party in June.

Since that fateful summer night, the 51 — and, indeed, the other 49 — have also seen their holiday spending power hit by a slump in sterling, with those from overseas most exposed.

Three weeks ago, this column calculated the biggest currency-related pay “cuts” since the Brexit vote: €230,000 for Kingfisher’s Véronique Laury; NZ$1.1m for RBS’s Ross McEwan, $2.3m for Prudential’s Mike Wells; and Rs300m for Reckitt Benckiser’s Rakesh Kapoor.

However, a new pan-European study at least offers some tidings of joy. From research taking in 701 companies in six countries, Xavier Baeten and Said Loyens of Belgium’s Vlerick Business School have drawn two conclusions.

UK chief executives earn more than their continental counterparts, and their pay is driven by one overriding factor: not margins, not profit, not price change, just relative company size.

Last year, FTSE 100 chief executives enjoyed the highest total remuneration of those studied: on average, €4.4m.

Gender, age and nationality, as any Open Briton would hope, played no part in this. These factors had standardised beta coefficients — a measure of their predictive powers, out of 1 — of 0.005, 0.038 and minus 0.082, respectively. But nor was profit a driver: earnings margin had a coefficient of minus 0.045. By contrast, market capitalisation was everything: at 0.783.

Conveniently, change — rather than ranking — of market cap had little effect: a coefficient of just minus 0.018. All of which may explain why Footsie CEO pay rose 9.6 per cent in 2015 while the index was down 4.9 per cent.

Perhaps those 51 captains of industry should have gone with a simpler rebrand: Stronger Than, not Stronger In.

Ace manager aced

Mark Lyttleton, ace fund manager at BlackRock, has just been given a jail term for insider dealing. But he was not as ace has he seemed. He lost money buying call options in Cairn Energy, having heard that the oil group had struck oil in Greenland.

It turned out that Cairn hadn’t found oil of a quality or quantity to be worth recovering. Mr Lyttleton lost £10,000 on the punt.

He made a classic rookies’ error — assuming it is enough to find oil to make out like a bandit. As Molesworth would say, any fule kno’ that the way to make it rich is to tap investors for the millions needed to extract oil and take a cut.

(TechCrunch) U.S. wearables market is doing much worse than expected

U.S. wearables market is doing much worse than expected
Next Story
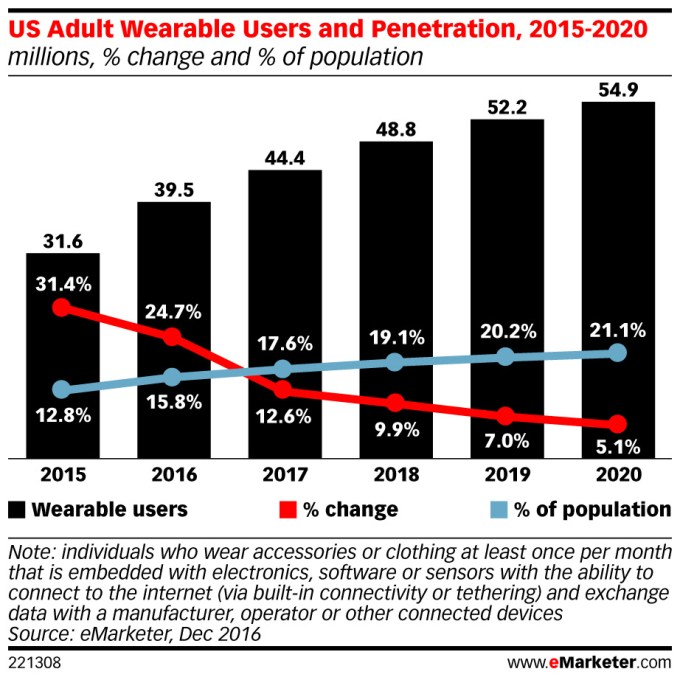
Apple may still be claiming that sales of its Apple Watch are “doing great,” but overall, the wearable device category is failing to grow at the rates forecasted earlier. According to a new report from eMarketer, wearables like Apple Watch and Fitbit were expected to grow more than 60 percent year-over-year from 2015 to 2016. However, the firm is now cutting that estimate down to just 25 percent growth this year.
“Smartwatches in particular,” the report said, “have failed to impress customers.”
Unlike other device categories, wearable devices have struggled to gain traction beyond early adopters. And with smartwatches, consumers struggle to find a reason to buy.
eMarketer analyst Nicole Perrin pointed out that before Apple Watch arrived on the scene, fitness trackers dominated the space. Today, fitness and health tracking remain one of the key selling points for the new crop of wearable devices, Apple Watch included.
But Apple hasn’t convinced everyone that a smartwatch is something they need, especially given the higher prices compared with standard fitness trackers for the watch’s enhanced functionality.
“Without a clear use case for smart watches—which have more features than fitness trackers, but significant overlap with smartphone functionality—the more sophisticated, expensive devices have not caught on as quickly as expected,” said Perrin in the report.
The firm estimates that 39.5 million U.S. adults will use a wearable device with internet connectivity at least once per month. However, this is much less than the 63.7 million eMarketer predicted back in October 2015. Use of wearable devices will only reach 15.8 percent of the population, and is only expected to grow to 21.1 percent by 2020.
eMarketer isn’t the only firm noting the troubles in the wearable market. This month, IDC reported smartwatch numbers were on the decline, with Apple dropping to fourth place after a 71 percent year-over-year decline in total shipments. Fitbit instead won the category with 23 percent of the market and 5.3 million units shipped in the quarter.

But even Fitbit could be struggling. New reports indicate that Fitbit’s Charge 2 may not be selling as quickly as expected, based on channel checks that found its inventory to be “particularly bloated,” along with weak demand for its Flex 2.
In addition, IDC had said this past October that smartwatch sales were tanking, with total shipments down 51.6 percent from the same time last year.
Apple had responded to IDC’s latest report not with hard numbers, but by touting the Apple Watch’s success as compared with its own prior sales. Apple CEO Tim Cook said that Apple Watch sales hit a record during the first week of holiday shopping, and that the current quarter is on track to be the best yet.
It’s not surprising that the Apple Watch sold better than before during the 2016 holidays – after all, this is the time of the year where people tend to increase their spending. Plus, Apple released a new version of its smartwatch ahead of the holiday season which likely contributed to the bump.
But that bump may not save the wearable category as a whole.
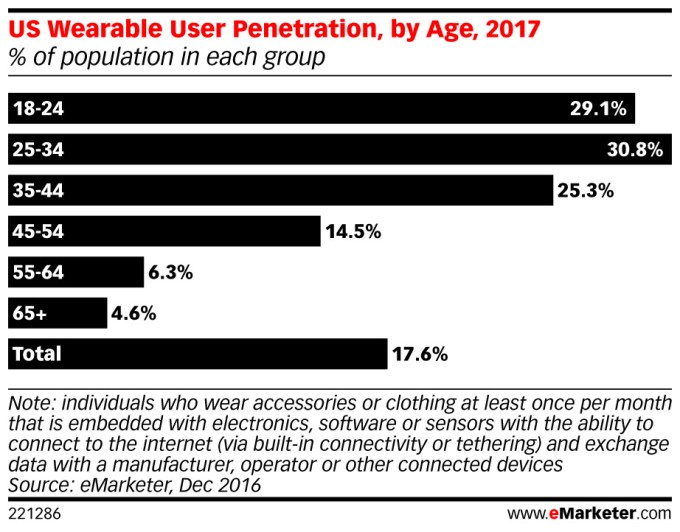
eMarketer’s new report also noted that younger people are more interested in wearables, as around 30 percent of those 18 through 34 will be wearable users in 2017 – a figure that’s 17.6 percent higher than the overall population.
Wearable early adopters also skewed male, until the shift toward fitness trackers, the report also found. By 2018, more wearable users will be female, it’s now forecasting.

FT : Dong Energy bumps up profit guidance after wind farm deal

Dong Energy, which hit the stock market only in the summer of this year, has lifted its profit guidance for 2016.

The Danish group said it thinks it will make an operating profit of DKr24bn (€3.23bn) to DKr25bn this year, up from a previous range of DKr20bn to DKr23bn, triggered by an agreement to sell half of Race Bank, a UK offshore wind farm project, to Macquarie. It has also been helped by a “strong performance” and cost cuts in its oil and gas division.
CEO Henrik Poulsen said:
We have had a really good year in DONG Energy and made significant strategic and operational progress in all business units. We have continued the green transformation and seen significant growth in our operating profit. All business units have delivered better than expected or to the high end of our expectations, and the divestment of 50% of the Race Bank Offshore Wind Farm has triggered the increase in our EBITDA guidance.

>>> US Gapping down:


Gapping down:

Earnings/guidance: FINL -14.1%, SCS -9.5%, LNN -3.8%, ACN -3.3%, FDX -2.5%

Other news:

  • XGTI -55.0% (prices approx. $10 mln offering of Class A and Class B Units, Class A Units were priced at $2.00)
  • MACK -19.9% (stops the Phase 2 HERMIONE study of MM-302 in HER2-positive metastatic breast cancer patients who had previously been treated with trastuzumab, pertuzumab and ado-trastuzumab emtansine)
  • AAAP -4.6% (FDA has issued a complete response letter regarding the NDA for Lutathera for the treatment of gastroenteropancreatic neuroendocrine tumors)
  • SBGL -2.6% (still checking)
  • FL -2.1% (FINL earnings read-through)
  • DKS -1.2% (FINL earnings read-through)
  • UPS -1.2% (FDX earnings read-through)
  • TWTR -1.2% (CTO Adam Messinger to leave the company)

Analyst actions:

  • NYCB -1.7% (downgraded at Raymond James, Morgan Stanley, FBR & Co following terminated merger with AF)

>>> Early pre-market gappers


Early pre-market gappers

Gapping up: CALA +18.0%, INVN +16.8%, LXRX +12.6%, WGO +6.9%, BCEI +5.8%, ERJ +5.5%, GST +5.3%, CLLS +3.9%, GTE +3.1%, DEPO +2.7%, NKE +2.6%, CBD +2.6%, JCP +2.8%, SDRL +2.2%, AU +2.1%, WTI +2.0%, FRO +2.0%, STO +1.9%, MNST +1.9%, LPI +1.7%, DRYS +1.7%, AUY +1.6%, VALE +1.5%, WLL +1.5%, NBR +1.5%, QGEN +1.3%, PAYX +1.2%, BP +1.1%, TOT +1.1%.

Gapping down: XGTI -55.0%, MACK -19.9%, FINL -14.1%, SCS -9.5%, AAAP -4.6%, LNN -3.8%, ACN -3.3%, SBGL -2.6%, FDX -2.5%, FL -2.1%, EBAY -2.1%,  NYCB -1.7%, CS -1.4%, MTL -1.3%, DKS -1.1%.