FT : US pension funds worth $1.5tn add risk through leverage

US pension funds worth $1.5tn add risk through leverage
Retirement systems allow more borrowing and derivatives as private holdings strain cash flows

US public pension plans that manage hundreds of billions of dollars of assets are increasingly turning to risky leverage strategies as burgeoning private market holdings create cash flow strains.

At least eight very large US public pension funds are using borrowed cash or other leverage strategies, now that the board of Calstrs, one of the largest US retirement funds, this month voted to allow the fund to borrow as much as $30bn, or 10 per cent of its portfolio.

The strategy has risen in prominence as these giant funds have tied up a larger and larger share of their assets in illiquid investments such as private equity, infrastructure and real estate. Using borrowed money and derivatives can help boost returns, rebalance portfolios and give the funds access to cash without having to resort to fire sales of illiquid assets during times of market stress.

But use of leverage can backfire, as it did during the 2022 gilt markets crisis, when forced selling by UK pension funds led to an emergency intervention by the Bank of England. Global regulators have recently stepped up scrutiny of the practice as well as broader systemic risks posed by nonbank financial institutions.

“If you are borrowing money to help avoid fire sales then this is a risky strategy because the money still needs to be paid back,” said Alasdair Macdonald, head of investment strategy with WTW, a global professional services firm.

“There is still a risk that assets will have to be sold at low prices, to repay the borrowing, locking in losses.”

California’s Calpers as well as state funds in Wisconsin and Texas are among the large funds already using leverage as part of their strategies. Virginia Retirement System said they are adding the tactic in the near future. The eight US funds known to have embraced leverage together manage $1.5tn.

Many large pension funds currently have more money allocated to private equity than their targets, in part because a slowdown in deals and new listings mean that funds are not returning money as quickly to their investors. That makes it harder to rebalance and increases the risk of missing the chance to snap up bargains if they do not have cash on hand.

The growing reliance on illiquid assets has also introduced new challenges in terms of cash flow for defined benefit style funds, such as Calstrs and others public retirement systems, which must pay regular benefits to millions of retirees. 

Calstrs, formally the California State Teachers’ Retirement System, has for six years in a row put more money into private equity than it has received back, according to filings. Its exposure to private equity has grown to 16.5 per cent of its portfolio, at the very edge of Calstrs’ targets. 

“Pension funds use leverage to manage cash flow and manage portfolios more efficiently,” said James Lewis, chief investment officer at the UK arm of Mercer, which advises pension funds.

“For example, futures can be put in place whilst an equity portfolio is being built, with the futures position unwound afterwards. The advantages of this are the avoidance of cash drag and swifter implementation. In most cases the main disadvantages are increased complexity and a need for robust operational controls.”

Steven Foresti, a senior adviser at Wilshire, an investment adviser that works with public pension funds, said some industry players were “a little bit early on that journey” to understand the risks of using leverage.

“I don’t think you can kind of pick a level of knowledge (about taking leverage) and say that applies to the industry writ large,” he said.

Calstrs has historically used some leverage within certain strategies, such as derivatives trading, but the proposal approved by the Teachers’ Retirement Board investment committee will enable the giant fund to borrow up to 10 per cent of the total portfolio.

“We are not looking to immediately borrow capital, but this an investment tool to utilise, particularly during market disruptions,” Scott Chan, deputy chief investment officer, told an investment committee meeting.

“We have 42-43 per cent [of the portfolio] in private markets and alternative assets. We need the flexibility to rebalance that, particularly with cash flow issues [we face],” he said. “We are not paving new ground in the industry”.

Calpers, the largest pension plan in the US with $452bn in assets, had total fund leverage of 8 per cent as of June 2023, which included what the fund described as “active” and “strategic” leverage. 

The $106bn Virginia Retirement System told the Financial Times it planned to increase its leverage level from zero to 1 per cent in the “near-term future” and expected the ratio to reach as high as 3 per cent of its portfolio. 

VRS said the use of leverage was part of its “long-term strategic asset allocation, which seeks to maximise return while balancing risk”. Virginia has almost half of its portfolio in private markets, including a 33 per cent stake in private equity, according to 2023 data.

The State of Wisconsin Investment Board said current target leverage approved at its December 2023 board meeting is 12 per cent.

The Texas Retirement System incorporated leverage within its individual asset allocations in 2019 to improve the “risk return profile” of the fund. By 2022, TRS said the use of leverage had added 0.63 per cent to returns over the previous three years — or more than $1bn. 

Calstrs has acknowledged that its leverage move was not without risk but believes allowing up to 10 per cent leverage, “poses minimal risk to funding over time”. The fund intends to implement tighter monitoring and governance around leverage use.

“I want the members to know we guard their money jealousy,” said William Prezant, chair of Calstrs’ investment committee.

>>> Barron’s Weekend Summary

Barron’s Weekend Summary: Stocks have regained momentum after a bleak start to the year,

Cover:
-Stocks have regained momentum after a bleak start to the year, with the tech highfliers leading the way. The S&P 500 index reached its first all-time closing high of 4839.81 on Friday, marking its first such record in over two years. The Barron's Roundtable, held on January 8 in New York, discussed 19 potential contenders and a variety of attractive bond funds. Speakers included William Priest, chairman and co-chief investment officer at TD Epoch, David Giroux, Sonal Desai, Scott Black, and John W. Rogers Jr., founder of Ariel Investments. The discussion highlighted the potential of these companies to attract value-conscious investors.

Interview:
-no interview this week

Tech Trader:
-The ad industry is facing a growing problem in 2024, with many ads and wasted money. Google, the parent company of Google, has threatened to phase out third-party cookies in Chrome, which controls 65% of the web browser market. This move is expected to disrupt the ad industry, as Apple's Safari browser already blocks third-party cookies. CEO Mark Zagorski, CEO of DoubleVerify, believes that the ad market is more upbeat this year than last year, with a sense that the market is not ready for a boom. DoubleVerify's role is to ensure advertisers get what they pay for, ensuring ads are seen and not appearing adjacent to problematic content.

The Trader:
-Legislators from both parties have agreed on a tax proposal with business-focused provisions, which could stimulate investment spending and generate a corporate windfall. The plan includes expansions of child and low-income housing tax credits and ending a Covid-era employment-support program. The Tax Relief for American Families and Workers Act of 2024, published on Tuesday, undoes provisions in the 2017 tax bill that rolled back favorable research, depreciation, and interest deductions starting in 2022. The big winners will be stocks of companies that spend the most on research, equipment, and interest payments.
-The S&P 500 index rose 1.17% in a holiday-shortened week, closing at a new record for the first time since January 2022. The Dow Jones Industrial Average added 0.72%, and the Nasdaq Composite jumped 2.26%. U.S. bank stocks generally slid after reporting fourth-quarter 2023 earnings, weighed down by billions of dollars of special charges to pay back regulators for backstopping failed regional banks' deposits last year. Semiconductor stocks had a particularly strong week after Taiwan Semiconductor Manufacturing gave a bullish forecast for the year ahead. However, investors have proved hard to impress, with 88% of the 43 S&P 500 companies reporting by Thursday morning beating the consensus earnings-per-share estimate. Wall Street's consensus calls for 11% S&P 500 EPS growth in 2024, which would help justify an index trading at about 20 times forward earnings.

Features:
-BP, the former British Petroleum, has refocused on its oil-and-gas business, particularly its U.S.-oriented operations. The company aims to boost its American oil-and-gas production by over 50% by 2030 and produce half of its projected output of two million barrels a day in the U.S. Despite its ambitious goals, the market has not yet noticed. BP's U.S-listed shares trade around $34 after hitting a 52-week low, fetching just seven times projected 2024 earnings of $5 a share, which is cheap even for big European energy companies. This shift in focus is expected to benefit BP's beaten-down stock.
-Microsoft has revealed that Russian hackers have accessed the email accounts of some of its senior leadership team, allowing them to read some messages and attached documents. The company identified the threat actor as Midnight Blizzard, also known as Nobelium. Microsoft has previously discovered attacks on its software by Midnight Blizzard, including an attack affecting small businesses in August. The attack began in late November using a password spray attack on a non-production test account, allowing access to a small percentage of Microsoft corporate email accounts.

Europe:
-Desmond Lachman, a senior fellow at the American Enterprise Institute and former deputy director in the International Monetary Fund's Policy Development and Review Department, discusses the fate of the Euro, which was launched 25 years ago with bold promises. However, despite the fanfare and bold promises of prosperity, economists like Milton Friedman and Martin Feldstein criticized the Eurozone for not meeting the basic conditions for an optimum currency area and questioning the wisdom of a monetary union before a political union. In 2024, the promise of economic growth and political integration in the euro zone has largely been unfulfilled, and the jury is still out on whether the euro will have its final day of reckoning.

Emerging Markets:
-No update this week

Commodities:
-As part pf the Barron’s Roundtable discussion, David Giroux, CIO, T. Rowe Price Investment Management, discussed his favorable expectations for some commodity investment. For the first time in a decade, Giroux is recommending an energy stock: Canadian Natural Resources, an oil-sands company with a market cap of $73 million, is a potential investment for investors. With a reserve life of 29 years, CNQ can grow production by 3% to 5% a year in a capital-friendly, low-risk way. The company is set to hit its net debt target of $10B by the end of the first quarter, and will pay back 100% of its free cash flow to shareholders. This will result in a 4.3% dividend yield and a 3%-4% reduction in share count. CNQ is one of the best capital allocators I have ever dealt with. Despite concerns about the sustainability of Russia's oil production due to Western sanctions and the Middle East, there are many reasons to be positive on energy.

Streetwise:
-Jack Hough is hungry and he feels like a Whopper. Burger King (part of is reportedly considering a franchisee fliparoo, with Oppenheimer). BK stated it's a good idea and the stock could make investors nearly 20% over the next year. The chain has a history of turnarounds, starting in the 1950s with the original California restaurant and later being bought out by franchisees and sold to Pillsbury in the 1960s. In 2014, 3G Capital of Brazil combined Burger King with Canada's Tim Hortons and took it public as Restaurant Brands International.

(ZH) Massive Deficit Spending Keeping The Economy Out Of Recession (For Now)

Massive Deficit Spending Keeping The Economy Out Of Recession (For Now)
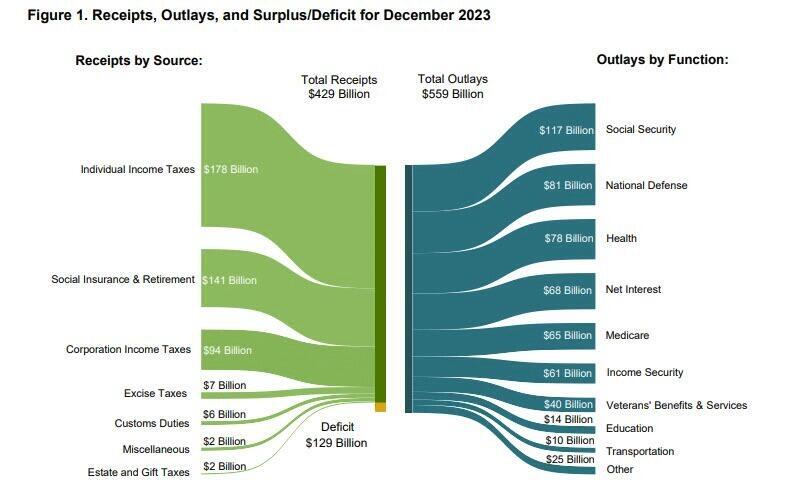
Economic growth continues to defy expectations of a slowdown and recession due to continued increases in deficit spending. In fact, the U.S. Treasury recently reported the December budget deficit, which shows the U.S. collected $429 billion through various taxes while total outlays hit $559 billion.

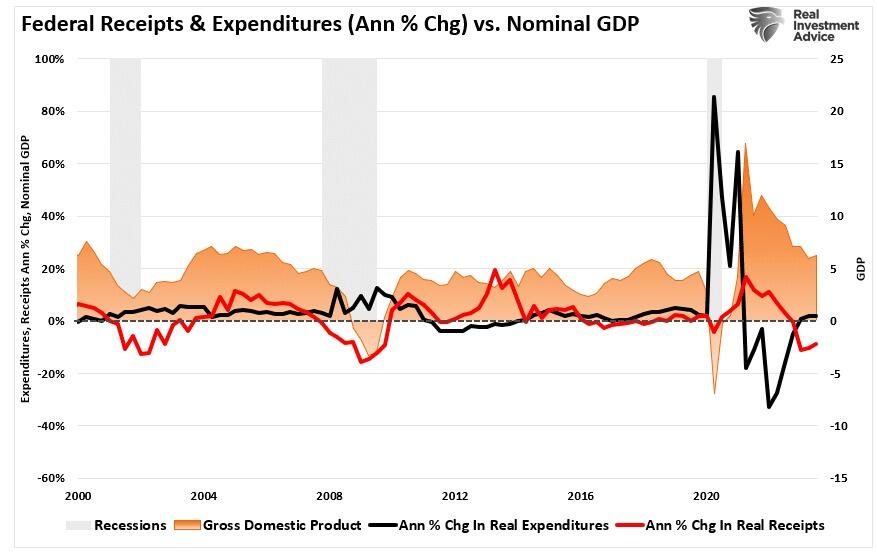
As noted, the problem remains on how the economy has avoided a recession despite the Fed’s aggressive rate hiking campaign. Numerous indicators, from the leading economic index to the yield curve, suggest a high probability of an economic recession, but one has yet to occur. One explanation for this has been the surge in Federal expenditures since the end of 2022 stemming from the Inflation Reduction and CHIPs Acts. The second reason is that GDP was so grossly elevated from the $5 Trillion in previous fiscal policies that the lag effect is taking longer than historical norms to resolve.
However, that red line in the chart above is the most interesting. Notice that while Federal expenditures are rising, Federal tax receipts are falling. Such is why the national deficit is increasing. When we discussed this previously, many thought the shortfall was temporary. To wit:
“California’s tax payments are delayed due to the emergency declaration. However, that doesn’t account for the magnitude of the decline in filings. Secondly, given the shuttering of the entire economy in 2020, which also delayed filings nationwide, the extent of the current decrease seems more than just a single event.”
Given the length of time and the fact the collection rate fell further, it suggests there is more to the decline.
Tax Receipts Send A Warning
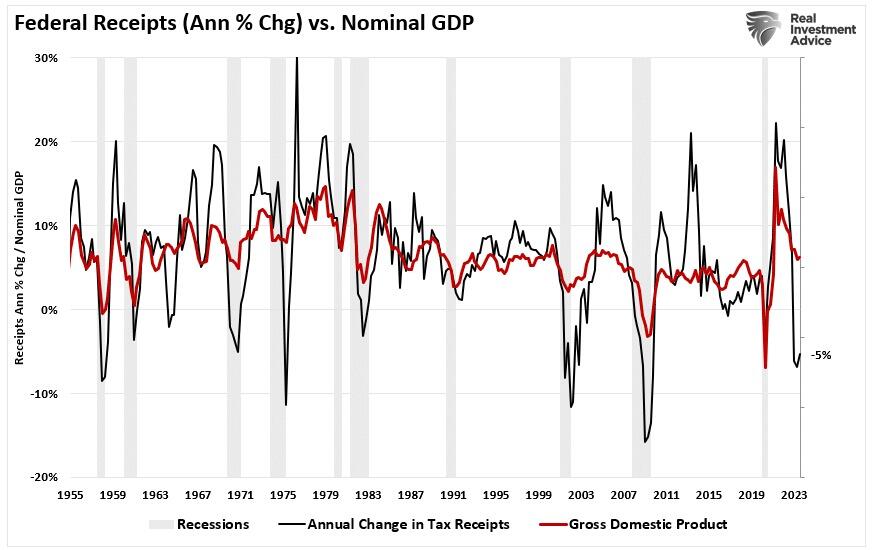
The change in Federal receipts is essential as the Government’s revenue is from the taxes on both corporate and individual incomes. Unsurprisingly, if revenues and incomes decline, such would reflect economic activity. As shown below, there is a very high correlation between the annual change in Federal receipts and economic growth. Historically, when the yearly change in Federal receipts falls below 2% annual growth, such has preceded economic recessions. Federal receipts’ yearly rate of change is currently a negative five percent (-5%).
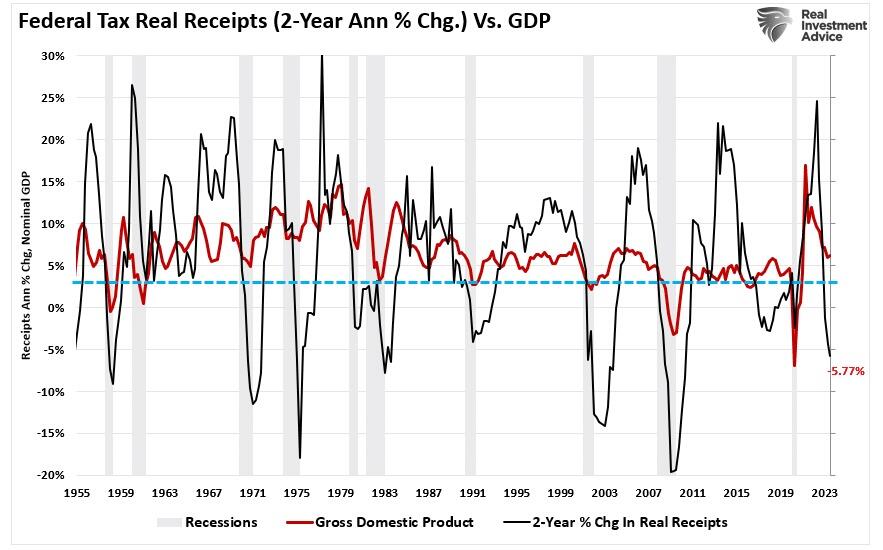
We see the exact correlation by smoothing the data and using inflation-adjusted tax receipts on a 24-month rate of change. Again, a recession follows when tax receipts fall below 2% annual growth rates. I like this measure better as it accounts for the “lag effect” in the economy. The 2-year yearly change in receipts has fallen well below the 2% warning line and is currently at -5.77%.
While tax receipts suggest economic weakness is more pervasive than headlines suggest, the deficit spending flows keep economic growth from becoming recessionary.
The Frog And Deficit Spending
If we look at the current economy, there is no noticeable collapse in the dollar, private capital, rampant Inflation, or recession. However, like bringing the water to a slow boil, the frog doesn’t realize it is in trouble until it’s too late.
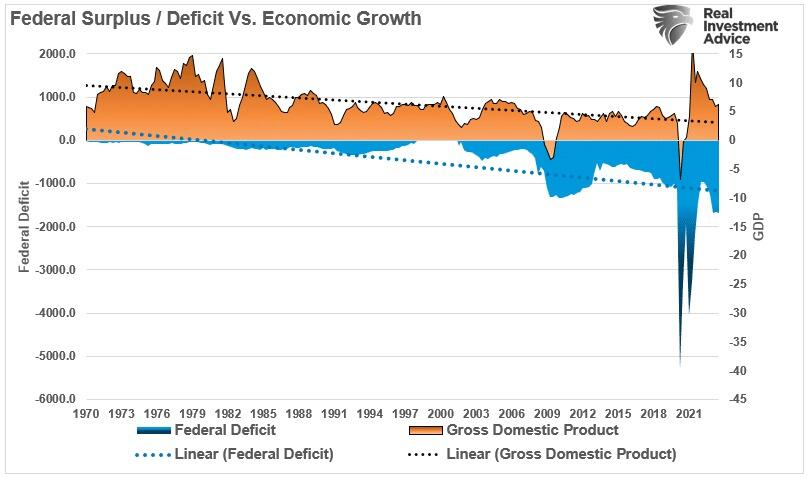
The government’s serious endeavors into deficit spending began with Ronald Reagan in 1980. Since then, politicians concluded that a lot should be better if a little deficit spending is good. For politicians, there are only positive benefits of deficit spending increases. More spending provides a short-term boost in economic activity, which gets them re-elected to office.
However, the water temperature is clearly rising in the longer term.
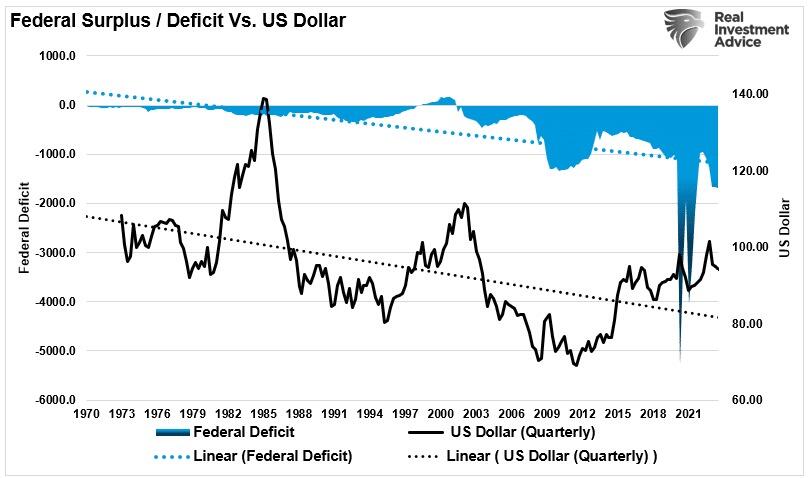
While the dollar hasn’t collapsed under the weight of deficit spending, the negative strength trend relative to other currencies is slowly rising in temperature.
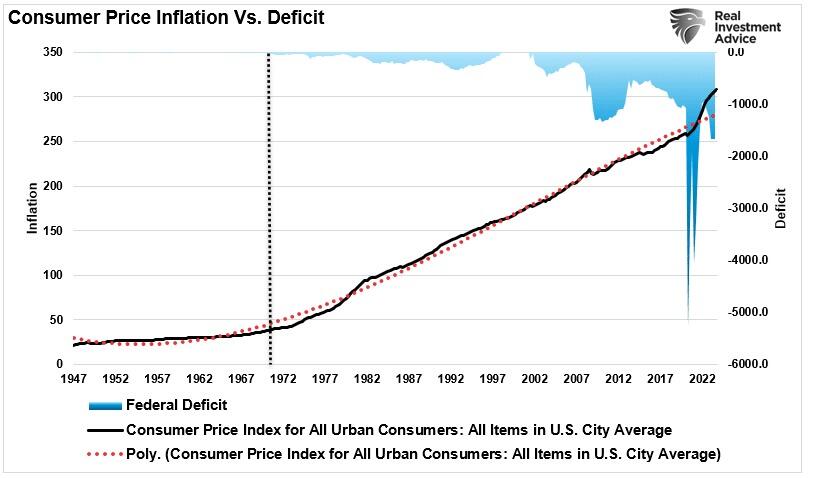
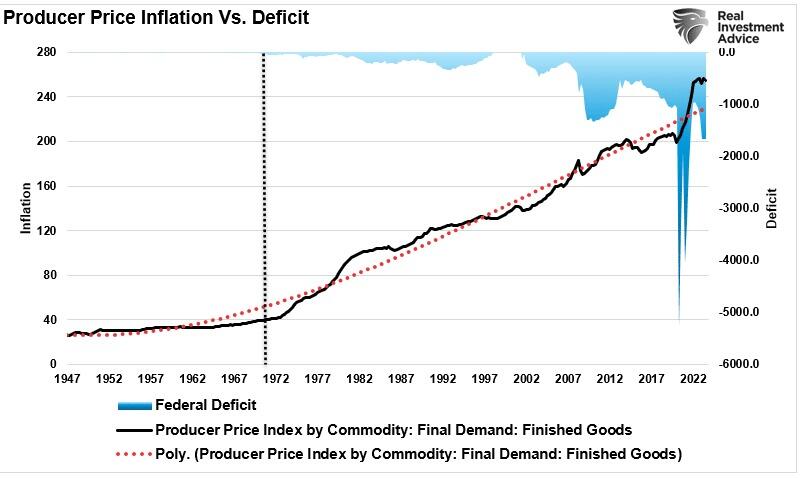
Of course, as the dollar weakened and deficits grew, Inflation, for both producers and consumers, rose.
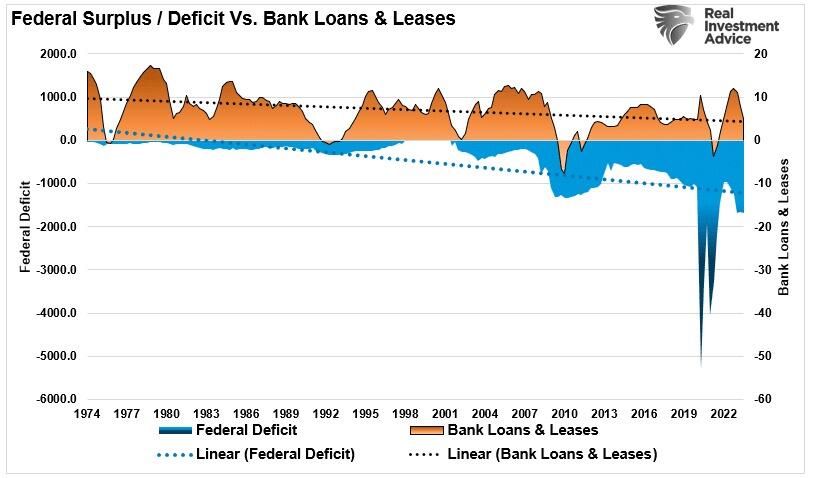
While deficits may not appear to crowd out private investment, the rise of behemoth companies like Apple, Google, and others do crowd out innovation and new company formations. Such activities require capital, and a reasonable correlation exists between the ebbs and flows of deficits and capital acquisition.
Not surprisingly, as the dollar weakens, the movement of capital slows, and Inflation rises, the economic growth rate slows. Such should not be surprising as debt used for non-productive purposes diverts money from productivity to interest service.
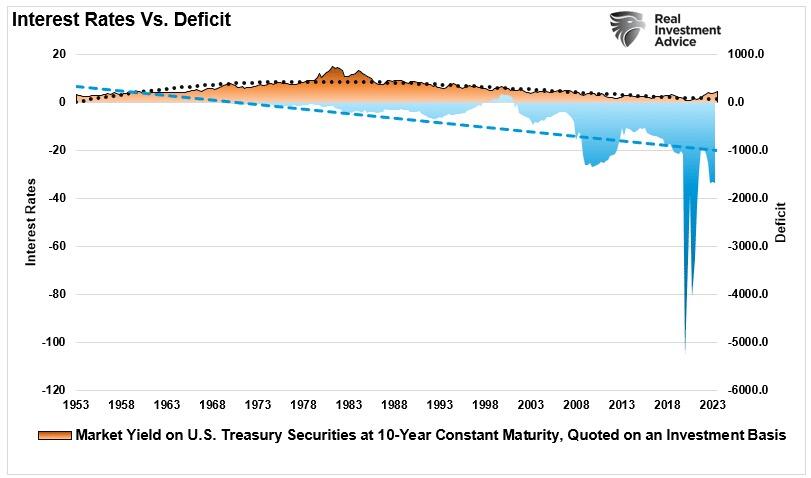
The one thing that deficits have not led to is surging interest rates and massive increases in borrowing costs.
However, that suppression of interest rates has come from two primary sources.
  1. Slower rates of economic growth
  2. Massive interventions by the Federal Government to suppress rates.
Given the sharp increases in Federal debt since 2008 to support economic growth, the economy can not sustain higher borrowing costs for long.
The Economy Is Close To Recession
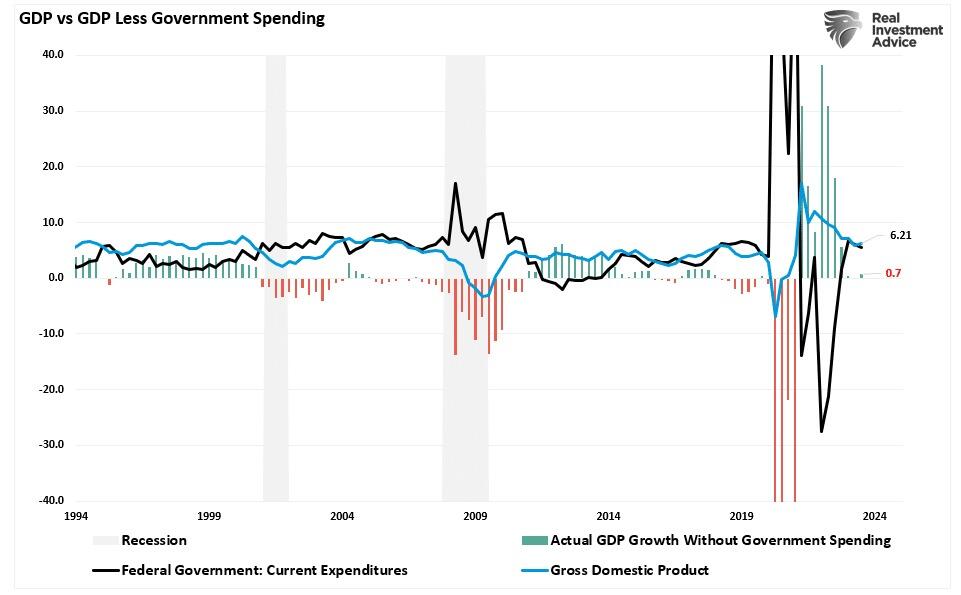
While economic growth continues to defy expectations on the surface, if it weren’t for increases in deficit spending, economic growth would be flirting with recessionary levels at just 0.7% in Q3 rather than 6.21%
In GDP accounting, consumption is the most significant component. Since deficit spending doesn’t filter down into the average household, it is no wonder why Presidential approving ratings are so dismal.
Should governments use deficit spending for “productive investments” during economic downturns? That answer is clearly in the affirmative category.
However, once the economy returns to growth, the deficits should be reversed into surpluses to prepare for the next inevitable downturn. Such is the entire underlying premise of Keynesian economic theory. But, unfortunately, politicians, in their ongoing endeavor to get reelected, ignore the part about repaying debts.
While short-term deficits may have no consequences, the rising levels of corporatism, wage disparities, and wealth inequality provide ample evidence that something has gone wrong.
Are all the problems in the U.S. solely the result of rampant deficit spending? Of coursenot. The U.S. has also spent four decades making poor political and economic choices.
  1. Massive increases in consumer and corporate debt.
  2. A shift from productive to non-productive labor.
  3. Poor immigration policies.
  4. The slow erosion of the rule of law; and,
  5. An undermining of capitalism and a move to socialistic policies.
If you ignore all of the anecdotal evidence, an argument can be made for running continual economic deficits. However, suggesting “deficit spending” has no consequences is entirely wrong.
We can continue our path for quite some time, and probably longer than most imagine.
But, just because we haven’t realized it yet, it doesn’t mean we aren’t slowly being “boiled by deficits.”

>>> Weekend Papers Summary

Weekend Papers Summary

.FINANCIAL TIMES
-Electric vehicles (EVs) are increasing globally, but at slower rates than anticipated due to higher prices compared to petrol alternatives. The UK and Europe's EV sales market share fell last year, while US growth has slowed. In 2023, a record 1.2M EVs were sold in the US, making up 7.6% of the domestic car market. However, Kelley Blue Book analysts noted that the US EV market is still growing, but not as fast. Sales in the last three months of 2023 rose 40% compared to the same period a year earlier.
-Microsoft has reported that a Russian hacking group, Midnight Blizzard, gained access to a small percentage of its senior leaders' email accounts in November. The attack was detected on January 12, and Midnight Blizzard lost access to the accounts on or about January 13. Microsoft attributed the attacks to the risks posed by groups like Midnight Blizzard, which was responsible for a high-profile cyber-attack in 2020 that hijacked software from SolarWinds to breach the US Treasury, Commerce, Pentagon, and Fortune 500 companies.
-A meeting between senior figures in the far-right Alternative for Germany (AfD) party and Austrian extremist Martin Sellner has scandalized Germany's political class and sparked media attention. The meeting, which took place at the Landhaus Adlon in Berlin, saw politicians and wealthy benefactors discussing mass deportations and other incendiary ideas. Many see the meeting as a Rubicon, indicating the AfD's radicalization despite growing political support. AfD leader Alice Weidel fired her closest adviser, but rallies have been held across Germany, with calls to ban the party outright being made at the highest levels.
-New Hampshire holds an "open" primary, allowing registered Republicans and independents to participate in the vote. Nikki Haley is assured of second place, but the question remains whether she can make it close enough to call on primary night. Haley has the endorsement of New Hampshire's governor, Chris Sununu, but South Carolina senator Tim Scott is preparing to endorse Trump. The latest polls show Trump with 47% support in New Hampshire, while Haley has 34%. Florida governor Ron DeSantis has only 5% support.
-South Carolina Senator Tim Scott has endorsed Donald Trump's White House bid, a significant win for the former president and a blow to Nikki Haley's campaign. Scott, who dropped his own bid for the Republican nomination in November, emphasized the need for a president who will close the southern border and unite the country. This endorsement comes as a gut punch to Haley, who appointed him to the US Senate in 2013. Scott, the only black Republican senator, is also rumored to be Trump's vice-president pick.
-Japan has successfully landed a 2.4-metre tall lunar lander on the Moon, becoming the fifth nation to do so. However, the spacecraft's power issue is posing a threat to its ability to study the lunar surface and find clues about the Moon's origins. This comes after a series of setbacks for Japan's space exploration plans, despite increased investment and collaboration with the US to counter China's ambitions.
-Israel's war leadership has sparked a divide after former military chief Gadi Eisenkot called for elections within months and accused the government of not being truthful about its offensive against Hamas. In a blunt television interview, Eisenkot declined to trust Israeli Prime Minister Benjamin Netanyahu, highlighting the need for a return to the polls and elections to renew trust and address issues such as securing Palestinian hostages and post-war planning.
-European Central Bank president Christine Lagarde has quashed investors' hopes of a first-quarter interest rate cut in Davos, citing demands for pay rises by European workers as the main threat. Policymakers at the ECB remained concerned about high wage growth and the potential for it to trigger a surge in price pressures. Lagarde and IMF first deputy managing director Gita Gopinath pushed back on market expectations of a rate cut in the first quarter. However, wage growth remains the main hurdle for a clear shift in tone.

THE NEW YORK TIMES
-With Deal Close on Border and Ukraine, Republican rifts threaten to kill both. A divided GOP coalesced behind a bit of legislative extortion: No Ukraine aid without a border crackdown. Now they are split over how large a price to demand, imperiling both initiatives.
-Stocks climb to record, lifted by big tech and rate cut hopes. The S&P 500 crossed above its January 2022 peak. Investors have been buying stocks after signs that the Fed’s campaign of raising interest rates is over.
-A line chart showing the trajectory of the S&P 500 index from 1980 to now. The index has reached a new peak.
-Divisions have emerged in Israel over Gaza war. Protesters demanded action to free hostages, a war cabinet minister criticized the military campaign and the prime minister ruled out a two-state solution.
-President Biden pressed Prime Minister Benjamin Netanyahu of Israel on working toward the creation of a Palestinian state.
-The US is staring down a Trump-Biden repeat in disbelief and denial. As President Biden and Donald Trump stroll toward a likely fall rematch, many Americans are clinging to forlorn hopes and floating wild theories.
-Ron DeSantis is quietly starting to build his off-ramp from 2024. DeSantis praised Donald Trump’s victory in Iowa. He admitted to an early strategic error. And he’s begun casting his eyes forward to 2028.
-Inside CNN, there’s a debate going on over whether or not to air Donald Trump speeches live.
-Donald Trump, disdaining Nikki Haley, said she “probably” wouldn’t be his running mate.
-Credit card statements suggest prosecutors in Trump case traveled together. Records included in a court filing followed claims that Fani Willis had begun a relationship with Nathan Wade before hiring him to help lead the case.
-Sports Illustrated is thrown into chaos with mass layoffs. The announcement on Friday left in doubt what lies ahead for the venerable publication, with some staff members dismissed immediately.
-After Uvalde, challenges endure for the police despite clear protocols. The failures in Texas underscored a challenge that mass shootings pose to officers: Be ready to use deadly force in some cases, and try to de-escalate in others.
-Louisiana lawmakers approve map that empowers more black voters. A federal court had found that the existing map appeared to illegally undercut the power of Black voters in the state.
-Alec Baldwin is charged, again, with involuntary manslaughter. A grand jury in New Mexico indicted the actor in the death of the cinematographer on “Rust,” months after the original case against him was dismissed.
-In Solano County, Calif., a who’s who of tech money is trying to build a city from the ground up. But some of the locals don’t want to sell the land.
-Japan becomes the latest country to land on the Moon. The SLIM spacecraft made a successful landing on the lunar surface, but a problem with its solar panels means it will soon run out of power. Japan made a soft landing, but robotic spacecraft have crashed and belly flopped on the moon since 1959.
-Trump claims immunity extends even to acts that ‘cross the line.’ On social media, Donald Trump appeared to take a stance that went further than his lawyers have in court about presidential immunity from prosecution.

THE NEW YORK POST
-Donald Trump is leading White House candidate Nikki Haley in South Carolina's primary by a significant margin, according to internal polling by the super PAC backing the former president. The memo, handed to Haley's donors and supporters, includes a survey showing Trump beating Haley by 39 points in the Palmetto State. The poll shows 64% of South Carolina Republican voters favor Trump, 25% favor Haley, and only 8% support DeSantis. Haley's supporters appear to be more uncommitted than Trump's.
-JetBlue Airways and Spirit Airlines have announced they will appeal a federal judge's ruling that blocked their planned merger due to US antitrust law violations. The move follows US District Judge William Young's decision that JetBlue's $3.8B acquisition of Spirit was anti-competitive and would harm consumers. The airlines filed a notice to appeal the ruling to the 1st US Circuit Court of Appeals, stating that the appeal is consistent with the requirements of the merger agreement. Spirit shares rose 12% after the appeal notice, but are still down over 50% since the ruling.

FT : Europe’s food delivery apps are beginning to serve up a profit

Europe’s food delivery apps are beginning to serve up a profit
The companies can point to 2023 as proof that their concept works and can assume further growth in the future

In most sectors, companies lament the impact of rising interest rates. The higher cost of capital sends their wheels spinning. Not so in European food delivery, where operators have paused value-incinerating land-grabs and are starting to gain traction.

For the first time, all three of the European delivery companies are expected to report positive adjusted ebitda in 2023. This metric strips out the impact of share-based compensation, which can be considerable, but it provides a useful indication of how the underlying business is performing.

The UK’s Deliveroo reckons it will do slightly better than its guidance of £60-80mn adjusted ebitda. Earlier in the week, Just Eat pointed to above-guidance adjusted ebitda of some €320mn. Germany’s Delivery Hero, which operates brands such as Glovo, Foodora and Foodpanda, expects adjusted ebitda margins of over 0.5 per cent. 

True, this is a mere sliver of profit and is adjusted to boot. Investors burnt by years of negative cash flows are loath to give the sector much credit. With the exception of Deliveroo, whose strong balance sheet enabled it to return cash to investors, share prices have languished.


Yet the companies can point to 2023 as proof that their concept works. Even in the midst of a cost of living squeeze, they have been able to extract more from their customers without causing them to quit the apps. Gross transaction value at Deliveroo rose 3 per cent year on year to £7bn.

There is more to come, especially in markets where food delivery is less widespread. Demographics will help. Today’s delivery-prone youngsters may spend more as they grow up and their disposable income increases. Gross transaction volume growth in the high single digits should be a reasonable mid- to long-term assumption, thinks Giles Thorne at Jefferies. 

Margins rise with increased penetration. As the density of participating restaurants and diners in a small “hyperlocal” area increases, riders can make shorter trips and even bunch up deliveries. Central overheads are largely fixed, meaning operating margins after amortisation and depreciation should move from negative to some 6 per cent of transaction values, reckons William Woods at Bernstein.

That is an attractive shift, especially for a sector that trades at 6.8 times 2025 ebitda, on Capital IQ estimates. European food retailers such as Tesco and Carrefour, with a fraction of the growth potential, hover near 6 times. Beleaguered platforms may yet deliver the goods.

FT : Soeur brings French style to London

Soeur brings French style to London
A first UK boutique signals global ambitions for the affordable Paris-based brand

In Paris last summer for the couture shows, I made time for a brief shopping pilgrimage. While the world’s 0.01 per cent perused hand-embellished eveningwear, my between-show treat was a snatched detour to the more reasonably priced Soeur boutique.

The city is brimming with shops offering their own vision of La Parisienne, but for me, Soeur’s mix of clean shapes, workwear fabrics and retro prints has an easy cool that stands out. I recommend it to anyone else who wants a change from APC, likes Toast but finds it slightly granola, or aspires to Phoebe Philo, but isn’t rich, edgy or willowy enough.

But now I can spend my free moments in Paris eating a baguette instead of shopping, because Soeur has just opened its first London boutique. Investment fund Style Capital took an 80 per cent stake last September, and aims to accelerate the brand’s international growth. Soeur’s sales have grown by 40 per cent a year for the past two years, and hit €52mn in 2023. For context, at 10 year-old French mid-market brand Sézane, sales rose 30 per cent year on year in 2022. As luxury prices soar, for many shoppers the contemporary (or affordable luxury) space feels extra relevant.

But for those French fashion fans who might have fallen under Sézane’s spell but haven’t come across Soeur, what does the brand bring to la table? It was founded in 2007 by French sisters Domitille and Angélique Brion and now has 50 standalone boutiques or shop-in-shops (41 in France, nine international) as well as 520 wholesale locations globally. Angélique, who was on the finance side, is “no longer involved operationally but is very much involved as a shareholder”, says Domitille, who has always been more focused on creative direction.

On a Zoom call with Domitille and managing director Freja Day, talking from their headquarters overlooking the Louvre in Paris, the pair explain the brand’s vision. Brion feels more comfortable talking in French, so Day is translating.

Creative director Brion says the brand encapsulates everyday elegance. “It’s sophisticated cuts for a woman who wants to feel elegant throughout the day, who doesn’t necessarily want to dress up on a Saturday and dress down on a Sunday. The way that we see [ French style] is this idea that the same garment can be worn during the day or night, depending on your attitude, and how you accessorise it.”

Ah yes, the never-ending topic of French style, how to crack it and how it’s evolving. Cornerstones of the French look — sharp blazers, trenchcoats, and dresses worn with plimsolls and the air of someone who spends their day browsing second-hand copies of Sartre on those bookstalls alongside the Seine — are still frequently spotted in the wild. But now greater experimentation has gained a foothold alongside these timeless classics.

Brion acknowledges that “French fashion is much more on the street, more accessible, and there’s more individual expression. The aesthetic is more polarised, and there’s more diversity: there are people who will follow the current fashion trend like Kim Kardashian, and others who will be more classically French who are maybe less visible on social media.”

Soeur is much more in the timeless than trend-led camp, helped by retro cultural references such as New Wave cinema and unfussy classics such as roomy summer shirt dresses and masculine blazers. However, Brion emphasises that “we are a fashion brand. We have the idea that each season you can update a little bit, rather than going in one direction.” A stylish Paris-based friend who wears it says she sees it as “chic-casual” and “bohemian”, while noting that “it’s very particular universe doesn’t suit everyone”.

The spring/summer collection has gone big on a laid-back, oversized feel, featuring wide trousers in cream twill and denim, long airy smock dresses in checks, chocolate silk and faded florals, and androgynous blazers and workwear jackets.

If Frenchness is one strand of Soeur’s appeal, another is the affordable pricing. For next season, wide linen twill trousers are £260, while a structured leather shoulder bag is £425 for the larger size. It’s one of a cohort of French brands, including Sézane, Sandro and Maje, that have carved out a space at the contemporary level that falls between the upper echelons of the high street and designer.

Day believes “there is space in the middle for a high-quality product . . . good materials combined with true serious design work around the pattern and the cuts. We have a big team of patternmakers who come from all the big luxury houses.” When I mention a Soeur kaftan dress I bought on eBay, Brion enthuses about a special machine in which the brand invested to create the stitch that holds the neckline on this particular garment closed.

Quality and attention to detail made up part of the brand’s appeal for Roberta Benaglia, chief executive and founding partner of Style Capital, which has previously invested in Golden Goose and Zimmermann. She confirms on a separate call that the price positioning is crucial to the plan to take Soeur from a brand that’s well known in France to an international name. “Wholesalers were pushing us to have a brand in our portfolio that was smarter in terms of price point, because what they are seeing is that luxury is too expensive today, with the growth of the prices after Covid,” she says.

Federica Levato, senior partner and EMEA leader of fashion and luxury at consultancy Bain & Company, says that in general: “The contemporary market has been pretty dynamic for the past 10 years. We see a great opportunity for this segment . . . as luxury brands increase prices, these brands have an opportunity to be a more authentic value proposition to customers and really understand them.” She cautions, however, that for brands that mainly cater to local markets, going global without the marketing budgets of big luxury houses will be more of a challenge.

Benaglia was also drawn to Soeur’s strong digital performance — it makes 35 per cent of its sales online — but the team is still enthusiastic about physical retail. According to Day, “it gives a context to the brand. OK, we are not a mom-and-pop shop, but we visit the stores often and get to know our customer — it’s what makes our work engaging.” She says there is a type of “VIP customer who used to shop at Phoebe Philo for Céline and has moved towards us for minimal wardrobe essentials, which she combines with designs from higher-priced brands such as Acne and Jil Sander”.

Brion says the new shop, on Redchurch Street in east London’s Shoreditch, is more pared back than many of the other boutiques, using lighter wood and more concrete on the floors. They decided to open in the UK capital “because we love London, and to be here is to be on the international map . . . it’s a window to Asia and the US”.

Finally, why does Brion believe Soeur can expand? “Maybe it’s a bit pretentious to say this but we feel like there’s a lot of potential; we are not done yet. It’s not necessarily about being the next Sandro or similar . . . but we feel like there is a Soeur customer in Seoul, there’s one in London, there’s one in Shanghai probably. And we want to dress her.”

>>> Weekly Market Update

Weekly Market Update: Risk-on sentiment prevails despite mixed data and earnings reports

Rates and stocks moved higher in a holiday shortened trading week for the US. Central bankers used the Davos forum to push back on the markets' current optimism for 2024 rate cuts. Economic data mostly supported that message as well. US manufacturing numbers were mostly subdued but December US retail sales and housing starts/permits, in particular, were stronger than most expectations. Weekly jobless claims came in below analyst estimates yet again. UK CPI was hotter than expected, as inflation there accelerate for the first time since last spring. Chinese stimulus expectations also underpinned sentiment after officials in Beijing confirmed they were discussing CNY1T in ultra long-bond issuance to fund various projects.

Geopolitical hotspots remained a concern, but markets largely looked past any expected lasting effects. Houthi fighters continued their intermittent attacks on ships in the Red Sea, drawing reprisals from the US and UK in Yemen. President Biden confirmed the US would continue preemptive air strikes against Houthis weapons systems. Russian stepped up missile attacks on Ukraine residential areas as President Zelenskiy attempted to solidify support in Davos. By Friday, NATO was said to be mobilizing 90K troops for the largest military drills since the Cold War next week. Meanwhile in Asia, North Korea conducted a test of an underwater nuclear weapons systems after fresh long range missile launches earlier in the week. Davos also saw lots of officials hand-wringing over the consequences of a second term for former President Trump after he easily won the Iowa caucus and remained well ahead in the New Hampshire primary polls. The Dollar index touched its highest levels since early December, while Bitcoin reversed and moved lower. Oil prices were little changed along with gold. The US 10-year yield backed up ~20 bps on the week to finish around 4.15%. For the week, the S&P hit all-time highs, adding 1.2%, while the DJIA rose 0.7% and the Nasdaq was up 2.3%.

In corporate news, financials were heavily featured among the earnings reports this week, and some tech names continued to shine. The regional banks took their turn at reporting quarterly results, and many still look shaky almost a year after the mini-crisis in the sector. Discover Financial posted disappointing results as well, as its charge off rate nearly doubled to over 4.1% for the quarter. Some other financial firms fared better, including The Travelers, which blew out earnings expectations and affirmed long term guidance, and Ally Financial, which beat estimates and announced the divestiture of its POS financing business. Humana slashed its FY23 forecast on higher medical costs, dragging down the healthcare sector. Advanced semiconductor names benefited from strong guidance out of Taiwan Semiconductor and Super Micro, sending a number of companies in that sector to fresh all-time highs. M&A news featured two big deals falling apart: A federal judge blocked Jetblue’s acquisition of Spirit on antitrust grounds, pushing Spirit toward a restructuring, and the European Commission is reportedly preparing to deny Amazon’s plans to acquire iRobot.


WEEKEND
(TW) TAIWAN’S RULING DEMOCRATIC PEOPLE’S PARTY (DPP) WILLIAM LAI WINS PRESIDENTIAL ELECTIONS WITH ~40% OF VOTES (AS PREDICTED BY THE POLLS); DPP party did NOT win parliamentary majority, but won unprecedented third consecutive presidential term
ALK Confirms FAA extended grounding of Boeing 737 MAX 9 indefinitely; FAA requires more data from Boeing before
(CN) CHINA PBOC CONDUCTS CNY995B VS. CNY900BE IN 1-YEAR MEDIUM-TERM LENDING FACILITY (MLF) AT 2.50% VS. 2.50% PRIOR
(US) Senate Majority Leader Schumer on Stopgap spending bill: House & Senate to release stopgap spending bill to Mar 1st and Mar 8th (from current Jan 19th and Feb 2nd, as speculated earlier in the weekend)
AAPL Said to offer up to 5% discounts for some products in China, including iPhone 15, for the first time in few years ahead of Chinese New Year - press citing company website

MON 1/15
(US) Fed’s Bostic (dove, voter): Inflation could “see-saw” if Fed cuts rates too soon; The descent towards 2% target is likely to slow in the months ahead; Taking a closer look at liquidity conditions
Qatar pauses its gas shipments through the Red Sea and Suez Canal - press
(DE) German army reportedly considering the possibility of a Russian attack on NATO's eastern flank as early as 2025 - Bild
(US) Reportedly Pres Biden and other senior US officials are becoming increasingly frustrated with Israeli PM Netanyahu and his rejection of most of the administration's recent requests related to the war in Gaza – Axios
PAGE.UK Q4 Trading Update: Gross Profit £237M v £253Me, -8.9% y/y (cc); Trims outlook citing macro-economic uncertainty persists
PAGE.UK Exec: Early 2024 shows reasonable activity; No further deterioration in US business - post earnings comments
US federal scientists conclude Marijuana should be removed from the US's most restrictive Schedule 1 category of drugs - NYT
(US) Houthi Negotiator*: All ships in the Red and Arabian Seas are safe, except vessels headed to Israel; We do not want escalation, we regret US and UK's militarization of the Red Sea
(US) On a House GOP conference call Sunday night, House Speaker Johnson said Congress can’t solve the crisis at the border until Trump or another Republican is in the White House; This could signal the end of the road for U.S. aid to Ukraine, a major Biden administration priority - Punchbowl
RIO.AU Reports Q4 Pilbara Iron-ore Shipments 86.3Mt, v 86.7Mte, -1% y/y; Notes US economy is slowing down with labor market cooling; China economy stabilized earlier in Q4
(US) Former Pres Trump projected to win Iowa Caucus (as expected); With ~90% of vote counted, Trump has 50.9%, DeSantis has 20.0% and Haley 19.0%; Vivek Ramaswamy suspends Presidential campaign - media outlets
(CN) China reportedly told some institutional investors not to sell stocks; China regulators reimposed stock-selling restrictions on securities to stabilize the stock market - FT

TUES 1/16
(IR) Reportedly Iran’s Revolutionary Guard deployed in Yemen and playing a direct role in Houthi rebel attacks on commercial traffic in the Red Sea - Semafor
(CN) Chinese banks reportedly tighten curbs on Russia after US sanctions order; Chinese banks said to stop providing any financial services to the Russian military industry regardless of the currency or the location of the transactions - press
CARD.UK FY23 Trading Update: Strong Christmas trading performance with LFL store Rev +7.8% in Nov-Dec; Pretax ahead of market expectations, FY23 Rev £476.9M v £432.6M y/y
Leading mining group Rio Tinto warns US economy is slowing down with labor market cooling; Summary of recent profit warnings and comments on global consumer state made by European, Asian and US firms
(CN) CHINA CONFIRMS MORE STIMULUS WITH CNY1T OF SPECIAL ULTRA-LONG SOVEREIGN BONDS - PRESS [**Note: would be 4th such sale in the past 26 years]
(US) House and Senate negotiators have reportedly agreed on a ~$78B framework for a package of tax benefits aimed at businesses and low-income families - press
PNC Reports Q4 $3.16 v $2.99e, Rev $5.36B v $5.28Be
PNC Guides Q1 average loans stable q/q, NII -3% to -2% q/q, Rev -4% to -3% q/q - earnings slides
AXP Reports Dec Master Trust: Net Write Off Rate: 2.5% v 1.7% prior
GS Reports Q4 $5.48* v $3.47e, Rev $11.3B v $10.7Be
ANSS Confirms to be acquired by Synopsis in $35B cash-stock deal; Ansys shareholders to receive $197/shr cash and 0.3450 shares of Synopsys common stock; Expected to Be accretive to Non-GAAP EPS within second full year and substantially accretive thereafter
(US) JAN EMPIRE MANUFACTURING: -43.7 V -5.0E (lowest since May 2020 and lowest ever ex pandemic, below all analysts' estimates)
(CA) CANADA DEC CPI M/M: -0.3% V -0.3%E; Y/Y: 3.4% V 3.4%E
(US) Fed's Waller (voter, hawk): Will be able to cut the policy rate this year as long as inflation doesn't rebound or stay high
(US) NY Fed takes $583.1B (v $603.1B prior) in RRP program at 5.30%; 65 participating and accepted counterparties (lowest dollar amount since June 2021)
(CN) CHINA DEC INDUSTRIAL PRODUCTION Y/Y: 6.8 % V 6.6%E
(CN) CHINA DEC RETAIL SALES Y/Y: 7.4% V 8.0%E

WED 1/17
1211.HK Launches its AI-powered smart car system; Plans to add its “navigation-on-autopilot” feature**; Plans CNY100B (~$14B) investment to develop smart cars features - China press
(UK) DEC CPI M/M: 0.4% V 0.2%E; Y/Y: 4.0% V 3.8%E (1st acceleration since spring 2023); UK ONS notes acceleration was also driven by a rise in tobacco duty in late Nov
(EU) ECB'S CHIEF LAGARDE: ECB LIKELY TO CUT RATES BY SUMMER [*Note: first major central bank head to provide specific forward guidance on rate cuts]
DPW.DE CEO: Container imbalances may start to appear in Asia; Concern in Red Sea context is that extending shipping routes could lead to a shortage of containers
1919.HK Exec: COSCO sees spot shipping rates may stay higher-for-longer; COSCO has also had to redivert some services via the Cape to the US East Coast given Panama Canal drought issues; Not seeing much evidence of box shortages or port congestion yet
HLAG.DE Enters operational cooperation with Maersk, starting Feb 2025; Targets delivering schedule reliability >90% once fully phased in; Hapag-Lloyd will leave THE Alliance end-Jan 2025
MAERSKB.DK *CEO: SEES RED SEA EVENTS LASTING ‘A FEW MONTHS’; TIMELINE CAN ALSO BE LONGER - DAVOS
(IR) Iran and Pakistan conduct joint naval drill in Gulf and the Strait of Hormuz [~20% of world's total oil consumption passes through it]
JPM Head of Asset Management: JPMorgan faces 45B attempted hacks daily; This number doubled in just one year
CFG Guides initial FY24 NII -9% to -6% y/y, NIM 2.80-2.85% v 2.85% in Q4 2023; Significant NII contribution from Non-Core and swaps in 2025 and beyond - earnings slides
USB Credit quality normalizing to pre-pandemic levels; Increases in delinquencies for the Commercial portfolio this quarter were primarily administrative in nature; Well-positioned for 2024 and beyond - earnings slides
(DE) German Economy Ministry spokesperson: Effect of Red Sea attacks makes delivery times up to 20 days longer on individual cases in industrial production sector
PLD Reports Q4 Core FFO $1.29* v $1.26e, Rev $1.89B v $1.78Be
(US) DEC ADVANCE RETAIL SALES M/M: 0.6% V 0.4%E (biggest jump since Sept); RETAIL SALES (EX-AUTO) M/M: 0.4% V 0.2%E
(US) DEC IMPORT PRICE INDEX M/M: 0.0% V -0.5%E; Y/Y: -1.6% V -2.0%E
(US) Fed’s Bowman (voter, hawk): The Fed should seek comments on any revised capital plan; Fed's Basel III proposal needs substantive changes to adjust known deficiencies
(US) Mid Jan Manheim wholesale used vehicle Index at 201.9, -1% m/m, -10.3% y/y
(US) JAN NAHB HOUSING MARKET INDEX: 44 V 39E
(US) Atlanta Fed GDPNow: Raises Q4 GDP from 2.2% to 2.4%
AA Reports Q4 -$0.56 v -$0.99e, Rev $2.60B v $2.61Be
DFS Reports Q4 $1.54 v $2.50e, Rev $4.20B v $4.10Be
DFS Guides initial FY24 avg Net Charge-offs rate 4.9-5.3% v 4.1% end-Q4 2023; Total opr expenses up mid single digits - earnings slides
(AU) AUSTRALIA DEC EMPLOYMENT CHANGE: -65.1K V +15.0KE; UNEMPLOYMENT RATE: 3.9% v 3.9%E
(IR) Pakistan confirms to have conducted retaliatory airstrikes inside Iran - press

THRS 1/18
CFR.CH Reports Q3 Rev €5.59B v €5.55Be, +8% y/y (cc); Americas Rev +8% y/y (cc) v +4.7%e
MAERSKB.DK *Reiterates it encourages its customers to prepare for there to be significant disruptions to the global network and complications in the Red Sea area to persist
TSM Reports Q4 (NT$) Net 238.7B v 226.4Be, Op 260.2B v 325.0B y/y, Rev 625.5B v 625.5B prelim
TSM *CFO: GUIDES Q1 REV $18.0-18.8B V $17.3BE; GUIDES FY24 REV STRONG; SEES REV CAGR 15-20% OVER NEXT SEVERAL YEARS; EXPECTS UTILIZATION RATE TO RISE FOR FY24 - EARNINGS CALL
WOSG.UK Cuts outlook assuming no recovery in consumer demand this FY; Despite a positive start to the early part of Q3 FY24, WOSG then experienced a volatile trading performance in the run-up to and beyond Christmas, as the challenging macro-economic conditions impacted consumer spending in the luxury retail sector
HUM Cuts FY23 $26.09 v $28.27e (prior: at least $28.25) citing higher medical costs/utilization and "more balanced" pricing; Reschedules earnings call to Jan 25th from Feb 5th; Expects individual Medicare Advantage (MA) growth of ~100K members, +1.8% y/y (prior: 'growth at or above industry growth level') - filing
TCOM CEO: Domestic China travel exceeded 2019 levels by over 50%; US still in top 3 travel destinations for China - Davo
(US) DEC HOUSING STARTS: 1.460M V 1.425ME; BUILDING PERMITS: 1.495M V 1.476ME
(US) JAN PHILADELPHIA FED BUSINESS OUTLOOK: -10.6 V -6.7E; Prices Paid: 11.3 v 25.1 prior
(US) DOE CRUDE: -2.5M V -1ME; GASOLINE: +3.1M V +2.5ME; DISTILLATE: +2.4M V -0.5ME
(US) NY Fed takes $618.2B (v $590.1B prior) in RRP program at 5.30%; 81 participating and accepted counterparties
(US) Office of the Controller of the Currency (OCC) Chief: OCC, Fed and FDIC are working on discount-window rule proposal, to push and "require" more banks to use the Fed's discount window at least once a year to reduce the stigma and be ready for troubled times - press
PPG Reports Q4 $1.53 v $1.50e, Rev $4.35B v $4.27Be; H1 conditions to remain subdued in US, Mexico; Believe European economic activity to stabilize in 2024 at current levels
SMCI Raises Q2 $5.40-5.55 v $4.48e, Rev $3.6-3.65B v $2.80Be (prior: $4.40-4.88, Rev $2.7-2.9B)
(JP) JAPAN DEC NATIONAL CPI Y/Y: 2.6% V 2.5%E; CPI EX-FRESH FOOD (CORE) Y/Y: 2.3% V 2.3%E (Core CPI slowest y/y growth since Jun 2022)
(US) New York Fed Report finds early delinquency rates rose for low-income borrowers in 2022 through Q3 2023, exceeding pre-pandemic levels
JBHT Exec: Guides initial FY24 Capex $800M-1.0B v $1.6B y/y; Not so much has changed in regard to the freight environment in early 2024; Seeing inflationary pressures in 2024, but mostly around its insurance premiums - conf call summary

FRI 1/19
(DE) German construction union IG BAU (~1M workers) said to be demanding a pay rise of over 20%, raising inflation fears - financial press
BAS.DE Cuts FY23 Rev €68.9B v €70.6Be (prior €73-76B v €87.3B y/y), EBIT €3.81B v €3.85Be (prior €4.0-4.4B); Notes Chemicals segment EBIT before special items in 2023 falls considerably short of average analyst estimates, among other things due to unplanned plant shutdowns, non-cash-effective impairments**
ABBN.CH Received US House Committee letter on strategic competition with China; States taking seriously
(EU) Reportedly EU preparing to launch mission in the Red Sea, expected to be adopted in Feb 2024; The new EU operation will accompany the British HMS Diamond - ShippingWatch
(US) NATO is mobilizing some 90,000 troops for its biggest military drills since the Cold War, called Steadfast Defender 2024 and starting next week - Axios
(CN) China cabinet said to have instructed heavily indebted local govts to delay or halt some state-funded infrastructure projects; Cites local govts' large debts and weaker growth prospects - press
(DE) Germany Defense Min Pistorius: Putin could possibly attack NATO in ‘5 to 8 years', according to our experts - Politico
HBAN Reports Q4 $0.27 adj v $0.26e, Rev $1.73B v $1.75Be; Believes the operating environment today is generally more constructive compared to last quarter; Customers are generally well positioned and are continuing to invest in their businesses
TRV Reports Q4 $7.01 v $5.01e, Rev $10.9B v $10.9Be
W To cut 1.7K jobs, or ~13% jobs globally; Now expect to deliver over $600M of Adjusted EBITDA in 2024 in a hypothetical flat revenue environment
MAERSKB.DK Implements temporary suspension of bookings to and from Asia/Middle East/Oceania/East Africa/South Africa to Djibouti port city, near the Red Sea on its Blue Nile Express service
ALLY Expect used vehicle values to stabilise in 2025 following three years of declines; Seasonally adj NCOs to peak in H1 2024; Guides initial FY24 NIM 3.25-3.30% v 3.35% y/y - slides
(US) Redfin: January is off to a slower-than-expected start for home sales, likely due to severe winter weather; US pending home sales rose 4.1% m/m in Dec (the biggest increase since September 2021); Mortgage rates posted the biggest monthly decline since 2008
(US) Fed's Goolsbee (non-voter for 2024); We are not off the Golden path, but have not reached the end of it either - CNBC
(RU) Russian troops reportedly plan a large-scale offensive in Ukraine in the summer 2024 - FT citing Ukrainian officials
(US) DEC EXISTING HOME SALES: 3.78M V 3.83ME
(US) JAN PRELIMINARY UNIVERSITY OF MICHIGAN CONFIDENCE: 78.8 V 70.1E
(US) Fed’s Bostic (dove, voter): Wants to make sure we're well on the way to 2% before cuts; Open to changing outlook on rate cut timing on if the data suggests it
(US) Weekly Baker Hughes Rig Count: 620 v 619 prior (+0.2% w/w)