FT : Copenhagen hits back as Berlin and Paris push to scrap rules on green suppl

Copenhagen hits back as Berlin and Paris push to scrap rules on green supply chains
Danish minister agrees reporting obligations for companies need simplifying, but insists on the new regulations’ merit

Denmark has rejected calls from Germany and France to scrap a planned EU supply chain law that has become symbolic of the bloc’s dilemma between meeting its ambitious climate goals and helping its ailing industry.

“We don’t agree” on abandoning plans to ask companies to monitor, report and take action against forced labour and mitigate the environmental impact of their operations outside the EU, Danish industry minister Morten Bødskov told the Financial Times.

Copenhagen will gain greater policy influence in Brussels when it takes over the rotating presidency of the Council of the EU in July. Denmark is one of the most ambitious countries in the bloc when it comes to adopting green legislation and pushing the EU to go even further than current targets and cut its greenhouse gas emissions by 90 per cent by 2040.

EU member states and the European parliament are currently negotiating the postponement of the supply chain rules, which are a key part of the bloc’s ambitious climate and human rights agenda.

But both Paris and Berlin have called for the law to be repealed altogether, saying the extra reporting requirements will only hurt the bloc’s competitiveness even further at a time when many European industrial sectors are struggling to keep up with Chinese and US competitors.

The CEO of a construction and logistics group that carries out projects in the US and Africa previously told the FT that it had begun to track more than 700 metrics to comply with the supply chain law at a cost of “several million” euros.

Bødskov acknowledged that the EU should look into simplifying the reporting obligations for companies, but insisted that “there are many, many positive sides to it that we have to remember”.

European Commission President Ursula von der Leyen has pledged to cut red tape, including climate-related legislation, to help close the competitiveness gap.

Bas Eickhout, a European lawmaker for the Greens, said the law had already been “heavily butchered” after the commission’s original proposal was heavily watered down and underwent further simplification efforts this year.

The EU’s internal watchdog opened an inquiry this week into the commission’s current attempt to rework the law, after NGOs said that the EU executive broke its own rules by failing to consult or do an impact assessment before proposing the simplification measures.

Implementing the EU’s simplification strategy is a priority for Denmark during its six months at the helm of the Council, said Bødskov, but a part of that debate is also “to remember that the goals were right, but some of it has developed into too much and to difficult to reach the goals.”

Bødskov’s remarks reflect growing concern among some EU countries that the EU’s push for “better regulation” could be used as a vehicle to dismantle green legislation.

“Better regulation is not deregulation, it’s simplification,” he said, to avoid moving Europe away from its climate targets.

“We have to keep the targets, but we have to make it much easier for our companies and businesses to invest in reaching these targets.”

FT : Europe’s largest shipbuilder calls on bloc to build up underwater defences

Europe’s largest shipbuilder calls on bloc to build up underwater defences
Fincantieri CEO says threat of attacks on subsea cables and other critical marine infrastructure will increase

The chief executive of Europe’s largest shipbuilder, Fincantieri, has called on European countries to scale up their underwater defence capabilities amid rising threats and the retreat of the US.

“The Mediterranean has always been populated by Russian and US submarines, it's up to us Europeans now to take responsibility for our underwater defence,” Pierroberto Folgiero told the Financial Times.

“If European countries are going to spend more on defence, we should spend better,” he added.

The Italian state-controlled shipbuilder announced last week that it expects its underwater division, which focuses on submarines, communication systems and autonomous vehicles, to double in size over the next two years reaching €820mn in revenue in 2027, equivalent to 8 per cent of the group’s current revenue.

It expects the global underwater economy to grow by €50bn a year as countries invest more in underwater defence and security.

Following the 2022 attack on the Nord Stream pipeline, governments have been scaling up underwater defence capabilities such as unmanned drone systems and anti-submarine technology.

Folgiero said the threat of attacks on subsea cables and other critical marine infrastructure was likely to increase and demand for technology and infrastructure that could prevent or minimise the impact of attacks would rise significantly.

“Attention has focused on the Baltic Sea following the outbreak of the war in Ukraine, but the Mediterranean is twice as big as the Baltic and a crucial juncture from a geopolitical perspective,” he said.

“This is why we are betting on underwater defence and technology and increasing our industrial capabilities.”

Fincantieri’s share price rose about 20 per cent last week to €15 a share after it said it would expand its underwater division.

It also announced a partnership with Graal Tech, an Italian technology group, to develop autonomous underwater vehicles.

Antonio Gianfrancesco, an analyst at investment bank Intermonte, said that “underwater is one of the key medium-to-long-term catalysts for [Finacantieri’s] equity story”.

Last year the company, which specialises in both military and civil shipbuilding, announced a €415mn deal with defence group Leonardo to take over its WASS submarine division. In 2023, it bought Remazel, an Italian engineering company focused on offshore equipment manufacturing.

Fincantieri, which failed in its 2020 merger attempt with France’s Chantiers de L’Atlantique amid opposition in France and EU competition concerns, has experienced strong growth since the pandemic. It has shipyards across the world, including in the US, and has had a surge in global orders.

Last week it said its earnings in the first quarter of 2025 rose 35 per cent to €2.37bn compared with last year. The value of its order backlog reached a record €57.6bn or seven times its 2024 yearly revenues.

FT : ExxonMobil and Chevron to do battle over $1tn oilfields in Guyana

ExxonMobil and Chevron to do battle over $1tn oilfields in Guyana
Dispute over stake in Hess’s Stabroek oilfield has implications for joint operating agreements between companies

A bitter dispute between ExxonMobil and Chevron over ownership of a gigantic oil project with up to $1tn in reserves is scheduled to be heard before an arbitration court in London on Monday, in a case with big implications for both companies and the wider industry.      

The US supermajors are battling over the right to acquire a 30 per cent stake in Guyana’s Stabroek oilfield which is owned by Hess, a US energy company that agreed to a $53bn takeover by Chevron in September 2023.

Exxon, which owns 45 per cent of Stabroek, claims it has “right of first refusal” to buy Hess’s stake in the oilfield under the terms of a joint operating agreement (JOA) with Hess and another partner, Cnooc, the Chinese oil and gas company. Cnooc, with 25 per cent of the oilfield, has filed a claim seeking the same pre-emption right.

Lawyers are monitoring the International Chamber of Commerce arbitration to determine whether future JOAs will need to be updated to reflect the outcome of Exxon’s case, which involves pre-emptive rights — contractual provisions giving a party the right to buy an asset before it is offered to others.

Stabroek is one of the most lucrative oil discoveries in recent decades with an estimated 11bn barrels of oil reserves and further exploration likely to increase this figure. The project has transformed Exxon’s fortunes, enabling it to reclaim its position as the most valuable US oil company after briefly being eclipsed by Chevron in October 2020.

Over the next 15 years Exxon and its partners are forecast to generate $182bn in profits from oil and gas sales from the Guyana oilfields, according to Wood Mackenzie, an energy consultancy. Guyana’s government should receive more than $190bn, a vast sum for a country that was one of the poorest in South America until Exxon struck oil in 2015.

“Guyana is one of the most prized oil and gas projects on the planet. It was developed in record time, provides comparatively low-emissions oil at a break-even price that is below $30 a barrel, which makes it super profitable,” said Luiz Hayum, an analyst at Wood Mackenzie.

Chevron, which is not a direct participant in the arbitration case, is desperate to push ahead with its Hess acquisition to access the company’s Guyana assets. Last year Chevron’s oil and gas reserves fell to 9.8bn barrels, down from 11.1bn barrels in 2023, the lowest in more than a decade.

Mike Wirth, Chevron chief executive, has said he is confident the company will prevail over Exxon. “This has been studied extensively, and we feel like they clearly have the right side of this argument,” he told a Goldman Sachs conference in January.

In March, Chevron disclosed it had bought almost 5 per cent of Hess shares on the open market, an unusual move which analysts interpreted as a sign the company is confident the long-delayed transaction will proceed.

But Exxon chief executive Darren Woods has also talked up the company’s prospects and claimed last year it is “standing up for what we believe is a fundamental right”.  

The hearing will be held in private before a three-judge panel. Sources close to the process told the Financial Times the case probably hinges on the interpretation of a few words related to pre-emptive rights in the JOA, which has not been published by any of the parties.

Lawyers for Hess are expected to argue that a right of first refusal clause contained in the JOA only applies when one of the partners seeks to sell the Guyana assets, and not in a corporate takeover. Exxon is expected to argue the clause covers Chevron’s takeover of Hess because the Guyana assets makes up about 70 per cent of the value of the entire company.

“Exxon will argue Hess is basically a huge Guyana asset and a bunch of rats and mice. In other words, everything else is pretty insignificant,” said one veteran oil executive with experience of JOAs.

David Hoffman, a professor of law at University of Pennsylvania, said the outcome could shape how future JOAs are drafted.

“Because so much money is at stake here I’m sure the relevant lawyers will understand what the dispute is about and they are going to know who wins and they are going to try and adjust their practice accordingly,” he said.

Analysts said the outcome was more important for Chevron than Exxon because of the company’s need to find growth opportunities and boost its oil reserves.

“If Mike Wirth completes Hess he is in good shape to retire and leave his era in charge as a hero. But if Chevron loses then he may need a different big deal, like Oxy [Occidental Petroleum], to cement his long legacy,” said Paul Sankey, an oil analyst.

(ZH) An Unstoppable Bull Market?

An Unstoppable Bull Market?

Even Trump Can’t Kill The Rally
Last week, we discussed how the rally had repaired much of the previous damage following the correction. As we noted:
“This past week, the market continued its advance. There is little reason to be bearish with key overhead resistance levels broken. However, as shown, the markets are reaching decently overbought levels after being extremely oversold. This suggests that at least for now, the “easy money” has been made. With the market above the 200, and above the 50 and 20-DMA, pullbacks should be between 5600 and 5800. Investors can use such a pullback to increase portfolio equity exposures and reduce hedges accordingly. Conversely, 5000 to 5200 becomes the next critical target if those lower supports are violated. Notably, such would require some unexpected event to unfold.”
Several times this past week, we discussed that the market was due for a corrective pullback after reaching more overbought conditions. On Friday, the market gave way early in the morning on fresh comments by President Trump instituting 25% tariffs on Apple (AAPL) on any product not manufactured in the U.S. and 50% tariffs on the EU, as trade talks are not going well. As is always the case, amid a bull run, sellers are still unwilling to sell over fear of “missing out” on rising asset prices. It takes some “event” to bring sellers into the market, which we saw early on Friday.
However, by late afternoon, markets bounced off the 200-DMA and clawed their way higher as comments from Scott Bessent took the sting out of Trump’s announcements. Most importantly, he made two significant statements to alleviate concerns over the recent yield rise. First, he expects the US budget deficit “to be something with a 3% in front of it by 2028,” with revenue from tariffs to be used to solve the deficit. This is crucial as the CBO projections of never-ending deficits do not consider the effects of policy changes that can lead to economic growth. Tax cuts, deregulation, the coming productivity boost from Artificial Intelligence, or the infrastructure demand for power can significantly impact future growth rates.
Secondly, he specifically mentioned the SLR. The Supplementary Leverage Ratio (SLR) is a rule imposed after the 2008 financial crisis that increased bank capital requirements. This is particularly interesting to the bond market, where reversing that requirement will allow banks to purchase more Treasury Bonds. Bessent noted in his interview that the Treasury is close to “moving the SLR requirement and could see that move by the summer.” That shift in the SLR requirement is very bond-friendly and will work to bring rates lower. (For more, read our Daily Market Commentary from last week.)
Technically Speaking
Even with Bessent’s comments, that market remains overbought short-term, and a further consolidation process is likely into next week. At the end of this week, we removed our short-market hedge, added to bonds, and reduced equity exposure. If the market is going to consolidate, we can allow cash to act as the primary hedge. However, if the 200-DMA is violated, the 50-DMA will become the next critical support. From a bullish perspective, the 20 and 50-DMAs are now sloping positively, which should provide rising support levels. Overall, we suspect that the market will stabilize. Of course, there are always risks to be aware of, so increased cash levels are essential now.
We are not “bearish” on the market because buybacks remain a powerful market influence over the next month. The recent surge has been the largest since the October 2022 market lows. However, those will begin to fade in the middle of June, which could weigh on markets into the Q2 earnings reports.
For now, this seems to be an “unstoppable” bull market, and investor spirits have become substantially more bullish. However, all rallies eventually end. That doesn’t mean a “crash” is coming, and as noted last week, the market is holding the 200-DMA for now. This suggests the previous correction phase is likely complete with support gathering at slightly lower levels. However, there is never a guarantee, so we have taken some recent gains and raised cash levels. We will be patient for a much better entry point soon.
With that said, let’s discuss how to navigate a seemingly “unstoppable” bull market.
Retail Buyers Go “All In”
Last week, we started the market update by analogy between the COVID pandemic decline and this year’s correction. As we noted:
“It is worth remembering that there are many competing differences between the current macroeconomic backdrop and 2020.”
“However, as we discussed in that previous analysis, even a “unstoppable bull market” gives those who can be patient better risk/reward opportunities to increase equity exposures. For example, after the initial rally off the March 2020 lows, the market pulled back and consolidated briefly before rallying further. Then, another longer consolidation process that year provided another entry point for bullish investors.”
“The weekly Technical Gauge we produce each week in this newsletter below follows the same path as 2020. While not yet back to bullish technical extremes, it is moving quickly higher to more elevated levels. When those readings reached 80, the market went through a longer consolidation process in 2020.”
Most interesting is that retail investors have been fueling the market’s advance. As noted in our #DailyMarketCommentary:
“Monday was a record-setting day. Stocks opened down 1% on news that Moody’s downgraded the US credit rating to AA. While some perceived the downgrade as problematic, retail investors, aka individuals, bought stocks at the highest rate ever. Per JP Morgan, retail investors purchased a net of $4.1 billion of US stocks in the first three hours of trading. As their graph below shows, Monday’s retail buying stampede dwarfs prior instances”
While the retail net inflow was quite impressive, it does leave the bulls and bears with a consideration. We should ask ourselves who the retail investors bought the stock from. The answer, by default, is institutional investors. This trend of retail buying from institutional investors has been ongoing. As we wrote in “Smart Money or Dumb Money: Who Will be Right?“
Smart money (institutions and hedge funds) is aggressively selling this market while individual investors, aka dumb money, are aggressively buying. The difference in opinions is stunning.
The data below confirms that view, with the recent stretch of Hedge Fund short selling remaining unprecedented and reflective of some skeptics. Over the past 3 COT reports, Hedge Fund shorts surged ~$25bn – the largest amount for at least the past 10 years.
Viewed through another lens, Hedge Fund shorts as a percentage of total open interest reached 41% – the max dating back to February of 2021.
Typically, institutional investors tend to be right. However, in the short term, particularly over the last few years, retail investors have been heavy buyers of corrections. The only question is whether retail investors run out of money before institutions are forced to cover?
Valuations Take A Back Seat
That said, the rally so far seems unstoppable. Every time the market opens lower, as on Friday following Trump’s tariff increase, buyers step in. As such, the patience needed to wait for a correction has been hard to come by. As noted previously, we remain bullishly biased but expect a pullback.
“We must remember that market advances can only go so far before an eventual correction occurs. My best guess is that if the markets are to reach all-time highs this year, we will likely have a correction to reset some of the more extreme overbought conditions, as shown below. Any pullback to the 50-DMA is likely a good entry point to increase exposure on a better risk/reward basis.”
The bull market that started in October 2022 has surprised many, given the number of traditionally more bearish indicators, such as inverted yield curves, leading economic indicators, and rising interest rates. For many individuals, trading a rising stock market is difficult because they expect the inevitable resumption of the “bear market.” However, as the market continues to rise, investors are pressured to buy equities, creating more demand, thereby pushing asset prices even higher.
The bullish bias is evident in the long-term relationship between stocks and bonds. The ratio of stocks to bonds has far exceeded that of the “Financial Crisis,” and is now on par with the “Dot.com” bubble peak, with a similar sharp slope higher.
Does that mean the market is about to “crash?” No, but there is an apparent correlation between the detachment of stocks to bonds and historical valuation metrics. However, in the short term, all that matters is price. As discussed in “Technical Measures,“ valuations are a terrible market timing tool. Valuations only measure when prices are moving faster or slower than earnings. In the short term, valuations are just a measure of psychology. To wit:
“Valuation metrics are just that – a measure of current valuation. More importantly, when valuation metrics are excessive, it is a better measure of ‘investor psychology’ and the manifestation of the ‘greater fool theory.’ As shown, there is a high correlation between our composite consumer confidence index and trailing 1-year S&P 500 valuations.”
The chart indeed suggests that investors should sell everything immediately. However, given that this is monthly data, these turns can and do take much longer than expected. This “lag” leads investors in the short term to believe that “valuations” no longer matter. Such is a dangerous assumption that investors paid dearly for in the past. Valuations do matter, and they matter a lot, just not today.
Therefore, when investors are caught in an “unstoppable” bull market, we must revert to price analysis and trading rules to navigate the markets.
Navigating An Unstoppable Bull Market
There are millions of ways to approach technical analysis, and investors use millions of combinations of technical indicators to decipher market movements.
I am only going to discuss how we do it with you.
Notably, technical analysis does NOT predict the future. It is the study of historical price action, which is the purest representation of the psychology of market participants. From that study, we can make statistical observations about the behavior of market participants in the past. Those assumptions can help form a “guess,” assuming similar variables, about how they may act in the near term.
For our portfolio management needs, we keep our analysis very simple. We use one indicator to indicate if prices are overbought or oversold, two moving averages to determine the trend of prices, and Bollinger bands to warn of significant deviations from those moving averages. I show the technical setup in the sample chart below from SimpleVisor.com.
When markets rise, we look for “warning signs” that stocks could be due for a short—or intermediate-term corrective period. Conversely, during market declines, we look for indications that markets are oversold and ready to advance. Currently, we are dealing with the former.
Historically, when prices move toward the upper bands of 2- or 3-standard deviations above the 50-day moving average (dma), the Williams %R is overbought, and the MACD is crossing lower from a high level, stock prices generally correct to some degree. Such is the potential environment we will likely deal with in the next few weeks as earnings season concludes and the corporate buyback window closes. This is also why we have suggested holding off trading portfolios and increasing cash levels until some of these more overbought conditions are corrected.
But that is difficult to do in an “unstoppable” market advance.
Trading An Unstoppable Market
It’s not as hard as you think, once you conquer the emotional side of the equation.
Commandment #1: “Thou Shall Not Trade Against the Trend.” – James P. Arthur Huprich
Let me be very clear. We are discussing risk management. You must understand the market’s overall trend and when it is changing. The negative price trend of 2022 is now over, and since then, the market has continued to trend positively. While you can argue, fight, and provide all the reasons why “the game is rigged,” the fact is that the market continues to push higher. Those participating are building wealth, those who aren’t…well…aren’t. You have a choice.
We are in a “bull market.”. As such, we want to maintain our exposure to equity risk. However, this does not mean we should ignore what the market tells us and let the ebbs and flows wash over us. Eventually, another “ebb” will come, and we will want to reduce risk accordingly. That does not mean selling everything and going to cash.
“In a bull market, you can be either long or neutral. In a bear market, you can only be neutral or short.” – Dennis Gartman
The market will eventually pull back, and likely soon. During that correction, prices will likely remain confined to the 50-dma, as noted above. Could a correction be larger? Yes. The market is currently overbought and extended, so we suggest that investors manage risk and remain cautious about committing cash reserves to the market. However, we will want to use corrections that reverse those overbought and extended conditions as an opportunity to increase equity exposure.
“Willingness and ability to hold funds uninvested while awaiting real opportunities is a key to success in the battle for investment survival.” – Gerald Loeb

(ZH) Long-Term Prospects "Bode Well" For Nuclear, Goldman Says After Trump Signs

Long-Term Prospects "Bode Well" For Nuclear, Goldman Says After Trump Signs Executive Orders

Following President Trump's signing of multiple executive orders accelerating development of the nuclear industry, Goldman Sachs was out with a note maintaining a positive outlook on the nuclear energy sector, especially in the near to medium term, focusing on opportunities related to uranium fuel supply and the upstream part of the nuclear value chain.
In the note, Goldman, led by analyst Brian Lee, reiterates its Buy rating on Cameco Corporation while also seeing potential in companies focused on small modular reactor (SMR) technologies.
Goldman Sachs believes the new orders could be beneficial for Cameco, a major uranium producer, as increased demand for nuclear power generation would likely raise the need for physical uranium and related fuel conversion services. This impact would be more visible over the longer term.
In the shorter term, Goldman highlights the potential benefit to Westinghouse, in which Cameco holds a 49 percent stake. Westinghouse could see more immediate gains if its reactor technology, particularly the AP1000 design, is selected for upcoming nuclear projects.
Uranium
For companies involved in small modular reactors, there is potential upside if the executive order leads to specific allocations of loan funding for SMR development. Such support could be directed toward both civilian energy infrastructure and defense-related power needs, Lee and his team said.
Recall, on Friday, President Donald Trump signed a series of executive orders designed to fast-track the development and deployment of advanced nuclear reactors on Friday culminating a dramatic policy shift aimed at revitalizing the U.S. nuclear energy sector.
Flanked in the Oval Office by Secretary of Defense Pete Hegseth and Interior Secretary Doug Burgum, Trump declared nuclear power “a hot industry” and praised it as “very safe and environmental.”
Burgum called it “a huge day for the nuclear industry,” and added, “Mark this day on your calendar. This is going to turn the clock back on over 50 years of over regulation of an industry.”
In terms of valuation, Goldman sets a twelve-month price target of $65 for Cameco’s U.S. listing and C$89 for its Toronto listing. These valuations are based on a sum-of-the-parts approach that incorporates different valuation multiples for uranium production, fuel services, and Westinghouse’s contributions.
Key risks to this outlook include fluctuations in commodity prices, disruptions in mining operations, timing issues related to contracts and deliveries, and potential delays in nuclear project construction.
For SMR, Goldman assigns a twelve-month price target of $24. This estimate is derived from a blend of discounted cash flow analysis and revenue-based valuation, using longer-term forecasts and applying a relatively high discount rate to reflect risk.
The primary concerns for SMR include execution challenges, ongoing funding needs, uncertainty around customer demand and regulatory approvals, and the final delivered costs of reactor modules.
Recall, the new orders aim to strip away what the administration describes as decades of regulatory overreach that have stifled innovation and stagnated the industry. “America’s greatness has always come from innovation,” Burgum said on Friday. “We led post-World War Two in all things nuclear. But then we’ve been stagnated. We’ve choked it with over regulation.”
The first of Trump’s executive orders directs the Department of Energy (DOE) to accelerate research and development, speed up reactor testing at national labs, and initiate a two-year pilot program for reactor construction.
A second order clears regulatory hurdles for the DOE and the Department of Defense (DOD) to build reactors on federal land — efforts that will bypass the Nuclear Regulatory Commission (NRC) entirely by using the agencies’ own regulatory authority.
“We’re going to do a lot of the small ones, and we’re going to do some of the big ones,” Trump said. “But yeah, very safe, safe and clean.”
The third order takes direct aim at the NRC itself. It mandates “a total and complete reform of NRC culture to reorient to ensure reactor safety and promoting the development and adoption of nuclear technology.” The order sets a new requirement that the commission rule on new license applications within 18 months, far faster than the current average of five years.
In support of this agenda, Hegseth underscored the national security implications, especially in powering AI infrastructure: “We’re including artificial intelligence in everything we do. If we don’t, we’re not fast enough, we’re not keeping up with adversaries. You need the energy to fuel it. Nuclear is a huge part of that, modular or otherwise. So we’re going to have the lights on and AI operating when others do not faster than everybody else because of nuclear capability.”
The fourth nuclear-focused order targets America’s uranium supply chain, aiming to “reinvigorate” the domestic nuclear industrial base. It calls for expanded uranium mining and enrichment, while also instructing Energy Secretary Scott Wright to evaluate policies for nuclear material recycling and reprocessing. A senior official explained, “That means America will start mining and enriching uranium and expanding domestic uranium conversion and enrichment capacity.” Nonproliferation and security considerations will guide those efforts.
Trump’s orders reflect a clear strategic intent: to restore the U.S. as a global leader in nuclear energy and science. Michael Kratsios, director of the White House Office of Science and Technology Policy, said the executive actions would “ensure continued American strength and global leadership in science and technology.”
He lamented the U.S. decline in nuclear progress, saying, “We decommissioned commercial reactors across the country, stepped back from nuclear R and D and abandoned hopes of nuclear energy, power and a bright future. America’s great innovators and entrepreneurs have run into brick walls when it comes to nuclear technologies.”
Kratsios declared that Trump is “telling the world that America will build again and the American nuclear renaissance can begin.”
With energy demands soaring due to AI and data center growth, industry giants like Microsoft, Oracle, Google, and Amazon are now investing in or exploring small modular reactors to power their operations. The administration sees this as a critical opportunity for the U.S. to lead again. “Nuclear energy is necessary to power the next generation technologies that secure our global industrial, digital, and economic dominance, achieve energy independence, and protect our national security,” a White House official said.
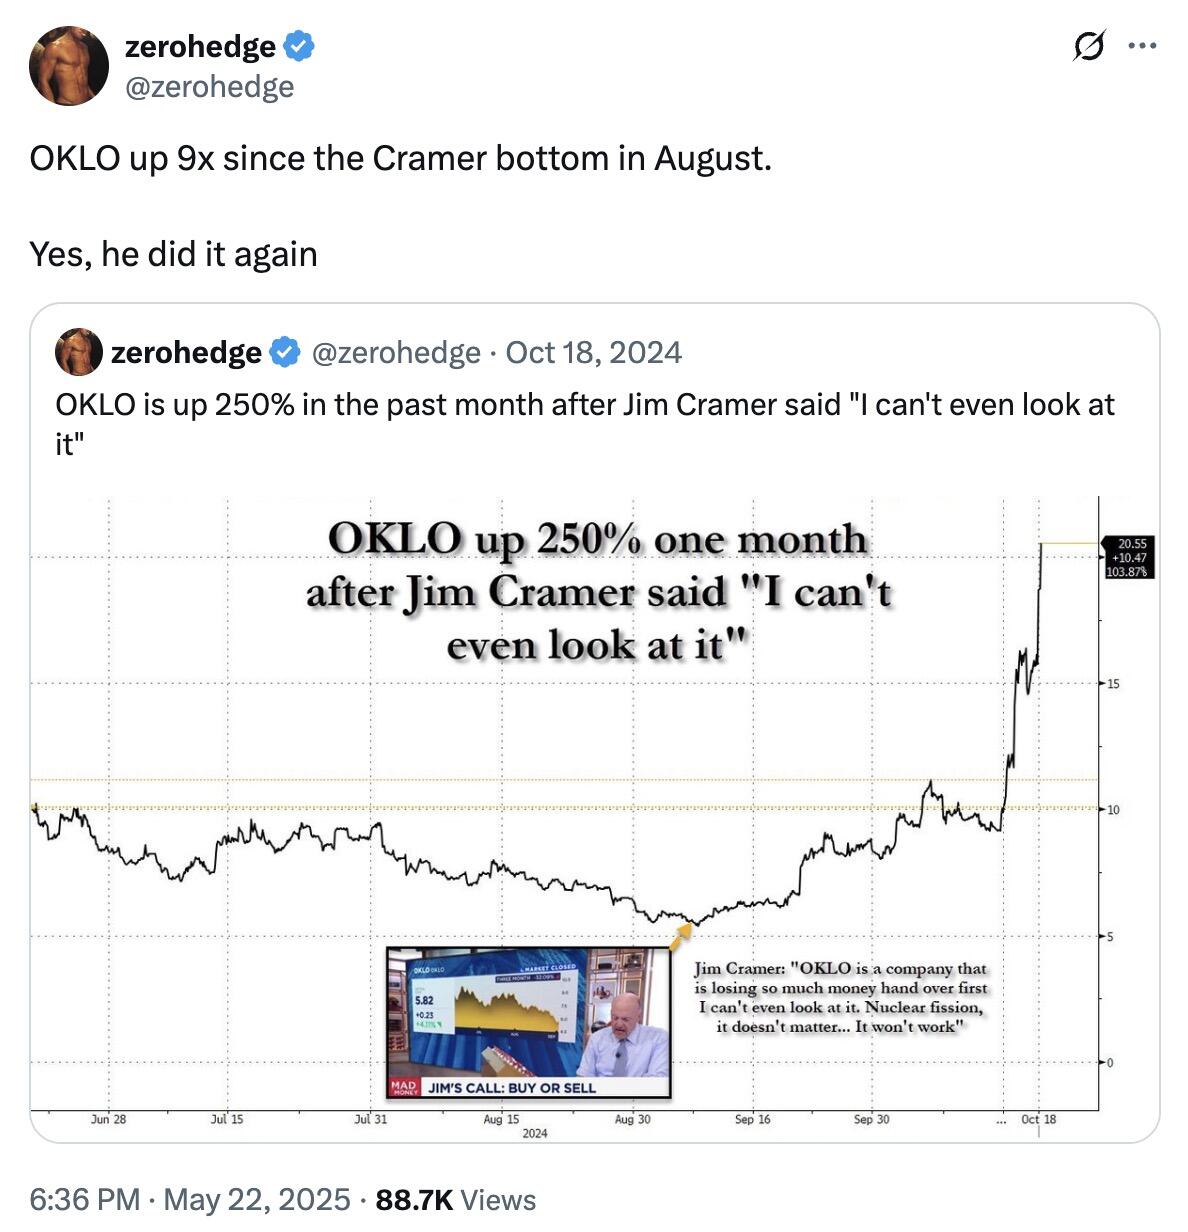
Nuclear stocks soared last week on the news of the order. And as we noted on X last week, OKLO is now up 10x since Jim Cramer said "I can't even look at it" back in October 2024.
Booyah!
On Oklo’s Q1 2025 earnings call earlier this quarter, CEO Jacob DeWitte confirmed the company is engaged in a “pre-application readiness assessment” with the NRC, aiming to smooth its formal license submission for a newly upsized 75-MW reactor design in Q4 2025. The company still targets late 2027 or early 2028 for first power production at its Idaho National Laboratory (INL) site.
DeWitte noted the recent departure of OpenAI CEO Sam Altman as Oklo board chair removes a potential conflict of interest should OpenAI become a future power customer. Oklo already holds about 14 GW in nonbinding agreements with data centers and industrial operators.
A UtilityDive report said that Zero Hedge favorite Oklo is also among eight companies eligible for the military’s Advanced Nuclear Power for Installations program, enabling on-base reactor deployments. It’s developing nuclear fuel fabrication facilities capable of reusing spent fuel that would otherwise sit in long-term storage.
For those who missed it, in our original note "The Next AI Trade" from April 2024, more than one year ago, we outlined various investment opportunities for powering up America, most of which have dramatically outperformed the market since then.
For those that missed that note, we pointed out on Friday all the ways to still profit.
Meanwhile the entire world has been jumping on the nuclear power bandwagon.
  • United States: Major tech. companies have come out in support of nuclear to help power AI data centers, and in places like Pennsylvania, local politicians are pushing for quick restarts and refreshes of nuclear plants like Three Mile Island. President Trump's goal is to quadruple nuclear capacity over 25 years.
  • China: China leads the world in nuclear construction, with 30 reactors being built, including the massive Lianjiang plant with six advanced CAP1000 reactors. The country sees nuclear as key to reducing emissions and meeting energy needs.
  • India: India is pushing forward with 10 new heavy water reactors, each generating 700 MW, to be built in a faster “fleet mode.” This expansion will help meet growing power demand and reduce coal reliance.
  • Japan: After years of hesitancy post-Fukushima, Japan has restarted several nuclear reactors and plans to extend their lifespans. The government is also supporting the development of next-generation reactors to reduce energy imports and cut carbon emissions.
  • Germany: Facing high energy costs from phasing out nuclear, Germany is rethinking its position. Discussions are underway about using small modular reactors and cooperating with France on nuclear energy.
  • France and the UK: Both countries are extending the life of existing plants and investing in new large-scale and small modular reactors to strengthen energy security and meet climate goals.
  • Nordic countries:
    • Sweden: Plans to build new reactors and extend the life of existing ones, aiming for stable, fossil-free electricity.
    • Finland: Recently completed the Olkiluoto 3 reactor, the largest in Europe. It now supplies about 14% of Finland’s electricity.
    • Denmark: Considering lifting a 40-year ban on nuclear energy, spurred by small modular reactor interest and regional trends.
As of late 2024, 63 nuclear reactors were under construction worldwide. Three-quarters of these are in emerging economies, and half are in China. The International Atomic Energy Agency projects that global nuclear capacity could more than double by 2050 to support clean energy goals.
In other words, we could very well still be in the early innings of this renaissance...
For even more including a deep dive into the nuclear technology, the nuclear fuel cycle, the uranium supply-demand model, pricing and contracting, and all the companies and major players in the place, read the full "Nuclear Playbook For Energy Transition" report available only to professional subscribers.

FT : Oil chiefs warn of end to US shale boom

Oil chiefs warn of end to US shale boom
Companies cut spending and idle thair drilling rigs despite Donald Trump’s pledge to ‘unleash’ production

US oil companies are cutting spending and idling drilling rigs, as Donald Trump’s tariffs push up costs and falling crude prices squeeze profits, prompting executives to warn that a decade-long shale boom is ending.

Surprise decisions by the Opec+ cartel to pump more oil have compounded the gloom across the US oil patch, sparking fears of a new price war and prompting analysts to cut output forecasts.

“We’re on high alert at this point,” Clay Gaspar, chief executive officer at Devon Energy in Oklahoma City, told investors this month. “Everything is on the table as we move into a more distressed environment.”

Oil output will fall by 1.1 per cent next year to 13.3mn barrels a day, according to S&P Global Commodity Insights, as prolific shale drillers that made the US the world’s biggest producer idle rigs in the face of prices driven lower by fears of oversupply and Trump’s trade war.

That would mark the first annual decline in a decade, excluding the 2020 pandemic when collapsing demand sent oil prices below zero and triggered widespread bankruptcies across states such as Texas and North Dakota.

US oil prices settled lower again on Friday, ending the week at $61.53 a barrel, down about 23 per cent from its high point this year. Shale producers need an oil price of $65 a barrel to break even, according to the quarterly energy survey by the Federal Reserve Bank of Dallas.


“The watchword now is, ‘hang in there’,” Herbert Vogel, chief executive officer at SM Energy in Denver, said at the Super DUG conference in Fort Worth.

A fall in production would end a stunning run in US energy, where the shale revolution delivered ever greater volumes of cheap oil and gas to power the economy, a boost to GDP and labour markets, and an export surge that improved the country’s trade balance.

Soaring shale output has also broken the US’s dependence on foreign suppliers such as Saudi Arabia and other Opec cartel members, while freeing the White House to target exporters such as Iran, Russia and Venezuela with sanctions.

Trump has promised to “unleash” more drilling and production in a bid to secure US “energy dominance”. But production, which hit a record high under his predecessor Joe Biden, could fall still further if prices keep sinking.

Scott Sheffield, the former head of shale driller Pioneer Natural Resources, told the Financial Times that if crude drops to $50 a barrel, US production would probably lose up to 300,000 barrels a day — more than the total output of some smaller Opec members.

Riyadh’s decision to pump more oil in recent months would be a direct threat to US producers’ share of the global market, he suggested.

“Saudi is trying to regain market share and they’ll probably get it over the next five years,” Sheffield said.

The onshore US oil rig count, a barometer of drilling activity, was 553 last week, down 10 since the week earlier and 26 lower than a year ago, according to oilfield services company Baker Hughes.


Some big producers are already shedding jobs. Chevron and BP have between them announced 15,000 job cuts globally, though in the US so far employment in the sector has remained relatively stable this year, according to the US Bureau of Labor Statistics.

The top 20 US shale producers, excluding ExxonMobil and Chevron, slashed their 2025 capital expenditure budgets by about $1.8bn, or 3 per cent, according to Enverus, an energy research firm.

“As operators, we cannot control the macro, but we can control how we respond,” said Vicki Hollub, chief executive of Occidental Petroleum, which cut rig count by two in the first quarter.

Many companies will slash more if prices hit $50 a barrel — the price Trump officials have indicated would help tame inflation.

“In this environment, we drop the rigs and buy back stock,” said Travis Stice, chair and chief executive officer at Diamondback Energy, which recently warned investors US oil production has probably peaked. “Every single conversation I’ve had is that this oil price won’t work.”

But the president’s other policies are also rattling the sector. Tariffs have pushed up the prices of steel and aluminium — crucial inputs in the oil patch. The price of casing, the metal used to line wells and the largest expense to drill a well, has risen 10 per cent in the past quarter alone.

“The economics will be challenged. We’ll see more capital pullback as the quarters progress,” said Doug Lawlor, chief executive of Continental Resources, one of the country’s biggest privately held energy companies.

That will force companies to batten down the hatches further as they try to keep Wall Street investors happy by protecting free cash flow to pay dividends and repay debt.

“You have to focus on dividends, they’re sacrosanct in this environment,” said Jim Rogers, partner at Petrie Partners, a boutique investment firm in Houston.

TechCrunch : Why Intempus thinks robots should have a human physiological state

Why Intempus thinks robots should have a human physiological state

Teddy Warner, 19, has always been interested in robotics. His family was in the industry, and he says he “grew up” working in a machinist shop while in high school. Now Warner is building a robotics company of his own, Intempus, that looks to make robots a bit more human.

Intempus is building tech to retrofit existing robots with human-like emotional expressions to help humans better interact with these machines and better predict their movements. Giving these robots human-like reactions will also produce data that can be used to better train AI models.

These robots will show expression through kinetic movements, Warner told TechCrunch.

“Humans derive a lot of our subconscious signals, not from face, not from semantics, but solely from the movement of your arms and your torso,” Warner said. “This extends to dogs and cats and other animals that aren’t humans.”

Warner said he got the idea for Intempus while he was working at AI research lab Midjourney. He said Midjourney, like many other AI research labs, was working on world AI models, or AI models that understand and make decisions based on the dynamics of the real world and spatial properties, as opposed to just cause and effect.

But it will be really hard for these models to achieve this spatial reasoning, Warner realized, because a lot of the data the models were being trained on came from robots that didn’t have this spatial reasoning, either.

“Robots currently go from A to C, that is observation to action, whereas humans, and all living things, have this intermediary B step that we call physiological state,” Warner said. “Robots don’t have physiological state. They don’t have fun, they don’t have stress. If we want robots to understand the world like a human can, and be able to communicate with humans in a way that is innate to us, that is less uncanny, more predictable, we have to give them this B step.”

Warner took that idea and started to research. He started with fMRI data, which measures brain activity by detecting changes in blood flow and oxygen, but it didn’t work. Then his friend suggested trying a polygraph (lie detector test), which works by capturing sweat data, and he started to find some success.

“I was shocked at how quickly I could go from capturing sweat data for myself and a few of my friends and then training this model that can essentially allow robots to have an emotional composition solely based on sweat data,” Warner said.

He’s since expanded from sweat data into other areas, like body temperature, heart rate, and photoplethysmography, which measures the blood volume changes in the microvascular level of the skin, among others.

Warner launched Intempus in September 2024 and spent the first four months exclusively on research. He’s spent the last few on a mix of building up these emotional capabilities for robots and engaging potential customers. He’s already signed seven enterprise robotics partners.

Intempus is also part of the current cohort of Peter Thiel’s Thiel Fellowship program, which gives young entrepreneurs $200,000 over two years to drop out of school and build their companies.

Warner said the next step for Intempus is to hire — he’s done everything until now as a team of one — and get some of the tech that’s already been built in front of humans to start testing. While Intempus is currently working on retrofitting existing robots and plans to focus on that, Warner said he’d never rule out Intempus building its own emotionally intelligent robots in the future.

“I have a bunch of robots, and they run a bunch of emotions, and I want to have someone come in and just understand that this robot is a joyful robot, and if I can innately convey some emotion, some intents that the robot holds, then I’ve done my job properly,” Warner said. “I think I can, you know, really prove that I’ve done this over the next four to six months.”

WWD : A Lot to Sea: Inside the World of Superyacht Design

A Lot to Sea: Inside the World of Superyacht Design
With price tags reaching into the mid-nine figures, bespoke boats are full of technical and aesthetic feats.
In mid-May, Amor à Vida, a new superyacht, set out on her maiden voyage. The boat, which features a sleek and sloped white exterior, made its photogenic debut at the Ferretti Group shipyard in Ancora, Italy, earlier this year. But what’s inside the boat remains a mystery — to most.

Italian design firm Nuvolari Lenard, responsible for both the exterior and interior styling, possesses an intimate understanding of the yacht, which boasts eco-friendly systems onboard.

“ Nobody comes here to get a copy of something else,” says Dan Lenard, whose three-plus decade design collaboration with business partner Carlo Nuvolari melds technical engineering and aesthetic design. “Each of [our boats] is iconic enough to be a brand by itself, so that really forces us every time to invent something completely different and speak a completely different language in design.”


Nuvolari Lenard was responsible for the striking exterior design of the 122-meter Kismet, built by German shipyard Lürssen, which launched last year and won motor yacht of the year at the most recent Superyacht Awards.


Kismet’s exterior features an elongated stainless steel bow with a leaping jaguar — a nod to owner Shahid Khan’s NFL team, the Jacksonville Jaguars. “Nothing looks like Kismet right now,” claims Lenard, describing its design as “neoclassical” and “postmodern.” “Now, Kismet sets the standards.”
Kismet, built by Lürssen.
Courtesy

The world’s 50 largest yachts all fall in the 110-plus-meter range, with the largest currently topping out at 180 meters. While Kismet has received a lot of attention since its launch, other impressive yachts fly intentionally under the radar.

“Boats like Nord are very private, very silent, going to very remote places where there is a lack of Instagram-chasers,” Lenard says of the 141-meter Lürssen-built boat, currently owned by Severstal chairman Alexei Mordashov, describing it as “probably the most complex boat ever built.”

“Unfortunately, it’s also so private that there’s not really much known about it,” he says. “Nord is built to go basically anywhere and be totally autonomous — but that doesn’t mean just that it can move. There is so much hiding in that boat that allows everything from exploring to underwater archeology, and these things are really complex to include in a boat that primarily is a very nice place to be. Very nice interior, very nice and pleasant spaces — and behind that, it’s hiding all these functions.”
Nord, built by Lürssen.

When it comes to the interior vision, Nuvolari Lenard’s approach is rooted in celebrating the owner’s individual aesthetic and interests.

“ What you do is you maximize the dream of the owner,” Lenard says. “I often say that we are paid to start dreaming from the point that the owner cannot dream anymore. We are expanding that dream into the next level.”

Beyond that, “The common factor of all of [these interiors] is really quality and attention to detail,” says Lenard, citing the level of quality as best-of-best of any field. “There’s no hotel built like a super yacht, and quite frankly, I don’t think even any private home has ever used the budgets that we use to build these interiors.”


Which isn’t to say that there’s no budget.

Big Design, Small Margins
”Budgets are huge, but they are limited,” Lenard says. “We have to really always work within the budget, even if the budget seems really almost infinite. The expectations and the requirements for the quality are so high that suddenly these budgets very soon appear to be restrictive.”

Lenard describes each bespoke boat as an artisan product, the collective work of many collaborators. “There is no industry in building a superyacht. Everything is going down to a man with two hands,” he says.
“Honestly, you have to know that nobody really makes big bucks on designing or building mega yachts. The margins are very small. The majority of that budget goes into materials and into payrolls,” Lenard adds.

“What I like to say is that building a superyacht is probably the biggest injection of private money into the middle class,” he continues. “We are distributing this money between the people, between thousands of people that are building it.”
Alfa Nero, built by Oceanco.
Courtesy image
Serenissima I, built by MengiYay.
Courtesy

Building a Branded Boat
The work of building a fully custom yacht takes time, and not all clients are in the market of waiting. Confronted with the limitations of time and money in a difficult custom market for midsize superyachts, brands and designers are dreaming up semi-custom designs.

Nuvolari Lenard recently unveiled a branded design line, starting with a 52-meter model, in partnership with the Turkish MengiYay shipyard, an approach that leverages the totality of the studio’s design experience. “And then you design each yacht a little bit with the owner to customize it,” Lenard says. “These clients actually go through the same process as if they were building a 100-plus-meter yacht with us. Although the boat is delivered in two, rather than four, years.”


An Interior Approach for an Ever-changing View
New York design firm Bonetti/Kozerski Architecture, which has worked on luxury projects including retail boutiques for Tod’s, the Audemars Piguet House and Pace Gallery, expanded into the yacht interior design space through a collaboration with Italian shipbuilder Benetti. While yacht design only represents a small portion of the business, it’s becoming bigger.

The team is working on the 32nd order of their 40-meter “Oasis” model, a semi-custom design that can accommodate different levels of design adjustments. There’s also a 34-meter version of the boat, and a new explorer series, the B.Yond available as 40-meter and 57-meter boats, launched last year. Another new line will debut at the Monaco Yacht Show later this year.

Common requests for the semi-custom line include material modifications, like switching a marble or stone choice, along with layout tweaks like moving room placement, or adding accessibility accommodations like elevators.
Benetti-built Oasis 40m yacht “Kahala.”
Courtesy photo
Benetti-built Oasis 40m yacht “Kahala.”
Courtesy photo

“Although we never designed boats, we had clients who chartered boats regularly, and we got feedback from them,” Bonetti says. “ It’s a vehicle. It’s not a house, it’s not an apartment — it’s something that moves. And so it shouldn’t necessarily mimic an apartment,” he adds. “When we design a house, we know where the sun is and we know where the views are. This changes all the time [on a boat].”

The studio took a wellness-forward approach to their design, wanting to highlight the connection to water by creating an organic sense of flow between the outdoor and indoor areas, utilizing the same inside and out to create a gentle progression between spaces.

“The same teak that is outside on the deck, we brought it inside,” Bonetti says. “We worked on how the light that comes into the space and materials gets progressively softer as you get into your own private areas, like the owner’s suite. Everything is organic.”
Benetti Oasis 40m yacht “Kahala.”
Courtesy photo
Benetti Oasis 40m yacht “Kahala.”
Courtesy photo

Bringing in Outside Inspiration
French designer Jacques Pierrejean looks to nature for inspiration — and on a boat, inspiration is never far away. “Our intention is to reflect something that we can find close to us when we are outside or close to the sea,” Pierrejean says. “ Because for me it is not a boundary between the exterior or the interior. If you are inside of the yacht, you can feel outside.”

The way that the waves break onto the beach might inspire a carpet, or the reflection of the sun on the water might inform placement of gold leaf on an interior wall to cast light inside a room. He’s created a carpet to give the impression of grass, and added a small garden to accommodate the comfort of canine companions onboard.


Pierrejean’s curved exterior design for Yas, a 141-meter boat currently owned by an Emirati royal, was inspired by the body of a dolphin. The boat, a refit of a former Dutch navy frigate, was rebuilt by ADM Shipyards in the UAE and its superstructure features large panes of glass. “ Most of the time we are looking to design something which is not on the market,” Pierrejean says. “People have to dream with you, and you have to convince them to dream with you.”
Yas, built by ADMShipyards.
Courtesy
Design by Pierrejean Vision.
Courtesy

Six-star Service at Sea
“If you can dream it up and make it buildable, you can create all kinds of things,” says Jonathan Quinn Barnett, who began his career in Europe working with yacht designers Ron Holland and Jon Bannenberg. The accumulation of wealth in the ’70s and ’80s brought clients who were increasingly requesting luxury additions outside the scope of naval architects, paving the path for a class of yacht designers who could marry technical and aesthetic engineering. Moving to Seattle in the early ’90s, Barnett was well-positioned for the area’s tech boom, establishing himself as an American designer with European flair.

Onboard amenities have expanded to include elevators, full-service spas, theaters, underwater observation areas, and practically any other specialized use case that can be imagined.

”You’re building the ultimate off-grid six star hotel,” says Barnett, whose approach to interiors is rooted in designing intimate spaces that feel personal and connected to the surroundings. “You have to have doors that open and to allow you to live on deck,” Barnett says. “And that’s where the joy of being at sea is: really being out in the elements and interacting with the ocean.”

Barnett worked with Paul Allen to design the interiors of his 126-meter Octopus, which launched in 2003 and has served as an expedition vessel, traveling to climates as remote as Antarctica. The boat also featured a music recording studio, used by U2 and Mick Jagger, among others.
A JBQ interior sketch for Octopus.
Interior design by Jonathan Quinn Barnett.

The Art of Being on the Boat
Barnett collaborated with Klara and Larry Silverstein’s “Silver Shalis” motoryacht, incorporating the couple’s collection of glass art; another recent project for a client included the installation of a James Turrell light art piece.

While Barnett primarily works on yacht projects for individuals, he was tasked by Washington-based corporation Boeing to design the interiors for the company’s private yacht, Daedalus, built by Seattle-based shipmaker Delta Marine in the late ’90s. Barnett had photographs from the company’s archive, documenting the internal structure of the wings of a 1930s China Clipper flying boat, blown up and displayed as artwork.

“The interior is both a luxury space, but it also forms a gallery; a place for them to show off some of these pieces,” Barnett says. “The artwork that I’ve had the opportunity to work with is just mind blowing, as you’d see in any museum, and sometimes even rarer.”

Barnett recently designed a semi-custom 42-meter yacht concept with Taiwanese yacht-maker Horizon, which can deliver a boat in around a year depending on customization. “I challenge the shipyard so that my clients’ yacht doesn’t look like the one parked right next to it,” he adds. “If you’re gonna spend $150 million, you don’t want a yacht that looks just like the one that came out a year before.”

“Perfect” is the word that Barnett lands on when describing a well-built and well-designed motor yacht. “It doesn’t matter if it’s ten feet or a hundred meters,” he says. “There’s something about a boat that’s so well cared for and so beautifully manufactured.”
Interior design by Jonathan Quinn Barnett.